Written about 12:30 PM ET Thursday, Oct. 29, 2026. All times Eastern. Prices are intraday and will move. About a 5-minute read.
- The St. Joe Company (JOE) owns about 165,000 acres in Northwest Florida, mostly in Bay, Gulf and Walton counties and largely within 15 miles of the Gulf. It’s a land bank that the company slowly turns into homesites, hotels and leased buildings.
- Q3 revenue slipped 3% to $156.2 million against a one-time sale a year ago, but operating income rose 16%, hospitality posted a third-quarter record and the dividend went up 13% to $0.18.
- The big news was a second phase of Latitude Margaritaville Watersound: 3,557 more acres sold to the joint venture, adding about 3,500 homes, at a land price per home 44% above the 2020 deal.
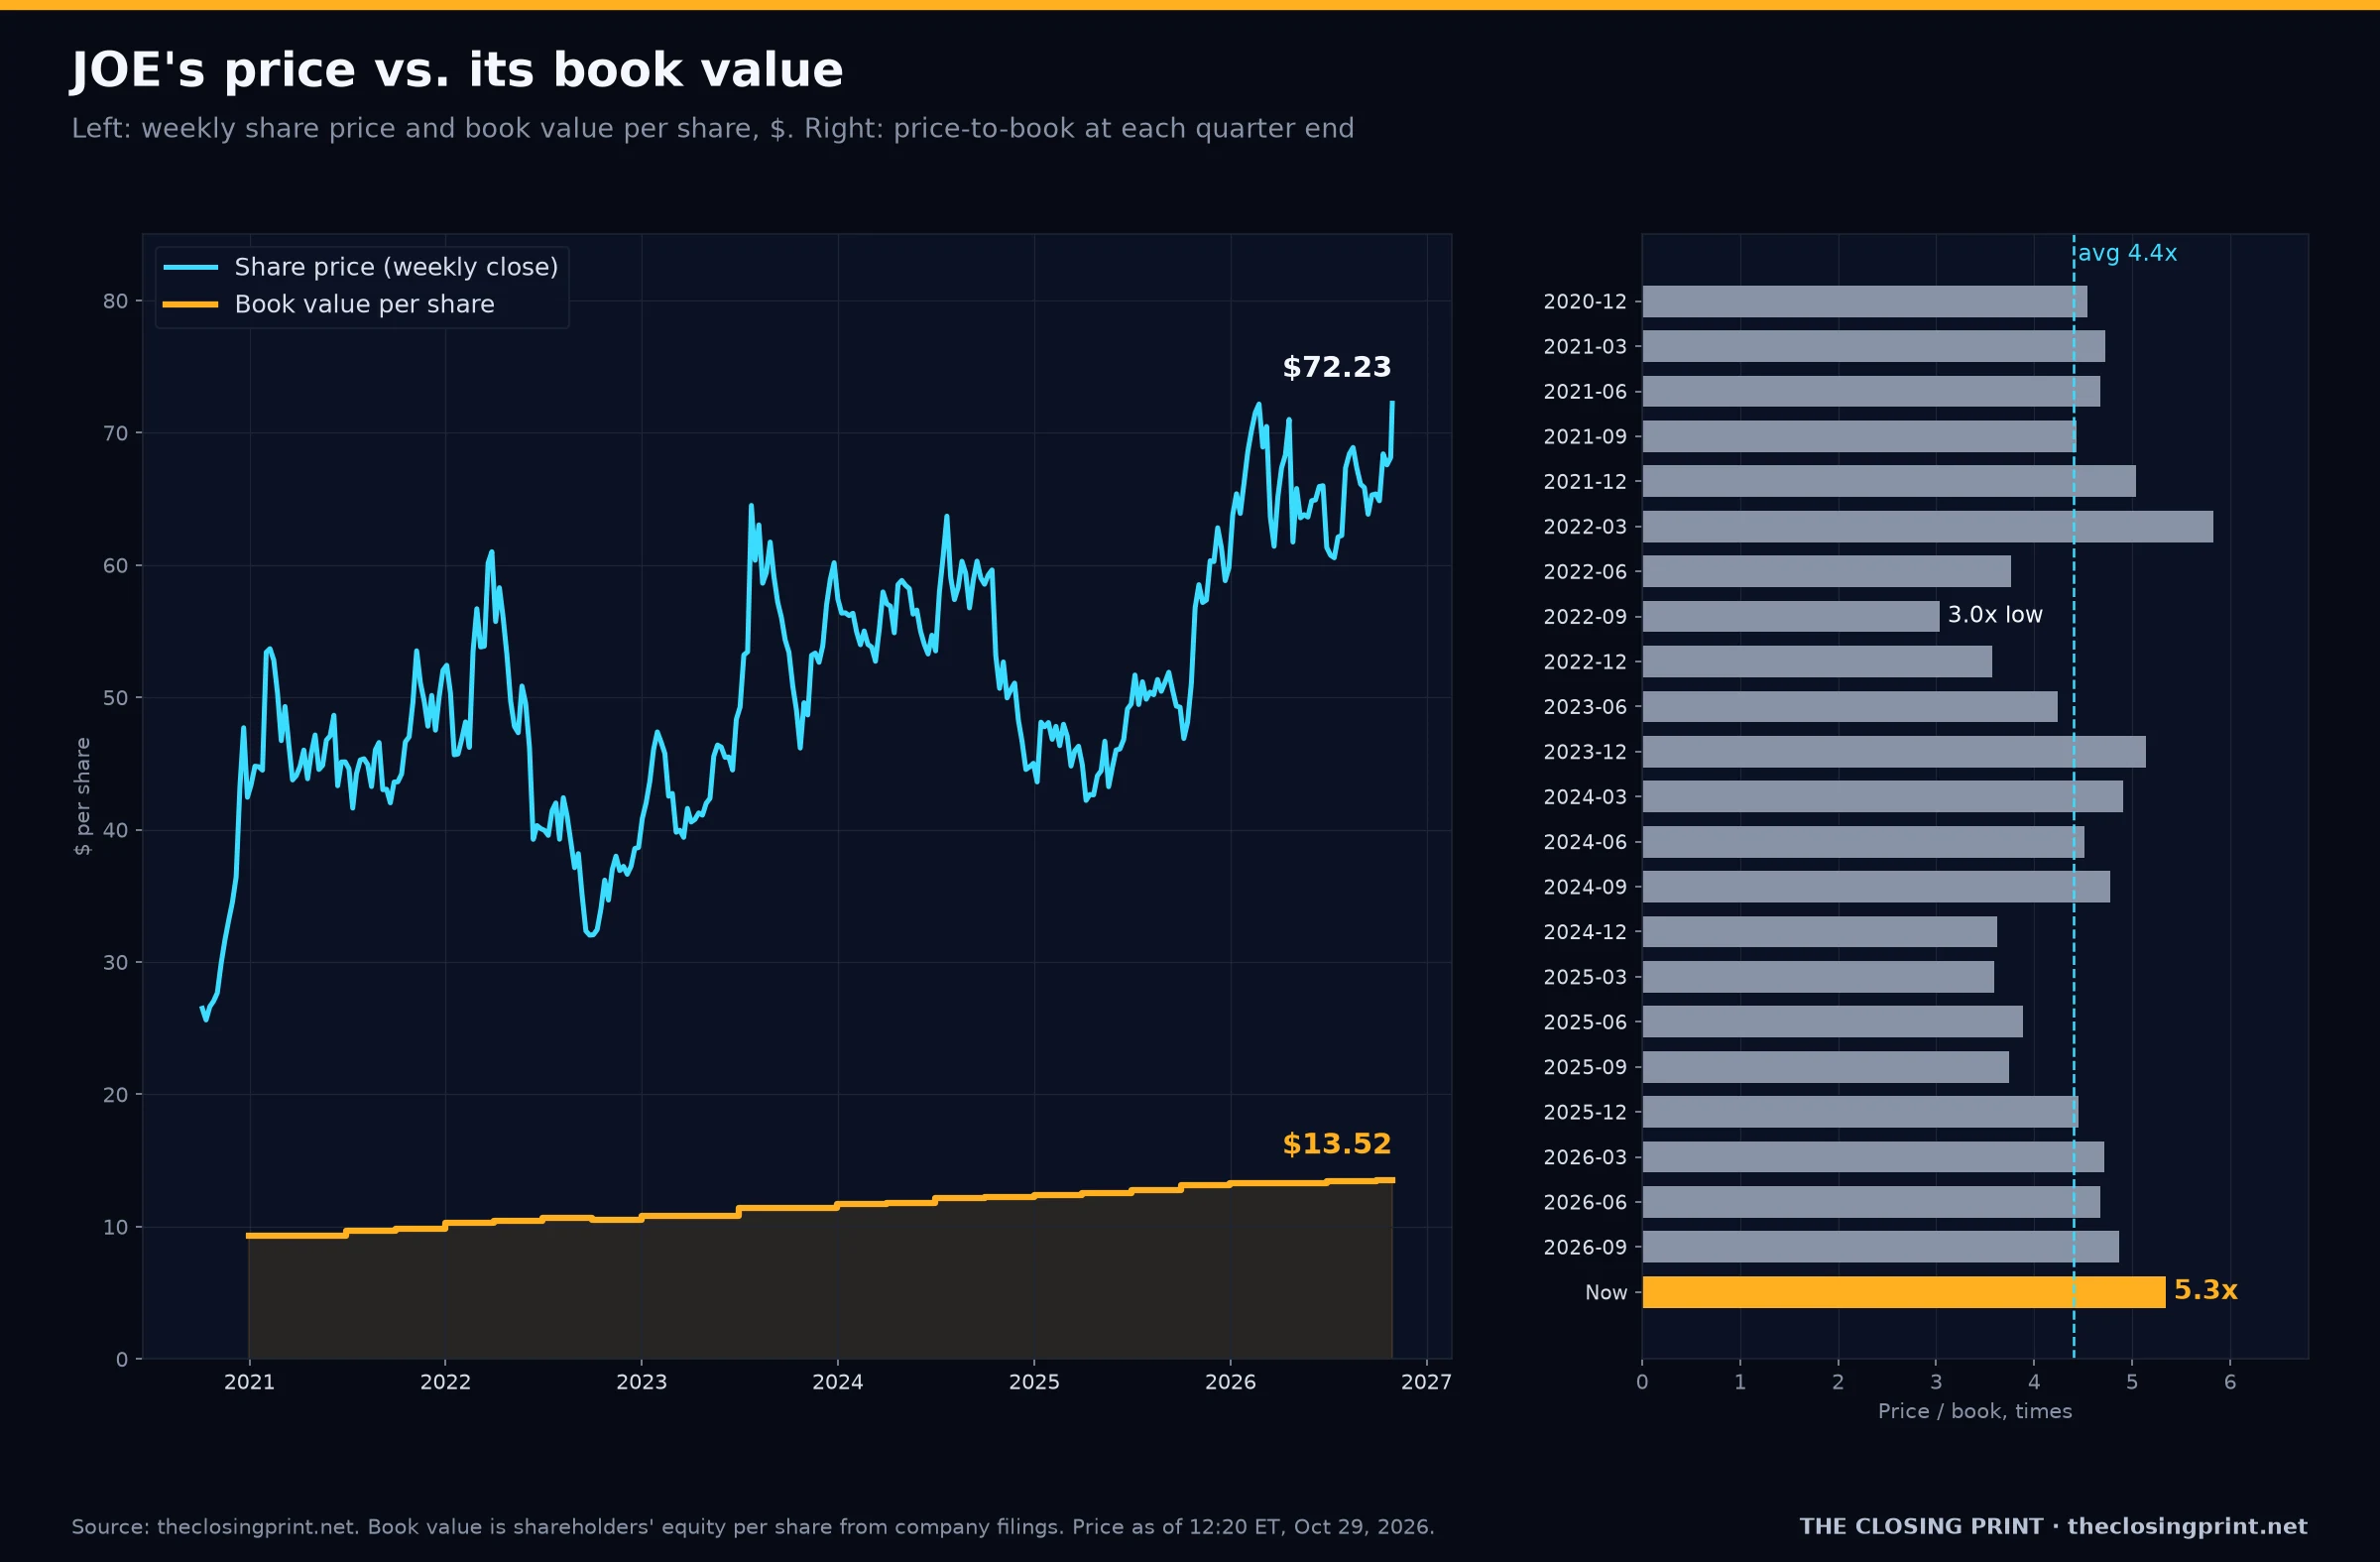
- JOE is up about 6% today to $72.23, its highest weekly close in at least 10 years, and trades at 5.3 times book value, above its 4.4x average since 2020.
- Wick's pick is Base (50%): a high-quality, slow-compounding land story, but the good news is priced in. Hold, and add closer to the low-to-mid $60s.
The land bank
St. Joe was founded in 1936 and still manages its undeveloped land as timber until it’s ready to build on. At the end of 2025 it owned about 165,000 acres, down from 168,000 two years earlier. About 87% of its real estate sits in Bay, Gulf and Walton counties, the stretch of the Panhandle around Panama City Beach.
What makes the acreage valuable is the paperwork. Part of it falls inside the Bay-Walton Sector Plan, which gives St. Joe the right to build more than 170,000 homes, more than 22 million square feet of commercial space and more than 3,000 hotel rooms. The company says its homesite pipeline alone is more than 23,000 lots in various stages of planning.
Three businesses on one map
Residential sells finished homesites to builders and lot buyers across communities like Watersound Origins, Breakfast Point East and the Watersound Camp Creek area. At Sept. 30 it had 3,021 homesites under contract. Leaving out two very large, long-dated deals (1,326 homesites in the Havenry community in the Pigeon Creek area and about 647 in SouthWood), the other 1,048 are expected to bring in about $103.6 million plus residual payments over several years. A new PulteGroup community of about 3,000 homes in Pigeon Creek is expected to break ground in early 2027.
The star asset is Latitude Margaritaville Watersound, a 55-and-older community run as a joint venture. Since sales started in 2021 it has closed 2,426 homes, and it had 222 more under contract at an average price of about $635,000. New contracts rose 49% in the quarter to 106. St. Joe gets paid for land as each home sells, and it shares in the venture’s profit.
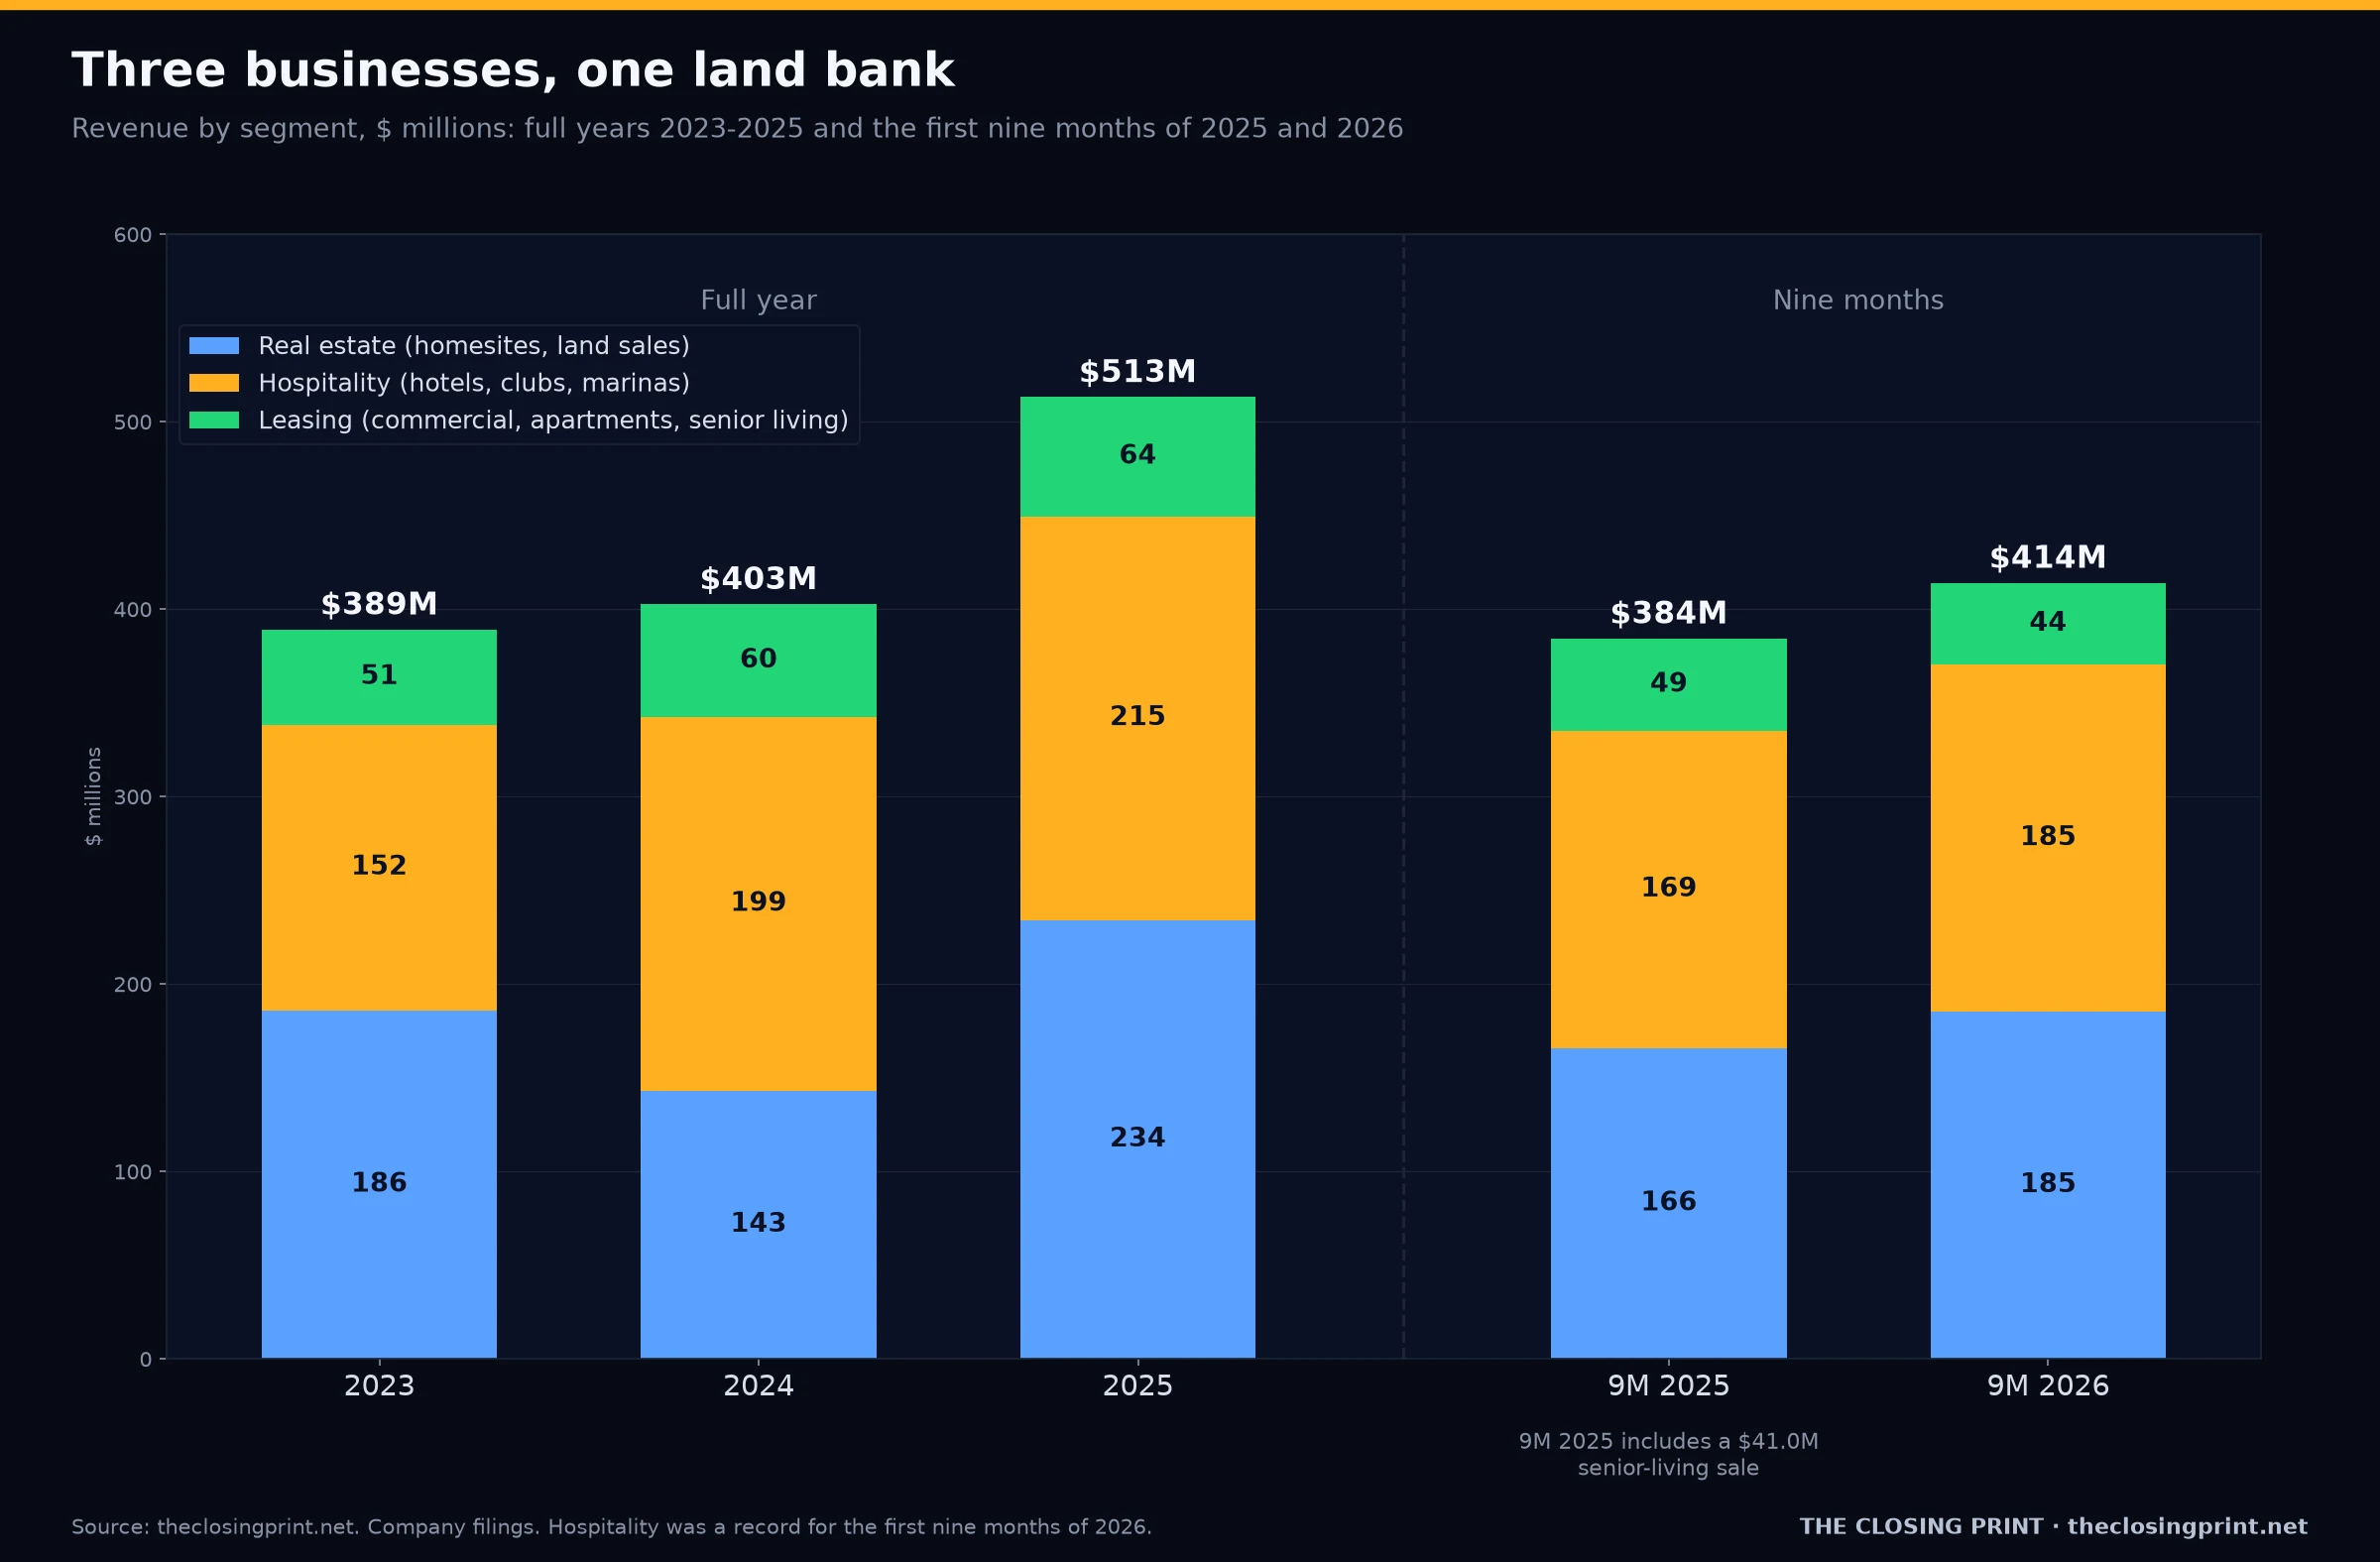
Hospitality is now the steadiest engine: 12 hotels with 1,298 rooms, the Watersound Club with 3,831 members (up 253 from a year ago), marinas and a new weddings and events business. Leasing covers about 1.15 million square feet of shops, offices, medical space, apartments and self-storage, 97% leased, with another 85,946 square feet under construction and 78% of that pre-leased.
The third quarter
St. Joe reported after the close on Wednesday, Oct. 28. The headline numbers look flat, but they’re distorted by last year’s $41.0 million sale of the Watercrest senior-living property. Strip that out and the quarter grew. Operating income rose 16% to $61.5 million, and hospitality gross margin improved to 37% from 35%, with club revenue up 14% and hotel revenue up 7%. Through nine months, revenue is up 8% to $414.1 million and EPS is up to $1.60 from $1.48.
| Q3 2026 | Result | vs. Q3 2025 |
|---|---|---|
| Total revenue | $156.2M | -3% |
| Real estate | $76.1M | -9% |
| Hospitality | $66.0M (Q3 record) | +9% |
| Leasing | $14.1M | -16% |
| Operating income | $61.5M | +16% |
| Net income / EPS | $36.9M / $0.65 | -5% / was $0.67 |
| Nine-month EPS | $1.60 | +8% / was $1.48 |
The quarter’s most important number is the land sale. St. Joe sold 3,557 acres in the West Bay Creek area to the Latitude Margaritaville venture for a contract value of $50.4 million, paid at about $14,400 per home as the homes sell, against $10,000 per home in the original 2020 deal. That takes the planned community to about 7,200 homes. Because the money arrives over many years, only the $31.4 million present value was booked as revenue now. St. Joe expects $40.8 million of pre-tax income from the sale over time.
One soft spot: venture home closings fell to 67 from 82, and nine-month closings dropped to 236 from 411 as the first phase sells out. Rising contracts point to timing between phases rather than weak demand, but it’s the number to check next.
Capital allocation
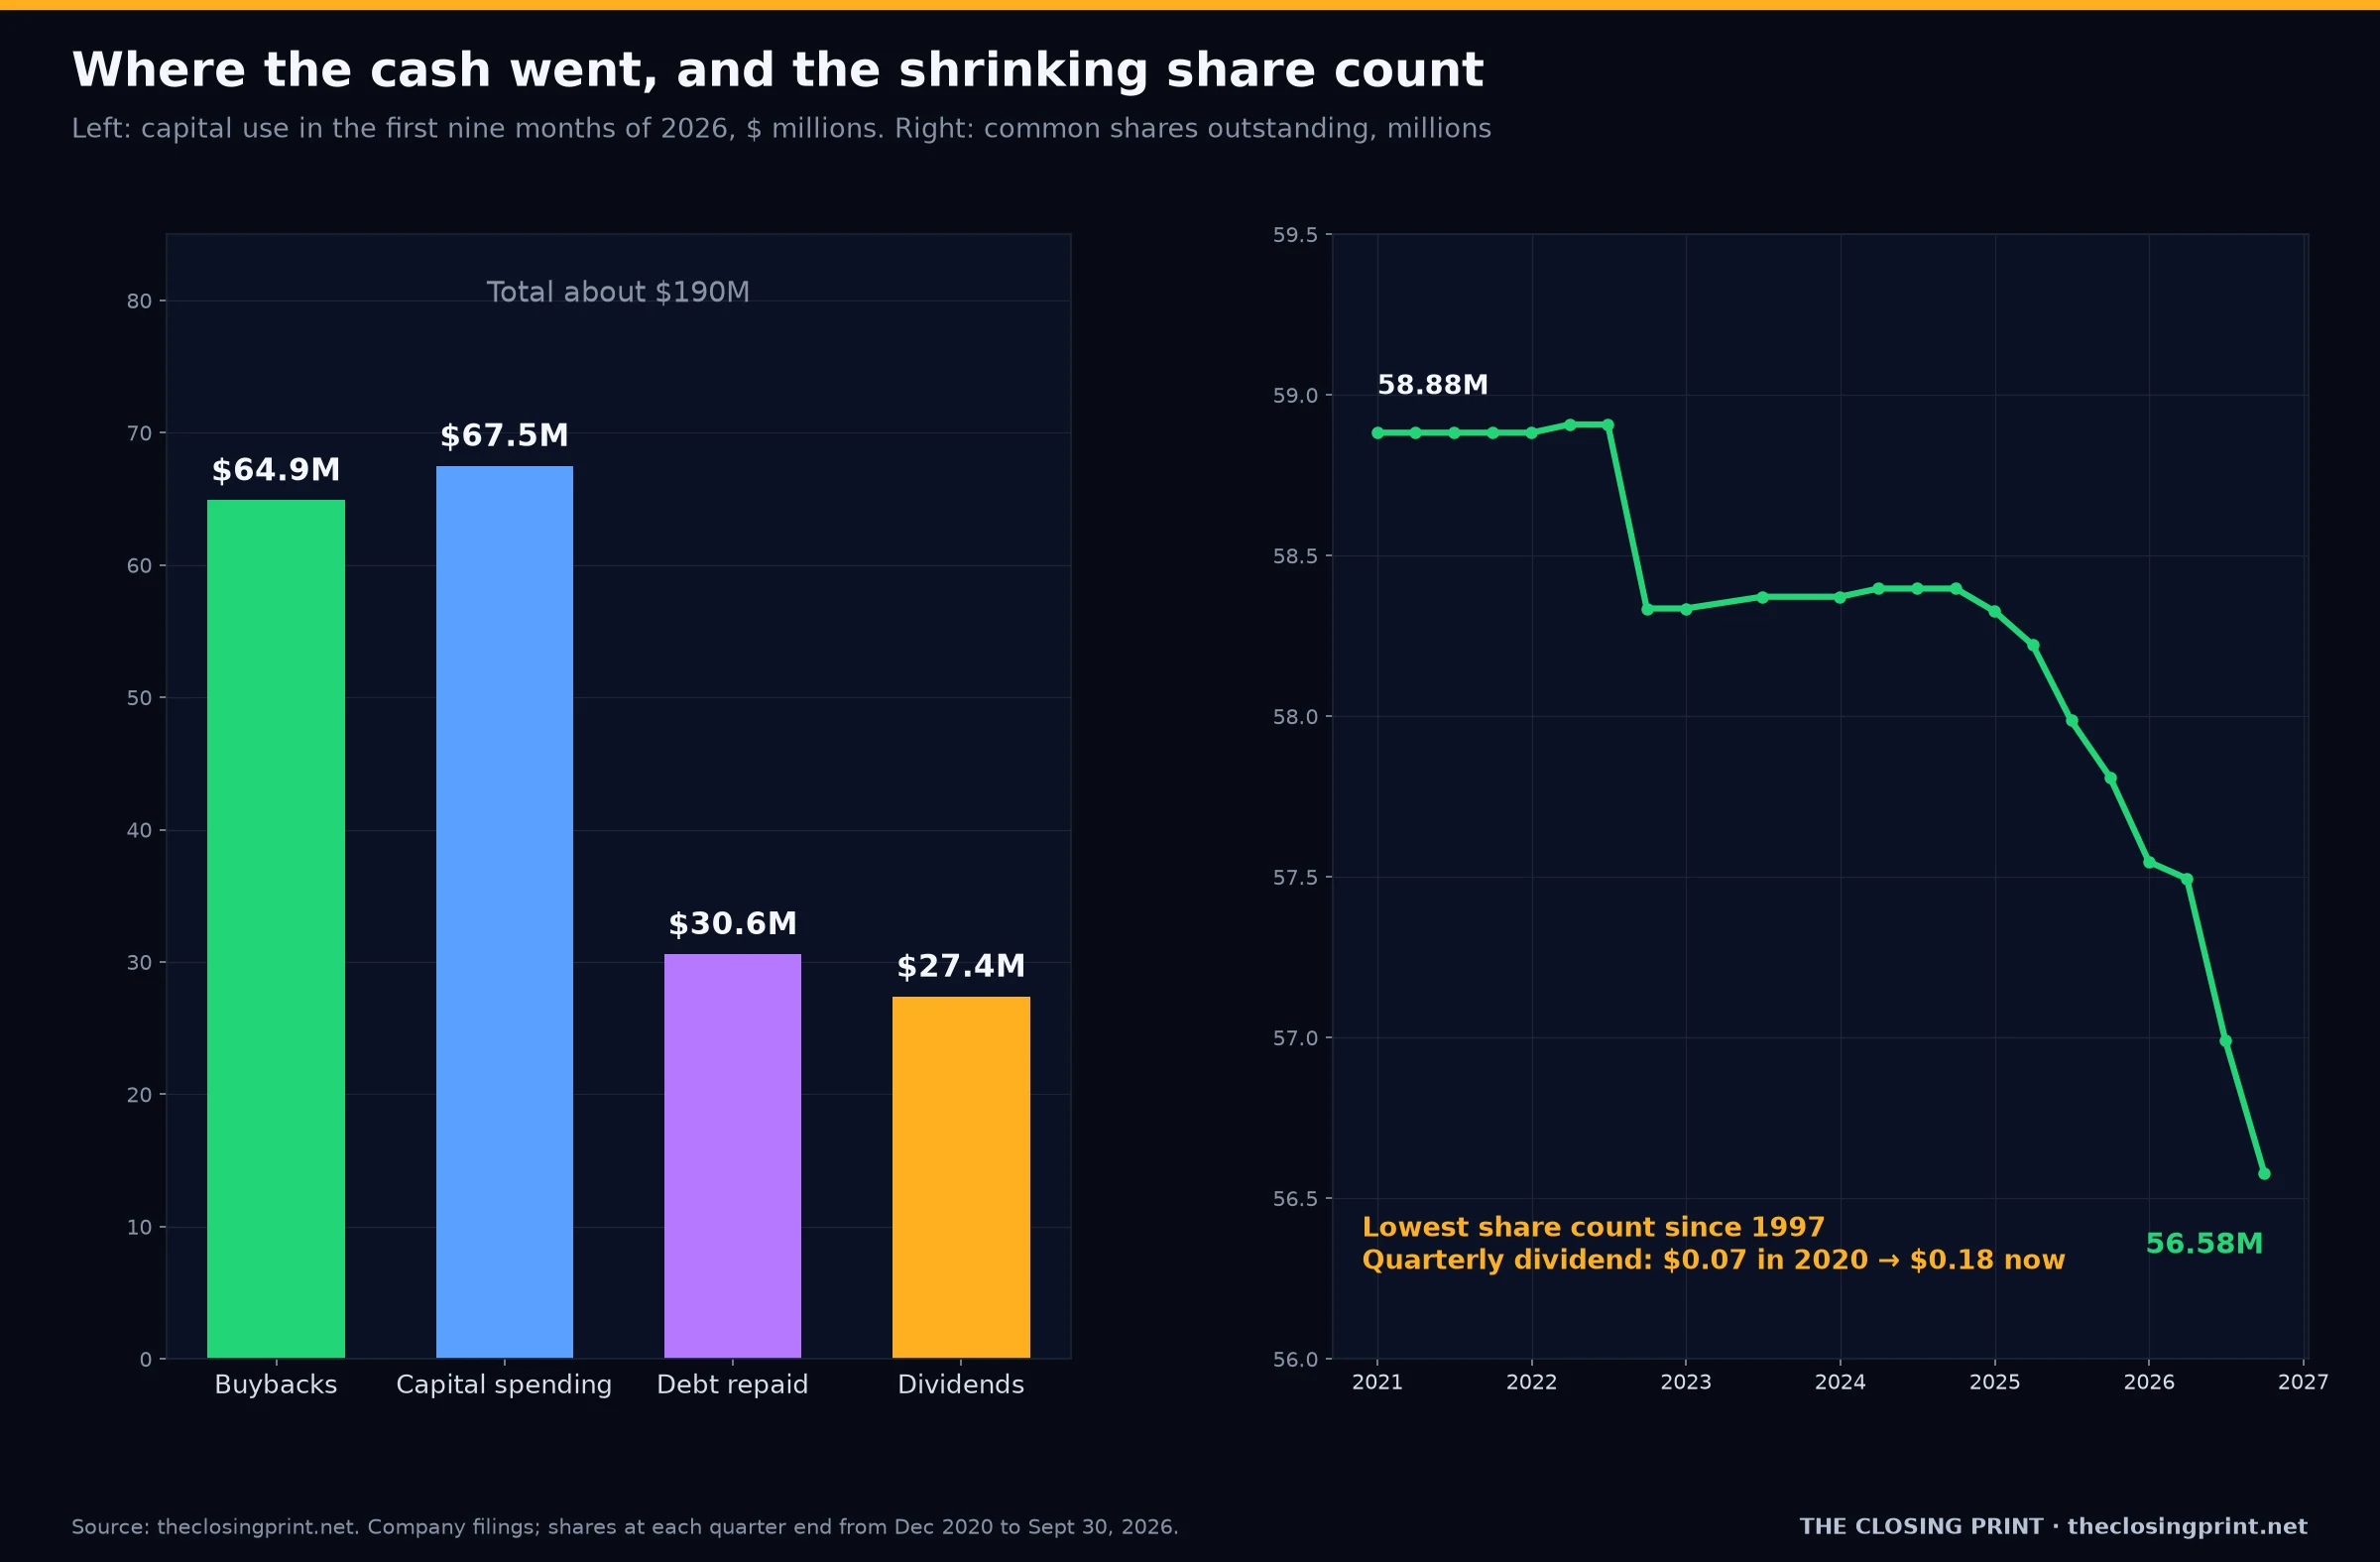
Buybacks have taken a bigger share of cash this year. In the first nine months St. Joe spent $67.5 million on capital projects, $64.9 million on buybacks (988,637 shares, up from $24.9 million a year earlier), $30.6 million paying down debt and $27.4 million on dividends. The share count fell to 56.58 million, the lowest since 1997. The new $0.18 quarterly dividend is payable Dec. 11 to holders of record on Nov. 12. It was $0.07 when the current program started in 2020.
The balance sheet is conservative for a developer. Debt was $361.7 million at Sept. 30 against $117.9 million of cash, and the company paid down $8.8 million of it in the quarter. Fairholme Capital Management and its founder Bruce Berkowitz owned 33.6% of the shares as of the 2026 proxy, so buybacks also make the float smaller.
Valuation
Book value carries land bought decades ago at very low cost, so the question is how far above book the stock trades. At $72.23, JOE is at 5.3 times book value of $13.52 a share, above its 4.4x average since 2020 and well above the 3.0x low in September 2022, when mortgage rates jumped. It’s about 34 times trailing earnings and yields about 1%.
| Measure | Value |
|---|---|
| Share price (12:20 PM ET) | $72.23, +6.0% today |
| Market value | about $4.09 billion |
| Book value per share (Sept. 30) | $13.52 |
| Price / book | 5.3x (average since 2020: 4.4x; low: 3.0x in Sept. 2022) |
| Price / trailing earnings | about 34x (about $2.13 a share over four quarters) |
| Dividend yield | about 1.0% on the new $0.18 quarterly rate |
| Net debt | about $244 million ($361.7M debt less $117.9M cash) |
A rough look per acre: the market values the whole company, net of debt, at about $4.3 billion, or roughly $26,000 for each of the 165,000 acres. That figure also buys the hotels, clubs and leased buildings, so it isn’t a pure land price. For comparison, the September sale priced raw land at about $14,200 an acre on a contract basis, paid out over time, and that’s land near the most active part of the map. We read this as the market already paying for a good deal of future development.
Rates matter here. See our Fed decision preview and today’s pre-market summary.
Risks
- Hurricanes. About 90% of the land is within 15 miles of the Gulf. Hurricane Michael destroyed timber in 2018, St. Joe doesn’t insure its timber, and its hurricane coverage is capped per storm. Hurricane Isaias made landfall near Destin, just west of Walton County, in early October; the quarterly filing didn’t mention it.
- Insurance costs. The company flags tight capacity in Florida’s insurance market. Higher premiums hit hotels and buyers alike.
- A Florida housing slowdown. A weaker market would slow lot sales and venture closings.
- Rates. The 10-year Treasury yield is near 5.0%. Higher mortgage rates hurt buyers, and higher bond yields make a 1% dividend yield less appealing.
- Concentration. One region, one storm track, and a top holder with about a third of the shares.
- Lumpy accounting. Land sales and joint-venture timing swing quarterly results, as this quarter showed.
Scenarios and Wick's pick


Wick's pick: Base (50%). St. Joe is now a real operating business, with hotels, clubs and leasing bringing in steady cash, and the land sale shows its raw acreage is gaining value. But after a 6% jump to the top of its range, at more than five times book, a lot of the next few years is already in the price. We rate JOE a Hold and would add closer to the low-to-mid $60s, about where it traded for most of 2026.
What would change our view: faster venture closings and a clear start date at Pigeon Creek (more bullish), or a damaging storm, falling club membership or a stall in lot contracts (more bearish).
What to watch
- Tue Nov 10, 8:30 AM: October CPI, a read on where mortgage rates go next.
 .ics

- Thu Nov 12: record date for the St. Joe $0.18 dividend..ics
- Mon Nov 30: the Atlantic hurricane season ends..ics
- Wed Dec 9, 2:00 PM: FOMC decision with new projections..ics
- Fri Dec 11: St. Joe pays its $0.18 dividend..ics
- Wed Feb 24, 2027 (estimated): St. Joe Q4 2026 results, with full-year venture closings and the 2026 acreage count..ics
Market data and opinions by Wick. This post is informational only and is not financial advice. Scenario odds and ratings are our estimates. Prices are intraday as of the time noted and may have changed.
Add all 6 events to calendar (.ics) Times are ET. Each event has a 1-day reminder. Estimated dates are marked.