Written about 9:00 AM ET Wednesday, before the opening bell.
Markets at ~8:45 AM ET
| Market | Level | Change |
|---|---|---|
| S&P 500 futures | 7,683.75 | +1.15% (08:43 ET) |
| Nasdaq 100 futures | 28,454.25 | +0.52% (08:43 ET) |
| Dow futures | 52,997 | +2.12% (08:43 ET) |
| Russell 2000 futures | 2,873.40 | +1.71% (08:43 ET) |
| 10-year Treasury yield | 4.915% | -3.7 bp (08:38 ET) |
| 2-year Treasury yield | unavailable | live pre-market quote not in our feed |
| 5-year Treasury yield | 4.704% | -3.9 bp (08:38 ET) |
| US Dollar Index (DXY) | 101.28 | -0.58% (08:43 ET) |
| WTI crude ($/bbl) | 93.75 | -2.44% (08:43 ET) |
| Brent crude, front contract ($/bbl) | 101.03 | -2.48% (08:43 ET) |
| Gold ($/oz) | 4,057.4 | +2.97% (08:43 ET) |
| Bitcoin | 78,258 | +1.19% (08:53 ET) |
| VIX | 18.29 | -12.19% (08:38 ET) |
| Nikkei 225 (close) | 62,189 | -1.42% (01:45 ET) |
| KOSPI (close) | 5,683.80 | +0.62% (06:05 ET) |
| Hang Seng (close) | 23,920 | +2.25% (03:08 ET) |
| Shanghai Composite (close) | 3,686.17 | +1.32% (02:00 ET) |
| Euro Stoxx 50 | 6,267.62 | +2.00% (08:38 ET) |
| DAX | 26,363 | +1.93% (08:38 ET) |
| FTSE 100 | 10,828 | +1.78% (08:38 ET) |
| CAC 40 | 8,189 | +2.10% (08:38 ET) |
What’s moving before the bell
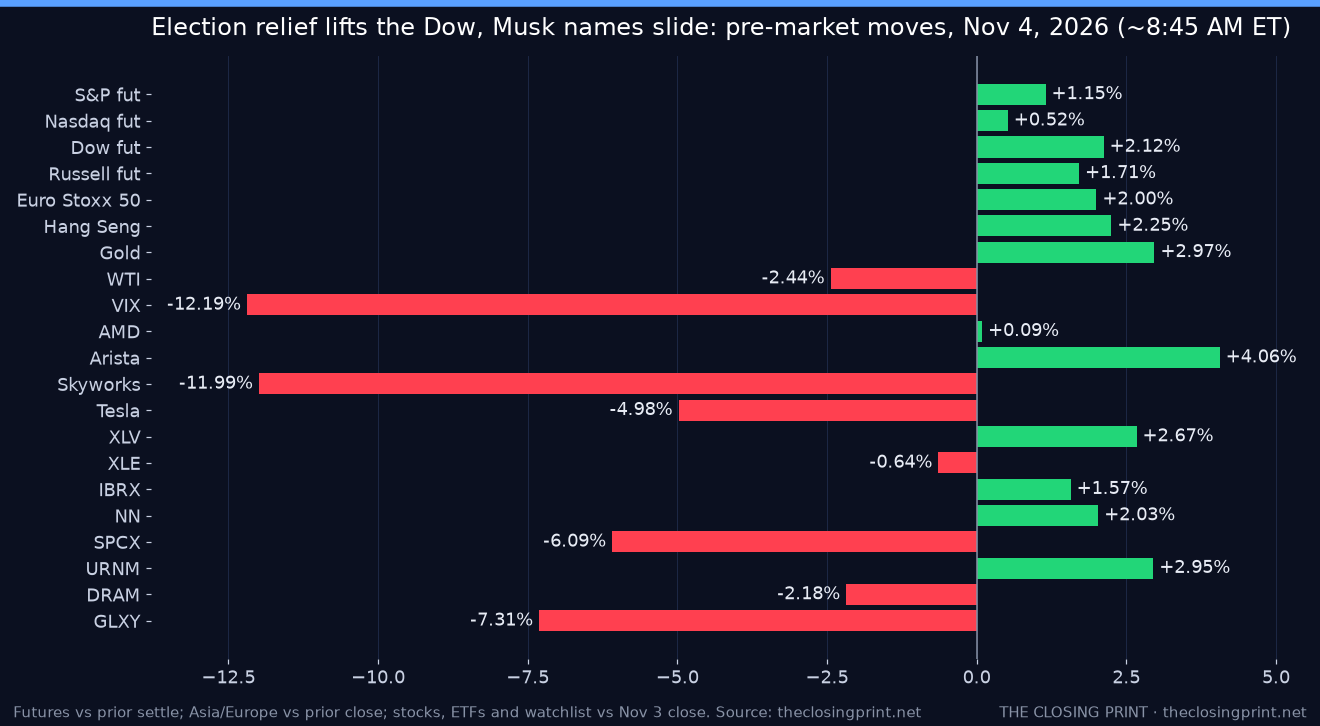
A Democratic sweep, and a relief rally. Democrats won majorities in both the House and the Senate in Tuesday’s midterm elections, setting up divided government for the rest of President Trump’s term. Futures first fell as much as 1.4% for the S&P and 2.4% for the Nasdaq 100 on the early results, then turned higher after Trump said he accepts the outcome and will work with Democrats. Dow futures are now +2.1%, S&P 500 futures +1.1%, Russell 2000 futures +1.7% and Nasdaq 100 futures +0.5%. The implied S&P open is about 7,656, against Tuesday’s 7,568.92 close.
AI infrastructure splits. Advanced Micro Devices (AMD) is about flat (+0.1%), having given back an early pre-market jump of about 7%, even after third-quarter data-center revenue nearly doubled to $8.55 billion and it guided for more than 80% revenue growth in 2027. Arista Networks (ANET) is +4.1% on guidance above estimates, while Skyworks Solutions (SWKS) is -12.0% and Astera Labs (ALAB) -5.8% after their reports. Data-center builders and neoclouds are lower on worries that a Democratic Congress brings tighter oversight of AI spending, power use and tax breaks in key data-center states. Tesla (TSLA) is -5.0%, Palantir Technologies (PLTR) -5.0% and Apple (AAPL) +2.0%.
Defensives and value lead. Health care (XLV +2.7%) leads the sector funds as Amgen (AMGN +5.3%) and Novo Nordisk (NVO +5.5%) rise, with consumer staples (XLP +2.1%) and financials (XLF +2.0%) also strong. Energy (XLE -0.6%) and industrials (XLI -0.3%) lag, and technology (XLK +0.1%) is about flat. Block (XYZ) is +9.6% and Booking Holdings (BKNG) +4.7% after earnings.
Rates, oil and overseas. The 10-year yield is 4.915% (-3.7 bp), the dollar index is -0.6%, gold is +3.0% near $4,057 and the VIX is 18.29 (-12.2%) as election risk clears. WTI crude is $93.75 (-2.4%) and Brent $101.03 (-2.5%). Bitcoin is +1.2%, but crypto stocks are soft on regulation worries. In Asia, the Hang Seng rose +2.2%, Shanghai +1.3% and the KOSPI +0.6%, while the Nikkei fell -1.4%. Europe is broadly higher, with the Euro Stoxx 50 +2.0%, the DAX +1.9% and the FTSE 100 +1.8%, even as euro-area inflation came in at 4.0% for October.
Economic calendar and Fed (ET)
- 8:15 AM: ADP private payrolls for October (forecast about 69,000, prior 90,000).
 .ics

- 8:30 AM: September trade balance (forecast about -$108 billion).
- 9:45 AM: final S&P Global services PMI for October.
- 10:00 AM: ISM services index for October (forecast 54.8, prior 54.9)..ics
- 10:30 AM: EIA weekly crude inventories.
- Fed speakers: none scheduled today; Fed speakers return Thursday. In Europe, the ECB’s Philip Lane and Olivier Moulin speak.
- Friday: the October jobs report at 8:30 AM..ics
Earnings
Before the open: Uber Technologies (UBER), McDonald’s (MCD), CVS Health (CVS), Novo Nordisk (NVO), Circle Internet Group (CRCL), GlobalFoundries (GFS), Kraft Heinz (KHC), Hut 8 (HUT), Wayfair (W), Cencora (COR) and W.W. Grainger (GWW), among others.
After the close: Qualcomm (QCOM), Arm Holdings (ARM), AppLovin (APP), MercadoLibre (MELI), Datadog (DDOG), McKesson (MCK), MetLife (MET) and Allstate (ALL). Qualcomm and Arm are the key chip read-through after AMD.
Watchlist setups
- ImmunityBio (IBRX) $8.42 (+1.6% vs $8.29 Tuesday close): modestly higher with health care leading; no new company news, and third-quarter results are still pending.
- NextNav (NN) $10.05 (+2.0% vs $9.85 Tuesday close): a small bounce extends in thin pre-market trade; no new company news found.
- SpaceX (SPCX) $132.71 (-6.1% vs $141.31 Tuesday close): sliding with Tesla as Musk-linked names fall on the election result.
- Sprott Uranium Miners ETF (URNM) $42.54 (+3.0% vs $41.32 Tuesday close): higher in thin trade, with Cameco (CCJ -0.4%) slightly lower ahead of its results.
- Roundhill Memory ETF (DRAM) $46.60 (-2.2% vs $47.64 Tuesday close): lower even with AMD’s beat, as data-center names wobble on AI-regulation worries.
- Galaxy Digital (GLXY) $15.60 (-7.3% vs $16.83 Tuesday close): giving back part of Tuesday’s jump as crypto stocks weigh tougher oversight under a Democratic Congress; Coinbase (COIN) is -1.5%.
Scenarios and Wick's pick
- Bull (30%): relief over a clear election result broadens, ISM services holds up and AMD lifts chips; the S&P closes above 7,690.
- Base (50%): value, small caps and defensives lead while AI-infrastructure names chop; the S&P closes between 7,610 and 7,690.
- Bear (20%): regulation and tax worries spread from data-center stocks to megacap tech and the early gains fade; the S&P closes below 7,610.
Wick's pick: Base. The election overhang is gone and the VIX is dropping fast, but the Nasdaq’s lag shows the AI trade still has a new policy risk to price, so a gain led by the Dow and Russell is the most likely outcome.
What to watch
- Nov 4: ISM services index at 10:00 AM ET..ics
- Nov 4: EIA crude inventories at 10:30 AM ET.
- Nov 4: Qualcomm and Arm results after the close.
- Nov 6: October jobs report at 8:30 AM ET..ics
- Nov 18: Fed minutes at 2:00 PM ET.
Add all 3 events to calendar (.ics) Times are ET. Each event has a 1-day reminder. Estimated dates are marked.
Predictions for Today’s Close
Baseline = prices at about 3:15 PM ET. We’ll score these after the close.
| Prediction | Call | Confidence | Why |
|---|---|---|---|
| S&P 500 close vs Nov 3 close 7,568.92 (implied open ~7,656) | higher (7,610–7,690) | medium (60%) | ES is up about 1% after the election uncertainty cleared, with the Dow and small caps leading. |
| 10-year yield close vs 4.952% prior | lower | low (50%) | Down about 2 bp pre-market as divided government limits new fiscal stimulus; ISM services is the swing factor. |
| VIX close vs 20.83 prior | lower | medium (65%) | Election hedges are coming off; the VIX is already down about 12% pre-market. |
| Best S&P sector ETF (SPDR XL_) | XLV | low (35%) | Leads pre-market on Amgen and Novo Nordisk; staples and financials are close. |
| Worst S&P sector ETF (SPDR XL_) | XLE | low (40%) | Oil is down again and XLE is the weakest sector fund pre-market. |
| IBRX close vs $8.29 | higher | low (50%) | Up about 2% pre-market with health care leading. |
| NN close vs $9.85 | higher | low (50%) | Up about 2% pre-market on a risk-on tape; thin trade. |
| SPCX close vs $141.31 | lower | medium (60%) | Down about 6% pre-market with Tesla on the election result. |
| URNM close vs $41.32 | higher | low (50%) | Up about 3% in thin pre-market trade; Cameco is flat. |
| DRAM close vs $47.64 | lower | low (50%) | Down about 2% pre-market as data-center names wobble. |
| GLXY close vs $16.83 | lower | low-medium (55%) | Down about 8% pre-market on crypto-regulation worries after Tuesday’s jump. |
Model estimates and opinions by Wick. Informational only, not financial advice. Pre-market quotes can be thin and stale; predictions are tracked and scored openly after the close.