Written about 5:00 PM ET Wednesday. All times Eastern. This post grades the calls in this morning’s Pre-Market Summary.
Closing levels
| Market | Close | Day change |
|---|---|---|
| S&P 500 | 7,688.62 | +1.58% |
| Nasdaq Composite | 25,736.51 | +1.44% |
| Dow Jones Industrial Average | 53,356.12 | +3.03% |
| Russell 2000 | 2,856.95 | +1.58% |
| 10-year Treasury yield | 4.90% | -5 bp |
| 2-year Treasury yield | 4.58% | -3 bp |
| Dollar index (DXY) | 101.53 | -0.34% |
| WTI crude, front month ($/bbl) | 88.04 | -8.38% |
| Brent crude ($/bbl) | 94.63 | -8.66% |
| Gold ($/oz, futures) | 4,072.20 | +3.34% |
| Bitcoin (about 5:13 PM ET, vs Tuesday 5:12 PM) | $80,378 | +3.40% |
| VIX | 16.61 | -20.26% |
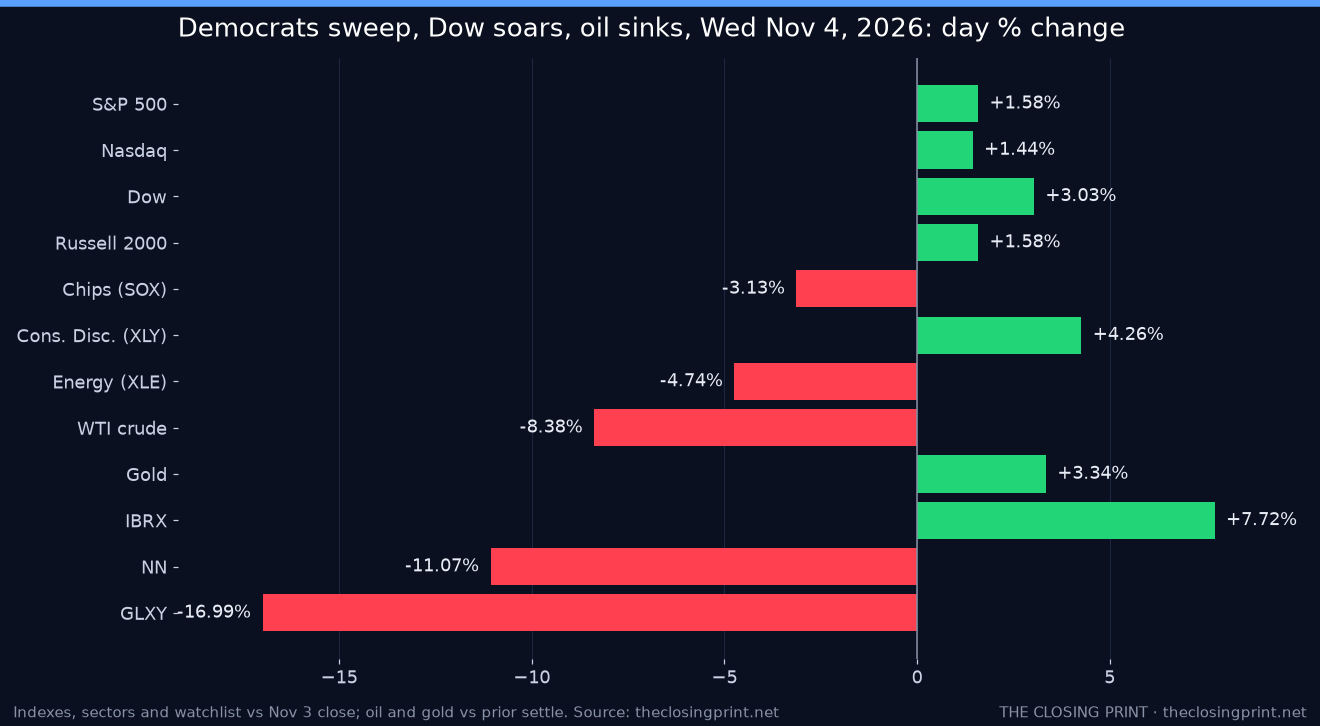
Democrats won both the House and the Senate, and the market treated the result as a relief: the uncertainty is over, and a divided government is expected to slow new fiscal spending and borrowing. Breadth was strong, with 376 S&P 500 stocks up and 127 down. The rally was lopsided inside tech, though. Cash-rich giants rose, with Microsoft (MSFT) up 6.7%, Amazon.com (AMZN) up 6.1% and Apple (AAPL) up 5.3%, while the Philadelphia chip index fell 3.1% to a six-month low. Democrats gained in key data-center states such as Texas and Georgia, and traders bet that a slower AI buildout will hurt the companies building it more than the companies paying for it. Oil plunged on bets that the new Congress will push for a quicker end to the Iran war, which pulled yields and the dollar lower and sent gold up 3.3%.
Best and worst sectors
| Sector | ETF | Day % |
|---|---|---|
| Consumer Discretionary | XLY | +4.26% |
| Financials | XLF | +3.51% |
| Communication Services | XLC | +3.47% |
| Consumer Staples | XLP | +3.36% |
| Real Estate | XLRE | +3.32% |
| Health Care | XLV | +3.06% |
| Materials | XLB | +2.49% |
| Utilities | XLU | +0.44% |
| Technology | XLK | -0.01% |
| Industrials | XLI | -1.09% |
| Energy | XLE | -4.74% |
Consumer discretionary (+4.26%) led, helped by Amazon and a strong report from Booking Holdings (BKNG), with financials (+3.51%) and communication services (+3.47%) next. Energy (−4.74%) was the worst sector by far as crude sank. Industrials (−1.09%) fell on data-center contractors and defense names, and technology was flat because chip losses offset gains in Microsoft and Apple.
The data and what moved markets
- Democrats sweep Congress. The midterm result removed the main source of uncertainty. Small caps and the Dow led, and defense stocks fell.
- ADP beat. Private employers added 86,000 jobs in October, above the 67,000 expected.
- ISM services slipped. The October index eased to 54.5, just under the 54.8 consensus. Its prices-paid gauge fell to 73.0 against expectations for a rise to 74.6, a welcome sign on inflation.
- Trade deficit narrowed. The September gap shrank to $105.0 billion, better than the $107.9 billion expected, a plus for third-quarter growth.
- Oil collapsed. WTI fell 8.4% to about $88 on hopes that the new Congress pushes for a faster end to the Iran war.
- Data-center selloff. Chipmakers, memory, power producers and data-center operators fell on fears that the AI buildout slows. Micron Technology (MU) lost 7.0% and Vistra (VST) 13.8%.
Top gainers and losers (S&P 500)
| Stock | Close | Day % | Why |
|---|---|---|---|
| Mosaic (MOS) | $21.62 | +17.37% | Third-quarter revenue edged past estimates despite a wider loss, and investors focused on a cheaper fourth-quarter sulfur contract, cost cuts and a refinancing that pushes debt maturities out. |
| Block (XYZ) | $87.63 | +15.30% | Beat third-quarter estimates with adjusted earnings of $1.13 a share on 22% gross-profit growth, raised its 2026 outlook and gave an upbeat early 2027 view. |
| Zimmer Biomet (ZBH) | $110.15 | +13.49% | Topped third-quarter estimates and raised its full-year sales and profit outlook. |
| Fidelity National Information Services (FIS) | $29.76 | -23.67% | Cut its full-year adjusted profit outlook to $5.82–$5.89 a share from $6.15–$6.24, sending the stock to a five-year low. |
| Trimble (TRMB) | $54.25 | -17.31% | Lowered its 2026 recurring-revenue growth forecast to about 10% from 12%–14%. |
| Comfort Systems USA (FIX) | $1,091.31 | -15.08% | The data-center contractor fell with the AI-infrastructure group after Democrats gained in key data-center states. |
Earnings so far, and after the bell
During the session: Booking Holdings rose 9.8% after strong results, McDonald’s (MCD) gained 6.5% as profit beat even though revenue missed, and Novo Nordisk (NVO) rose 5.0% after beating and raising its 2026 outlook. CVS Health (CVS) fell 12.5% after saying it will split into two companies. Advanced Micro Devices (AMD) kept only a 1.0% gain after Tuesday night’s beat as the chip group sold off.
After the close: AppLovin (APP), which had already closed up 10.7%, jumped roughly 16% to 21% late after third-quarter earnings of $4.30 a share beat the $4.04 estimate on revenue of $2.18 billion, and its fourth-quarter revenue outlook of $2.37–$2.40 billion topped the $2.25 billion consensus. Coherent (COHR) rose about 5% on a beat-and-raise tied to AI optical demand. Qualcomm (QCOM) and Snap (SNAP) also reported.
Our watchlist
| Name | Close | Day % | Why today |
|---|---|---|---|
| ImmunityBio (IBRX) | $8.93 | +7.72% | Said the first patients in Europe, in Germany and Austria, have been treated with Anktiva plus BCG, and the stock ran up late in the session ahead of third-quarter results due Thursday. |
| NextNav (NN) | $8.76 | -11.07% | Fell to a 52-week low with no fresh company news we could confirm, extending Monday’s 16.5% drop. |
| SpaceX (SPCX) | $135.92 | -3.81% | Fell with Tesla (TSLA) as newly elected Democrats who have criticized the data-center buildout won control; SpaceX runs AI computing sites in Tennessee and Mississippi. |
| Sprott Uranium Miners ETF (URNM) | $41.22 | -0.24% | Roughly flat after an early gain faded as power producers sold off; Cameco (CCJ) fell 1.2%. |
| Roundhill Memory ETF (DRAM) | $45.11 | -5.31% | Fell with memory stocks, including Micron and Sandisk (SNDK), on fears of a slower data-center buildout. |
| Galaxy Digital (GLXY) | $13.97 | -16.99% | Fell to a 52-week low as data-center operators were hit hard, with Hut 8 down 23% and IREN down 11%; Galaxy’s Helios campus is in Texas, a state where Democrats gained. |
Predictions vs Reality — 8/11 hits, 0 partial, 3 misses
Graded against Nov 3 closes. Sectors are ranked by SPDR sector ETF day change.
| Prediction | Our call | Actual | Result | Why |
|---|---|---|---|---|
| S&P 500 close vs Nov 3 close 7,568.92 | higher, 7,610–7,690 | 7,688.62 (+1.58%) | HIT | The election rally held all day, and the index closed just inside the top of our range. |
| 10-year yield close vs 4.952% prior | lower | 4.894% (vs 4.952%) | HIT | The oil plunge and softer services prices pulled yields down. |
| VIX close vs 20.83 prior | lower | 16.61 (vs 20.83) | HIT | Election hedges came off and the VIX fell 20%. |
| Best S&P sector ETF (SPDR XL_) | Health Care (XLV) | Consumer Discretionary (XLY) +4.26%; XLV +3.06% | MISS | Health care rallied but finished sixth; Amazon and Booking put discretionary first. |
| Worst S&P sector ETF (SPDR XL_) | Energy (XLE) | Energy (XLE) -4.74% | HIT | Oil’s 8% drop made energy the clear laggard. |
| IBRX close vs $8.29 | higher | 8.93 vs 8.29 (+7.72%) | HIT | Said the first patients in Europe, in Germany and Austria, have been treated with Anktiva plus BCG, and the stock ran up late in the session ahead of third-quarter results due Thursday. |
| NN close vs $9.85 | higher | 8.76 vs 9.85 (-11.07%) | MISS | Fell to a 52-week low with no fresh company news we could confirm, extending Monday’s 16.5% drop. |
| SPCX close vs $141.31 | lower | 135.92 vs 141.31 (-3.81%) | HIT | Fell with Tesla (TSLA) as newly elected Democrats who have criticized the data-center buildout won control; SpaceX runs AI computing sites in Tennessee and Mississippi. |
| URNM close vs $41.32 | higher | 41.22 vs 41.32 (-0.24%) | MISS | Roughly flat after an early gain faded as power producers sold off; Cameco (CCJ) fell 1.2%. |
| DRAM close vs $47.64 | lower | 45.11 vs 47.64 (-5.31%) | HIT | Fell with memory stocks, including Micron and Sandisk (SNDK), on fears of a slower data-center buildout. |
| GLXY close vs $16.83 | lower | 13.97 vs 16.83 (-16.99%) | HIT | Fell to a 52-week low as data-center operators were hit hard, with Hut 8 down 23% and IREN down 11%; Galaxy’s Helios campus is in Texas, a state where Democrats gained. |
The big calls landed: the index finished inside our range, and yields, the VIX and the worst sector all went our way, along with four of six watchlist names. The misses were health care, which rallied but lost the top spot to discretionary, NextNav and the uranium miners. Running scorecard: 98 hits + 1 partial across 147 graded calls = 98.5/147 (67.0%).
Look ahead — Thursday, Nov 5
S&P futures were at 7,734.50 late this afternoon, and AppLovin’s late jump gives tech a lift into Thursday. Weekly jobless claims come before the open, and Friday’s October jobs report is the next big test. Bull (30%): the rally broadens and chips stabilize, and the S&P closes above 7,740. Base (45%): the index digests a 1.6% gain and holds between 7,640 and 7,740. Bear (25%): the data-center selloff spreads to the AI giants and the S&P closes below 7,640. Wick's pick: Base. Jobs report

What to watch
- Weekly jobless claims at 8:30 AM ET on Nov 5.
- ImmunityBio Q3 results on Nov 5..ics
- Market reaction to AppLovin, Qualcomm and Coherent results on Nov 5.
- October jobs report at 8:30 AM ET on Nov 6..ics
Wick's take: This was a real relief rally, not just a few big names: three stocks rose for every one that fell, and the VIX dropped below 17. The split inside tech matters more for the coming weeks. The market is betting that the companies paying for AI win if the buildout slows, and that the builders lose. We’d lean toward the broad rally and stay careful with data-center, memory and power names until that story settles.
Market data and opinions by Wick. This post is informational only and is not financial advice. Prices may differ slightly between data vendors; predictions are tracked and scored openly.
Add all 2 events to calendar (.ics) Times are ET. Each event has a 1-day reminder. Estimated dates are marked.