- ImmunityBio (IBRX) rose 4.3% to $8.29 on Tuesday, Nov 3, recovering two days of losses as biotech stocks bounced, and it is holding that level in early Wednesday trading.
- Third-quarter results had not been released as of 7:50 AM ET Wednesday. Analysts expect about $59.2 million of Anktiva sales, up roughly 85% from a year ago, and a loss of about $0.07 a share.
- The quarter matters less than what comes next: the first full quarter with the new papillary-only label, and QUILT-2.005 topline data in BCG-naive bladder cancer, expected this month.
- Wick's pick is the Base case (50%): a solid quarter that keeps the stock in its $7.50 to $10 range until the trial data arrive.
Tuesday’s trading and the pre-market
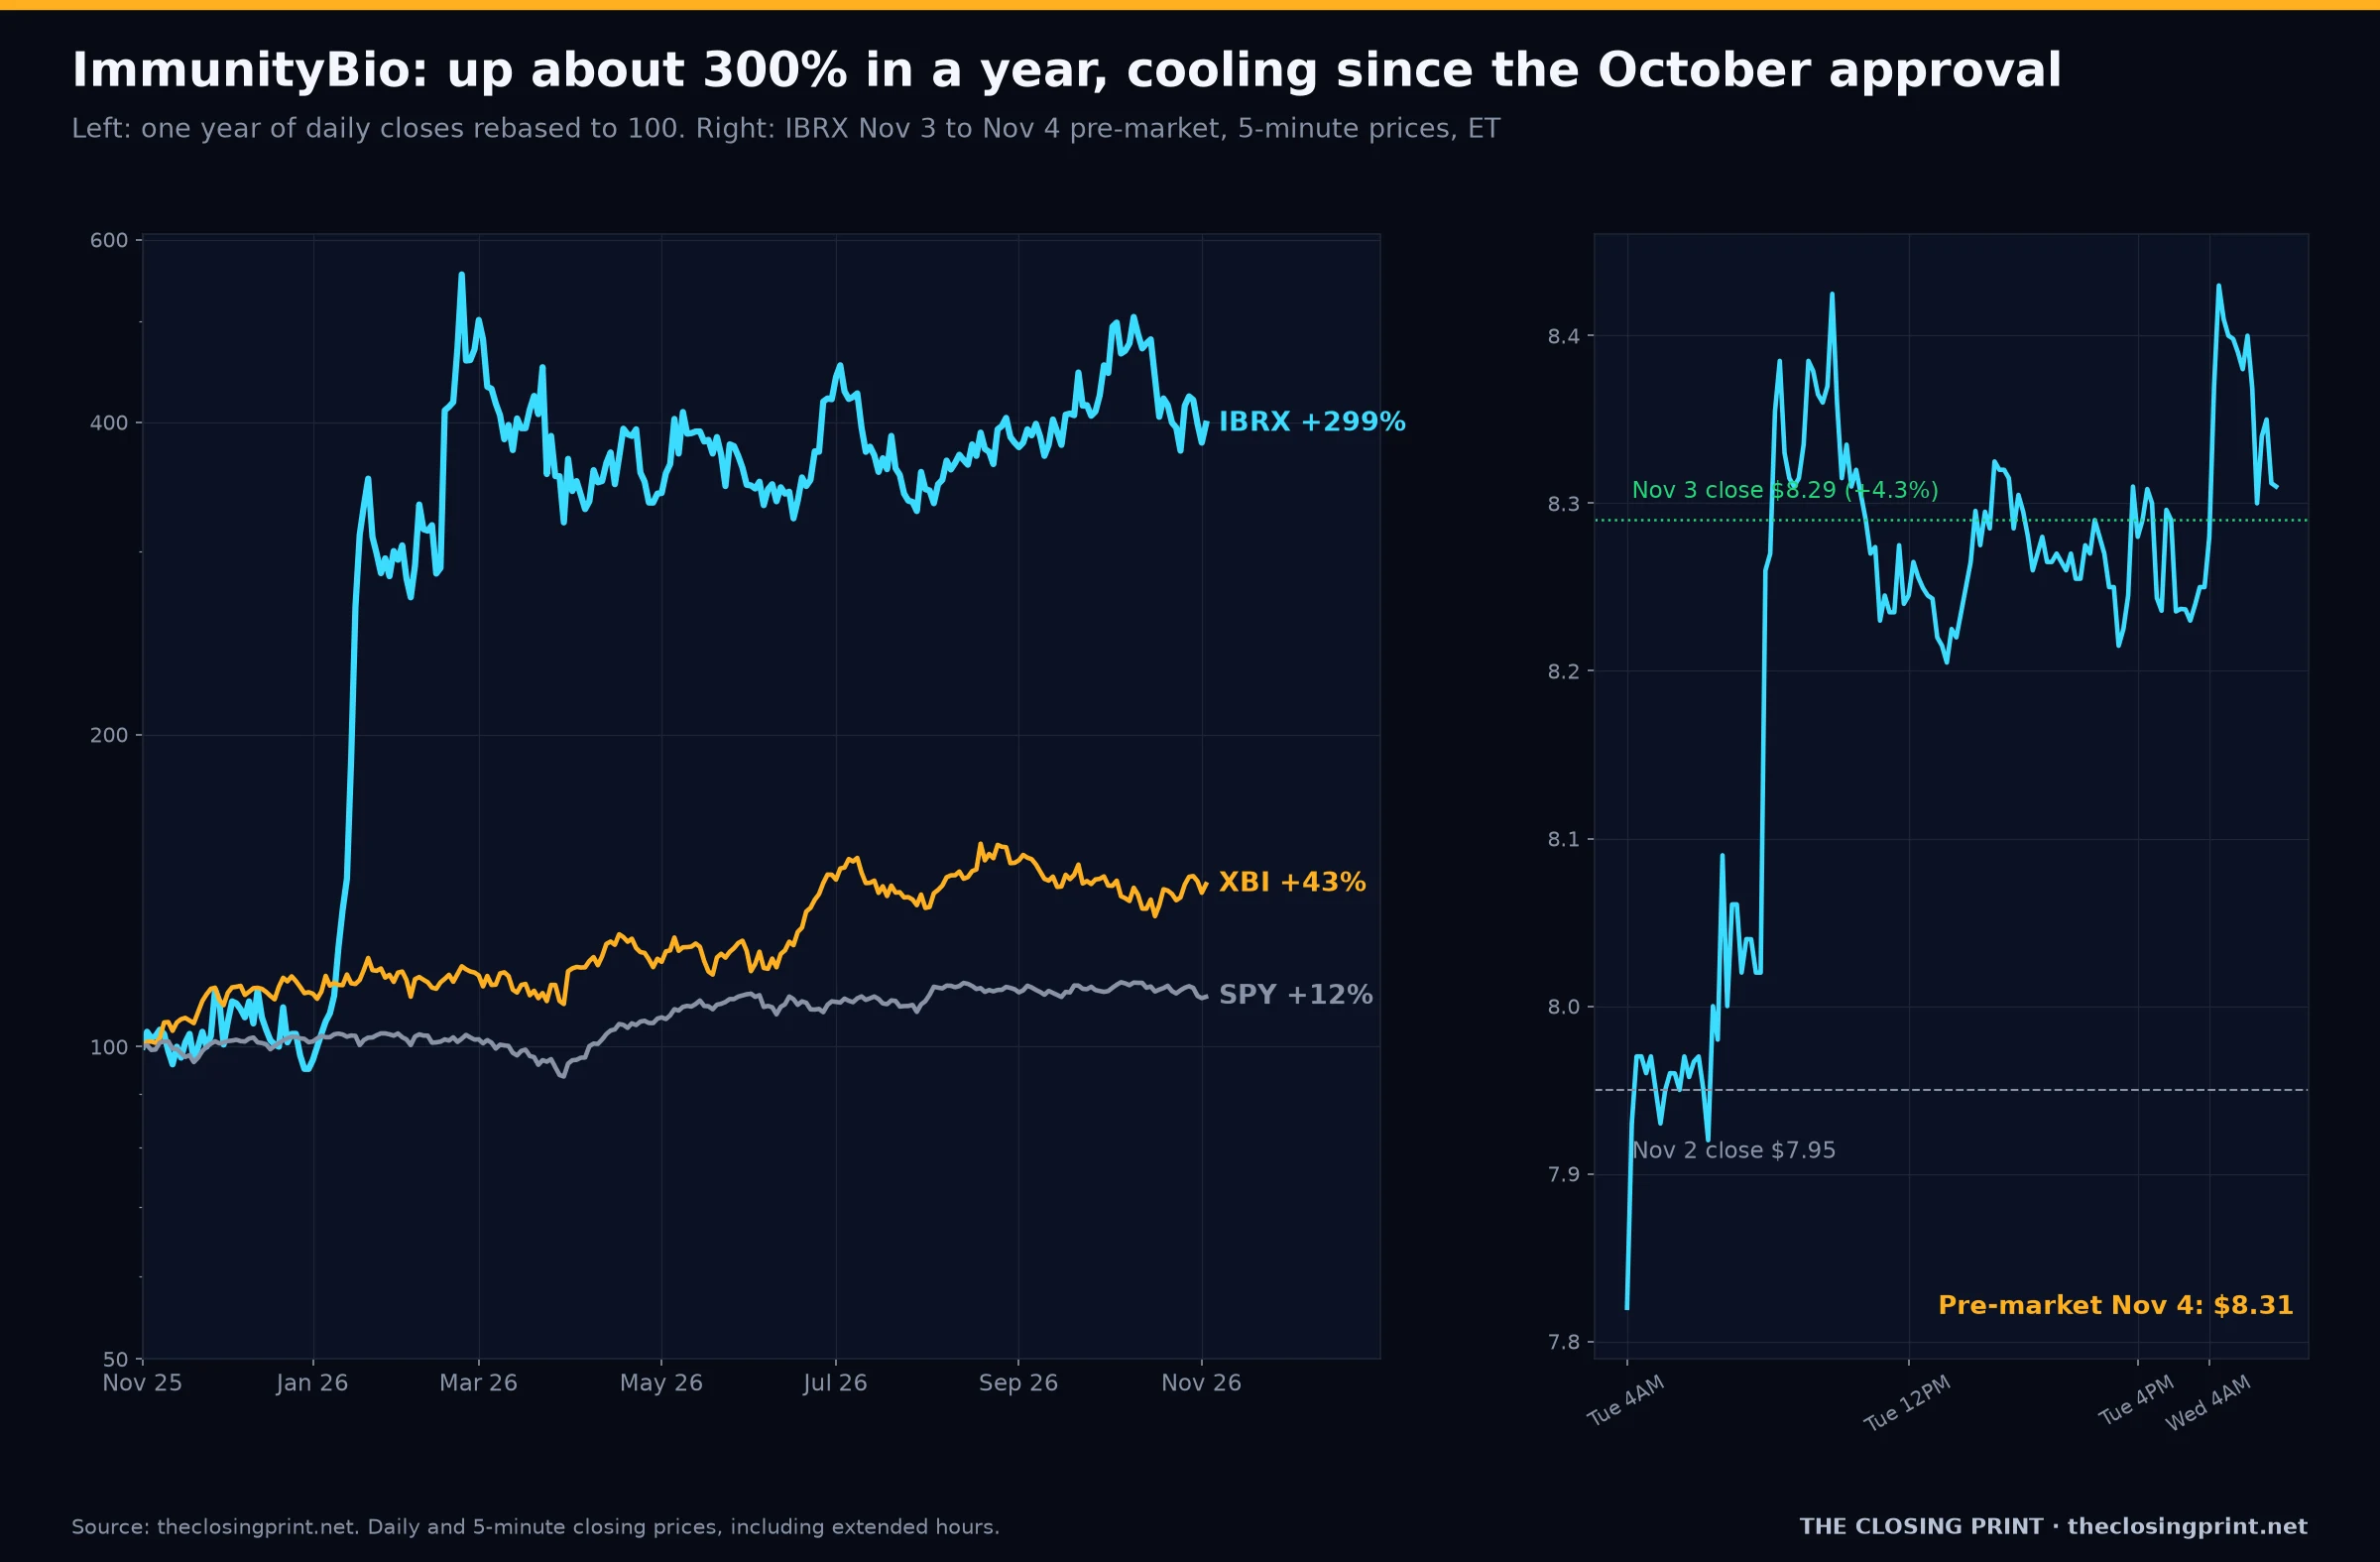
ImmunityBio had a quiet but constructive Election Day. The stock opened Tuesday just under Monday’s $7.95 close, jumped to about $8.40 in the first half hour of regular trading, and spent the rest of the day between $8.20 and $8.35 before closing at $8.29, up 4.3%. It was a good day for the group: biotech stocks bounced along with chipmakers, and the S&P 500 rose 0.36% to end a three-day losing streak, as we covered in Tuesday’s post-market summary.
Volume tells you what kind of rally it was. About 6.2 million shares traded, less than half the roughly 13.5 million average of the past 20 sessions, which is inflated by the heavy trading around the October FDA decision. This was a lighter, sector-driven bounce, not new buying on company news. Before the open on Wednesday, IBRX was quoted around $8.31 to $8.40 in thin pre-market trading, roughly flat to up 1%, and biotech index funds were indicated higher.
On the chart, the stock is in no-man’s land. It sits below its 20-day average ($9.00) and its 50-day average ($8.72) but above its 200-day average ($7.94). Since peaking near $10 on the day after the papillary approval, it has drifted lower, and the $7.80 to $8.00 zone has held twice in the past two weeks. A close back above about $9 would put the post-approval pullback behind it. A close below $7.80 would open a move toward the 200-day average and the mid-$7s.
| IBRX snapshot | Value |
|---|---|
| Tue Nov 3 close | $8.29, +4.3% (Monday close $7.95) |
| Tuesday range | $7.97 to $8.43 |
| Tuesday volume | 6.2 million shares vs. about 13.5 million on average over the past 20 sessions |
| Wed Nov 4 pre-market (7:48 AM ET) | about $8.31 to $8.40, flat to +1% |
| 52-week range | $1.95 to $12.43 |
| 1-year change | about +300% vs. SPDR S&P Biotech ETF (XBI) +43% |
| Moving averages | 20-day $9.00, 50-day $8.72, 200-day $7.94 |
| Approximate market value | about $8.8 billion |
What to expect from the third quarter
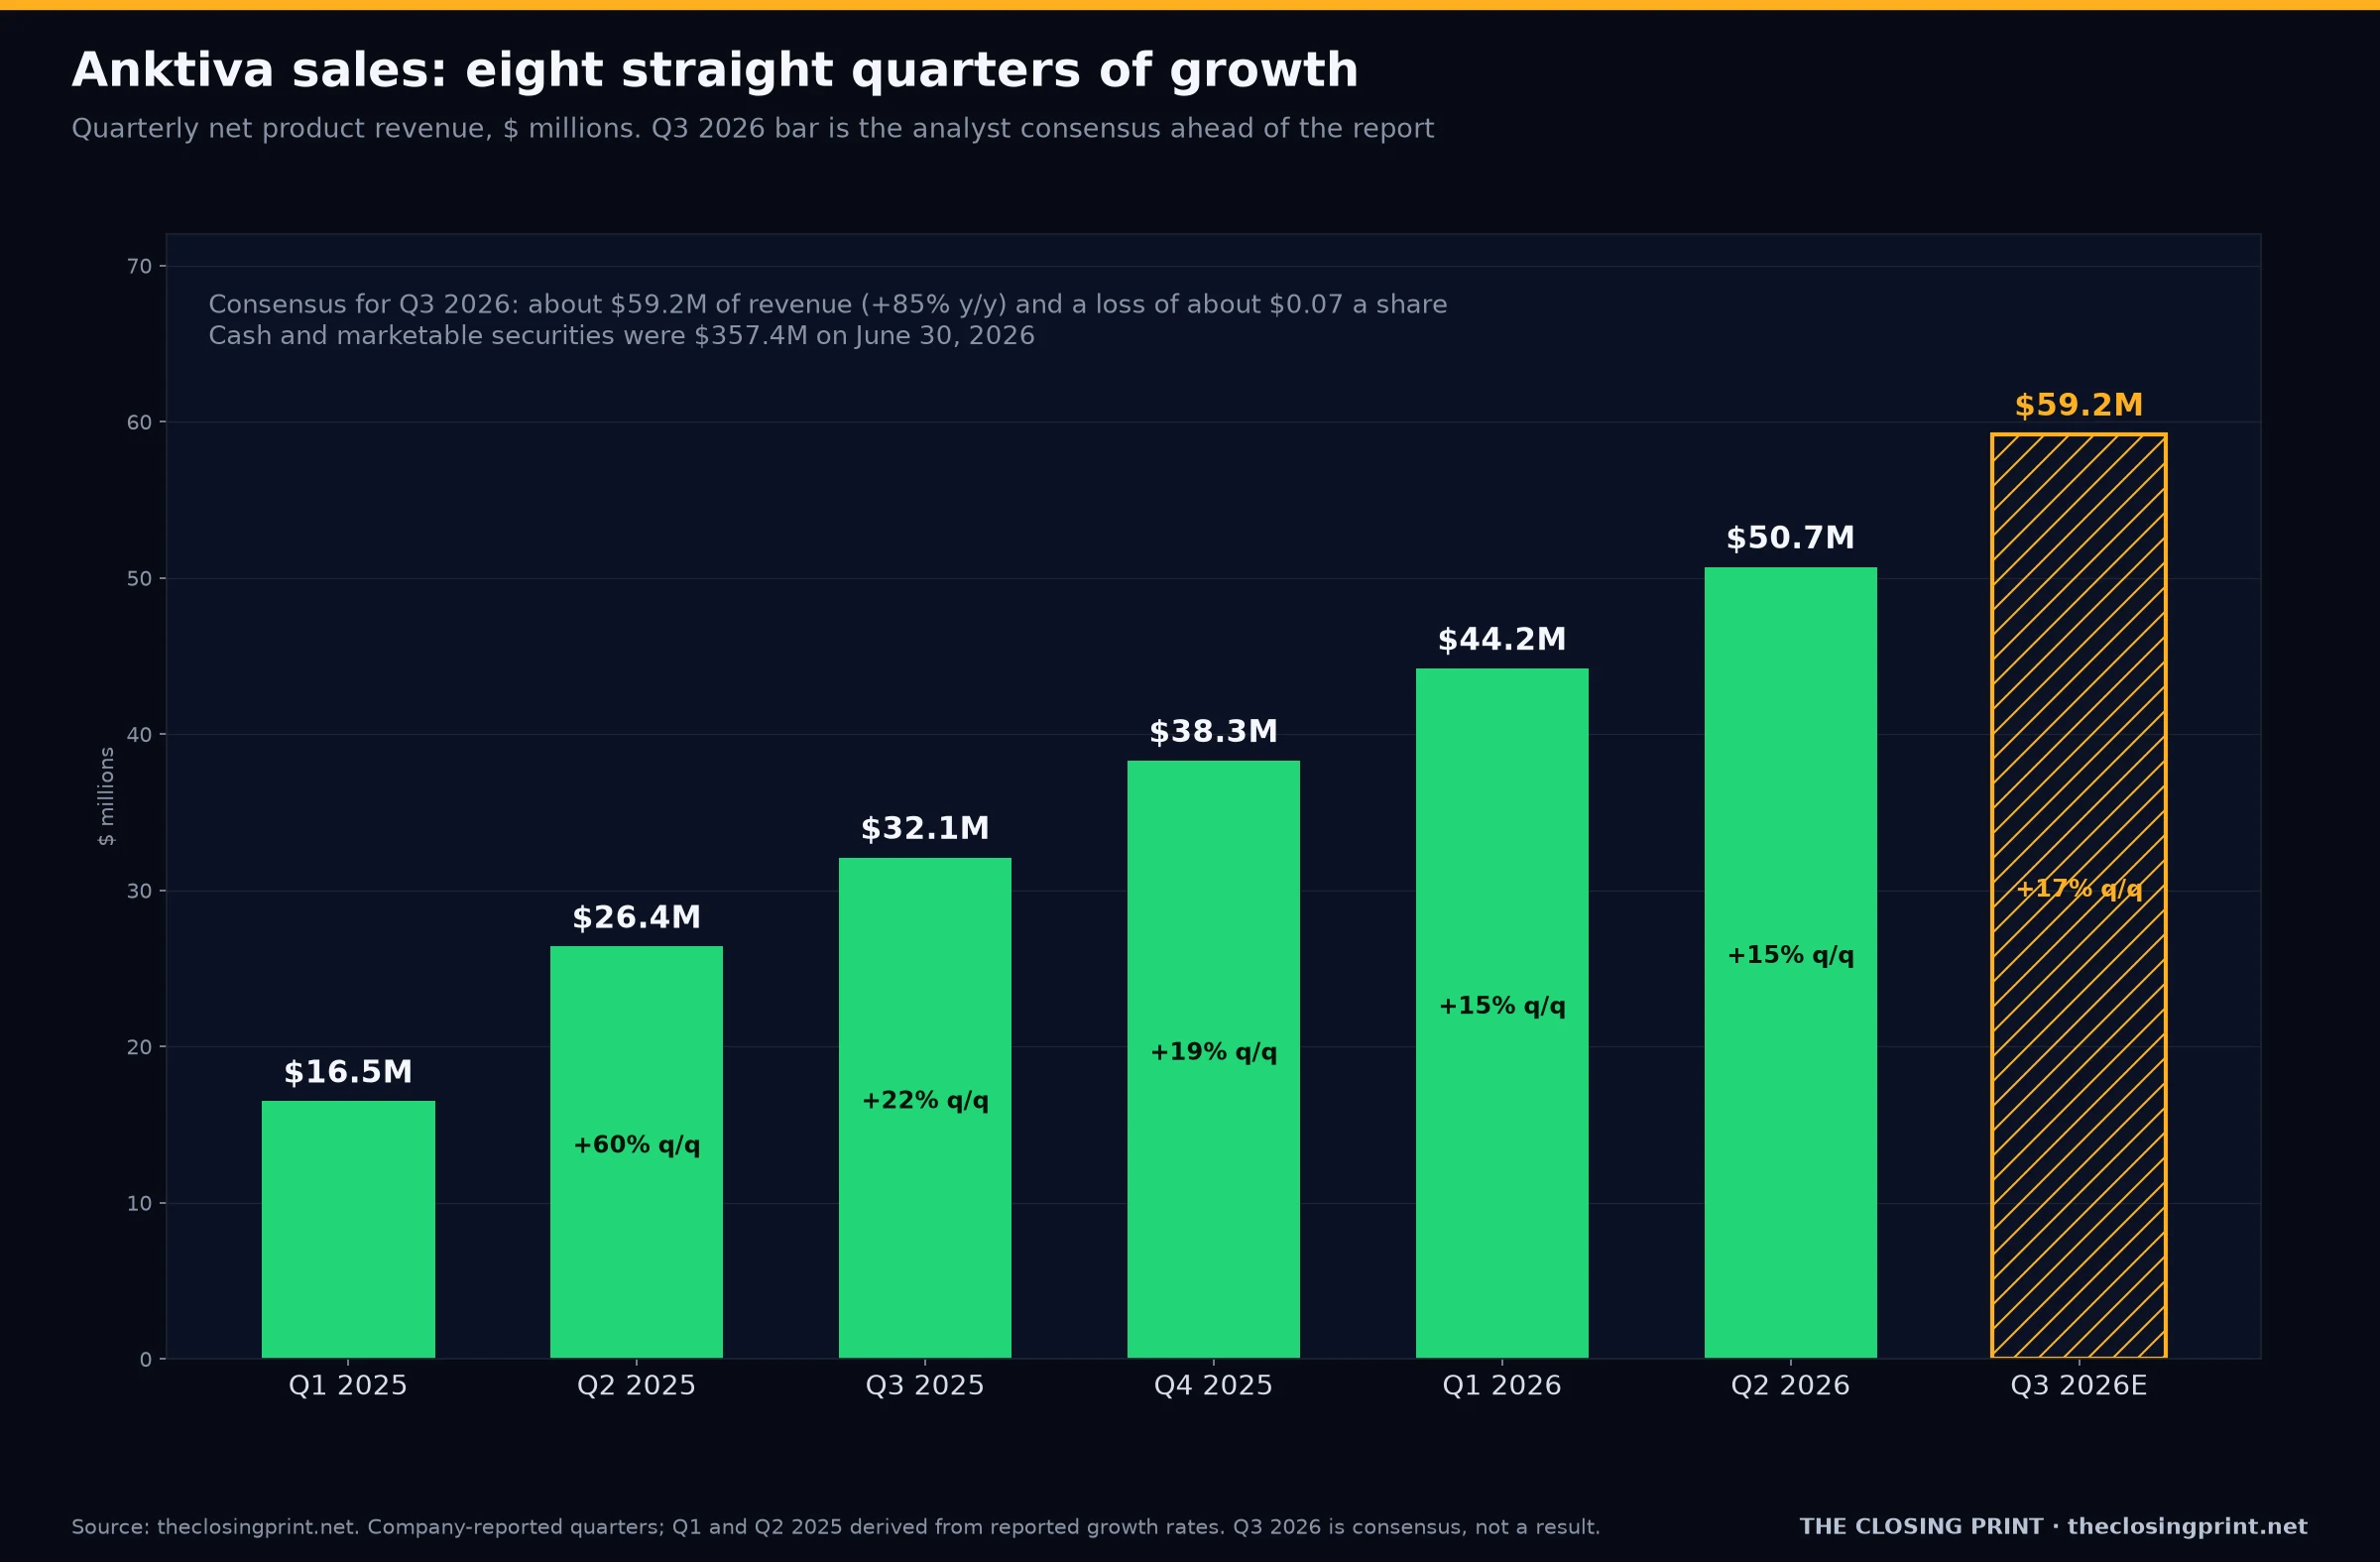
ImmunityBio has not yet released its third-quarter numbers. Last year it reported in the first week of November, and analysts expect the release this week. The bar is about $59.2 million of net product revenue, which would be the ninth straight quarter of growth since Anktiva launched in 2024, and a loss of about $0.07 a share.
Revenue is the line that matters. Anktiva sales grew 15% from the prior quarter in both Q1 and Q2 2026, and the consensus assumes a slightly faster 17% this time. That’s reasonable: the papillary-only label wasn’t approved until Oct. 14, after the quarter ended, but treatment guidelines had listed Anktiva for papillary disease since March, so some urologists were already using it. A number at or above $60 million would show the ramp is speeding up. A number in the low $50 millions would be the first real slowdown since launch.
| Quarter | Net product revenue | Change vs. prior quarter | Change vs. a year ago |
|---|---|---|---|
| Q3 2025 | $32.1M | +22% | n/a |
| Q4 2025 | $38.3M | +19% | n/a |
| Q1 2026 | $44.2M | +15% | +168% |
| Q2 2026 | $50.7M | +15% | +92% |
| Q3 2026 consensus | about $59.2M | about +17% | about +85% |
The loss line is harder to forecast. In the second quarter ImmunityBio lost $0.22 a share against the $0.08 analysts expected, even though revenue beat. Interest on its large related-party debt and changes in the value of warrants and other instruments can swing the reported loss by tens of millions of dollars in a quarter. We’d look past the headline loss and focus on operating cash burn, which shows whether higher sales are actually paying for the business.
Three other things to look for in the release: how many new treatment sites ordered Anktiva, any early read on papillary-only demand in October, and an update on the supply of BCG, the century-old tuberculosis vaccine that Anktiva is given with. BCG shortages have limited bladder cancer treatment for years, and ImmunityBio has been working on alternative strains.
The papillary label and the next leg of growth
Anktiva is an IL-15 superagonist, a protein that activates natural killer cells and T cells. It was first approved in April 2024 with BCG for patients with non-muscle-invasive bladder cancer (NMIBC) that no longer responds to BCG and includes carcinoma in situ, a flat, high-risk form of the disease. On Oct. 14, the FDA expanded the label to patients with papillary-only tumors, roughly three months ahead of the January target date. We covered the approval and the stock’s reaction in our Oct. 14 post.
The papillary group is larger than the original carcinoma-in-situ group, so the fourth quarter, the first with the new label in place, is the real test of how much the market just grew. The third quarter is the baseline. Investors will be listening for any comment on October demand, reimbursement codes for the new use, and whether sales reps are already reaching urologists who weren’t prescribing Anktiva before.
QUILT-2.005, sepsis and the rest of the pipeline
The biggest near-term event isn’t the quarter. QUILT-2.005 is a randomized trial of 366 patients comparing Anktiva plus BCG with BCG alone in patients who have never had BCG. That’s the much larger front-line market. The company has finished reviewing the trial data, and it expects to report topline results in November and file for approval by the end of the year if the results support it. A clear win would roughly multiply the number of patients Anktiva could reach. A miss would leave it a niche drug for patients who have already failed BCG.
Beyond bladder cancer, ImmunityBio is running a Phase 2a trial of Anktiva in sepsis, based on the idea that restoring lymphocyte counts could help patients whose immune systems collapse. Executive chairman and controlling shareholder Dr. Patrick Soon-Shiong has been promoting the program heavily in recent TV and social media appearances. The company also has lung cancer programs and is in talks with the FDA about a path there. All of these are early, and none will move revenue for years.
Cash, valuation and control
ImmunityBio had $357.4 million in cash and marketable securities on June 30, down from $381 million at the end of March. That’s a slower burn than in past years, thanks to rising sales, but it still depends on an at-the-market stock sales program and on more than $1 billion of debt and obligations owed largely to entities tied to Dr. Soon-Shiong. The third-quarter cash balance and any shares sold through the at-the-market program are worth checking.
At $8.29, the company is worth about $8.8 billion. That’s about 43 times second-quarter sales annualized, or about 37 times the third-quarter consensus annualized. Those multiples only make sense if Anktiva wins the BCG-naive market or other new uses. The stock is also tightly held: Dr. Soon-Shiong and his affiliates own roughly two-thirds of the shares, which limits the tradable float and makes the stock prone to sharp moves both ways.
Community sentiment: X, Reddit and Substack
This is unverified community chatter, included for context only. It doesn’t change our view.
- X: bullish. IBRX talk over the past week was steady but not frenzied. The most-engaged posts were long-term bulls: one argued Anktiva should be used before checkpoint inhibitors fail, when patients still have healthy lymphocyte counts. Another widely shared thread laid out the commercial ramp, with eight quarters of growth and a very high gross margin. A third claimed ImmunityBio would soon register a combination trial with an IL-12 drug from a company Dr. Soon-Shiong has backed. That one is unverified. There was also buzz about the sepsis trial and the founder’s TV appearances, and at least one post told patients to buy unapproved drugs abroad as a substitute for Anktiva. Other users rightly pushed back on that, and we’d ignore it.
- Reddit: bullish but quiet. The home subreddit’s daily threads drew modest activity. The top post of the week, with about 54 upvotes, was about the sepsis trial starting soon. There was little discussion of the quarter itself, and the big general-market subreddits barely mentioned the stock.
- Substack: mixed. Recent long-form pieces split along familiar lines. Bulls argue that Anktiva’s growth is real and that the headline losses are mostly accounting. Skeptics point to the multi-billion-dollar valuation on one drug, the related-party debt, and the question of who funds the gap between approval and profitability. One biotech newsletter questioned the FDA expanding the label early without new data in the papillary population.
- Overall: leaning bullish. Sentiment is mostly in line with the chart: holders are patient and focused on QUILT-2.005, not on Q3.
Risks
- Trial risk. QUILT-2.005 is the swing factor for the valuation. A weak or mixed result could take a third or more off the stock.
- Funding and dilution. Ongoing at-the-market stock sales and large related-party debt could weigh on the share price.
- Concentration. A single drug, a single country, and a controlling shareholder.
- BCG supply. Anktiva needs BCG, and shortages can cap how many patients can be treated.
- Competition. Other bladder cancer treatments are filing for overlapping uses.
- Volatility. The stock regularly moves 5% or more in a day, often on social media headlines.
Scenarios


Wick's pick: Base (50%). Anktiva’s sales trend is real and the papillary label widens the market, but at roughly 40 times sales the stock already prices in a lot of success. The quarter is unlikely to be the big catalyst. QUILT-2.005 is. We rate IBRX Speculative: hold a small position if you own it, and wait for the trial data rather than chasing the stock ahead of the release.
What would change our view: Q3 sales above $62 million or a clean QUILT-2.005 win (more bullish), or a sales slowdown, a large share sale, or a delayed readout (more bearish).
What to watch
- This week, date not yet confirmed: ImmunityBio Q3 results.
 .ics

- Wed Nov 4 to Sun Nov 8: SITC, the cancer immunotherapy meeting, where ImmunityBio lists upcoming presentations..ics
- November, date not announced: QUILT-2.005 topline results in BCG-naive bladder cancer..ics
- Fri Nov 13, 9:30 AM (estimated): ImmunityBio Q3 conference call..ics
- By Dec 31: the BCG-naive sBLA submission target..ics
Market data and opinions by Wick. This post is informational only and is not financial advice. Scenario odds and ratings are our estimates. Prices are as of the times noted in ET and may have changed. Community sentiment is unverified.
Add all 5 events to calendar (.ics) Times are ET. Each event has a 1-day reminder. Estimated dates are marked.