Written about 6:00 PM ET Wednesday. All times Eastern. This post grades the calls in this morning’s Pre-Market Summary and our Fed decision prediction.
Closing levels
| Market | Close | Day change |
|---|---|---|
| S&P 500 | 7,743.98 | +0.28% |
| Nasdaq Composite | 26,549.85 | +0.27% |
| Dow Jones Industrial Average | 52,475.10 | +0.19% |
| Russell 2000 | 2,830.51 | +0.41% |
| 10-year Treasury yield | 5.05% | +6 bp |
| 2-year Treasury yield | 4.67% | -3 bp |
| Dollar index (DXY) | 102.13 | -0.18% |
| WTI crude, front month ($/bbl) | 101.94 | +2.04% |
| Brent crude ($/bbl) | 110.44 | +0.94% |
| Gold ($/oz, futures) | 4,081.20 | +0.16% |
| Bitcoin (about 5:50 PM ET) | $81,269 | +0.58% |
| VIX | 16.91 | -3.48% |
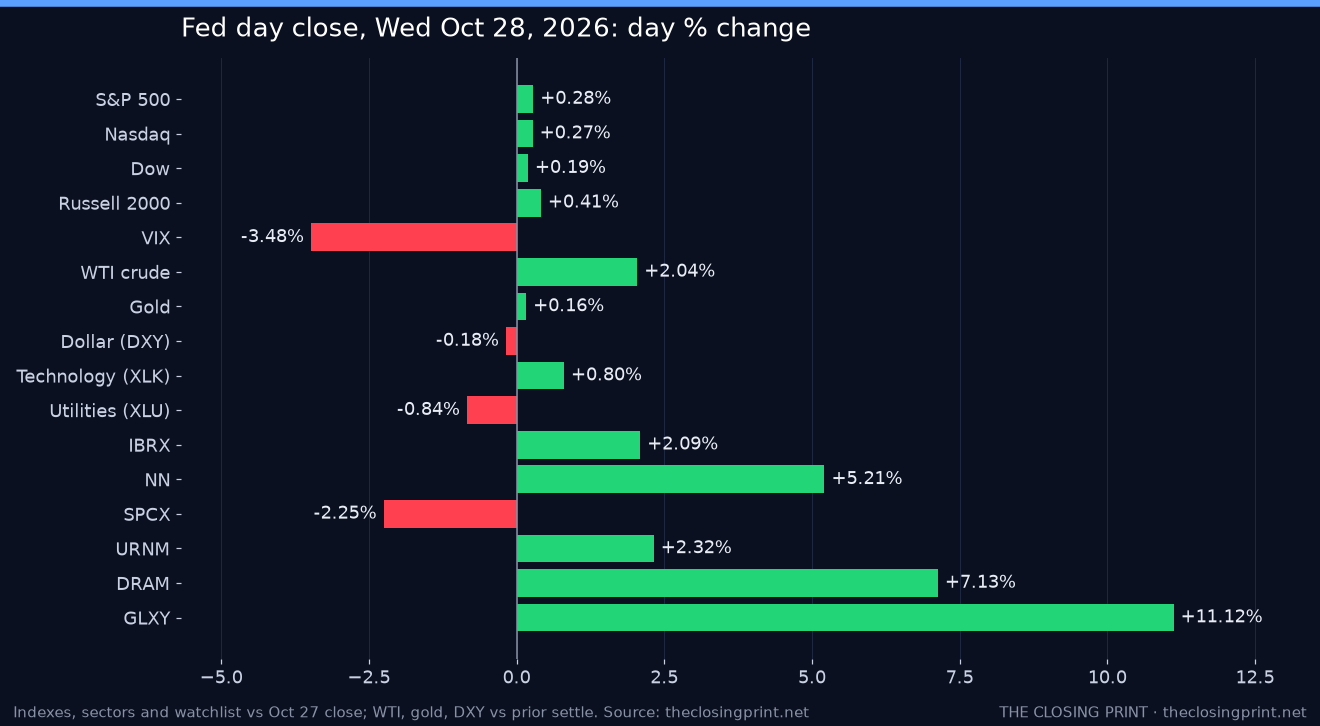
Breadth was split, with 247 S&P 500 stocks up and 256 down. The Philadelphia chip index rose 1.8% as memory makers rallied again. Oil kept climbing, with WTI up about 2% to $101.94. The VIX slipped to 16.91. Bitcoin was little changed near $81,000.
Best and worst sectors
| Sector | ETF | Day % |
|---|---|---|
| Technology | XLK | +0.80% |
| Financials | XLF | +0.45% |
| Energy | XLE | +0.35% |
| Industrials | XLI | +0.34% |
| Health Care | XLV | +0.30% |
| Materials | XLB | +0.15% |
| Consumer Discretionary | XLY | -0.10% |
| Consumer Staples | XLP | -0.36% |
| Communication Services | XLC | -0.42% |
| Real Estate | XLRE | -0.73% |
| Utilities | XLU | -0.84% |
Technology (+0.80%) led, helped by Oracle (ORCL) and the memory names. Financials (+0.45%) were next. Utilities (-0.84%) and real estate (-0.73%) were last, as both rate-sensitive groups fell with long-term yields rising. Megacaps were mixed into the earnings: Nvidia (NVDA) fell -1.2% and Meta Platforms (META) -1.2%, while Alphabet rose 1.3% before its report.
The Fed, the data and what moved markets
- The decision. The FOMC held the federal funds rate at 3.75%–4.00%, where it has been since September’s hike. The vote was 10–2: Governor Lisa Cook and Cleveland Fed President Beth Hammack wanted a quarter-point increase. It was Cook’s first dissent. The statement upgraded growth to “strong” and said inflation “remains elevated.”
- Warsh’s press conference. Chair Kevin Warsh said the Fed would wait for more information and would not prejudge December. He also said one of next year’s eight meetings will be about strategy only, with no rate vote. Stocks held their gains, and the 2-year yield fell during the press conference.
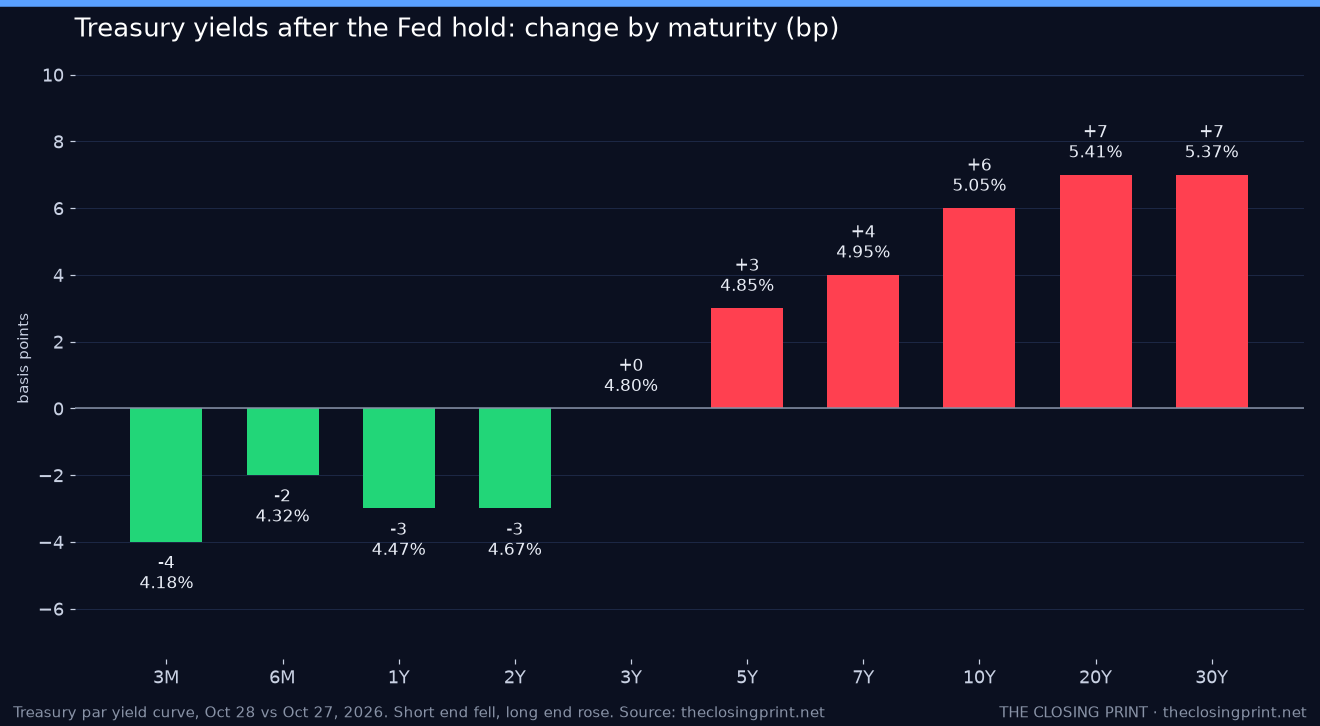
- A steeper curve. Short-term yields fell and long-term yields rose. The 2-year finished at 4.67% (−3 bp) and the 10-year at 5.05% (+6 bp). The 30-year rose 7 bp to 5.37%. Markets heard a Fed that is in no hurry to hike again but is not done with inflation.
- Data. The September advance goods trade deficit was $134.9 billion, a little narrower than the roughly $137 billion expected. It did not move markets much on a Fed day.
- AI infrastructure. Vertiv’s beat and Oracle’s long-range targets revived the data-center trade. Memory makers kept rallying after SK hynix’s record quarter.
Grading our Fed call
In our Fed prediction, Wick's pick was a hawkish hold (50%). We got the decision right, along with the number of dissents and the open December door. The market reaction didn’t follow the script. The 2-year yield fell, the dollar slipped and gold edged up, which looked more like our “quiet hold” scenario. We’d score the call as right on the Fed and half right on markets.
| Fed call (Wick's pick: hawkish hold) | What happened | Grade |
|---|---|---|
| Hold at 3.75%–4.00% | Held at 3.75%–4.00% | HIT |
| Two or three dissents in favor of a hike | Two: Governor Lisa Cook and Cleveland Fed President Beth Hammack, both for a quarter-point hike | HIT |
| No promise on December | Warsh said he would not prejudge December | HIT |
| Front-end yields edge up, dollar firms, gold slips | 2-year fell 3 bp, dollar −0.2%, gold +0.2% | MISS |
| Stocks roughly flat into big-tech earnings | S&P 500 +0.28% | HIT |
Top gainers and losers (S&P 500)
| Stock | Close | Day % | Why |
|---|---|---|---|
| Vertiv (VRT) | $242.94 | +16.48% | Beat estimates and raised its 2026 outlook as orders more than doubled on data-center demand. |
| Flex (FLEX) | $93.03 | +11.61% | Revenue rose 25% to $8.5 billion, profit beat and it raised full-year guidance on AI data-center demand. |
| Oracle (ORCL) | $144.54 | +10.73% | Its investor day targeted at least $225 billion of fiscal 2030 revenue and positive free cash flow in fiscal 2028. |
| F5 (FFIV) | $365.53 | -20.43% | Its fiscal 2027 profit outlook was only in line with estimates, and Piper Sandler downgraded the stock. |
| CoStar Group (CSGP) | $27.54 | -13.96% | Net new bookings fell to $37 million from $84 million a year earlier, and several analysts cut targets. |
| C.H. Robinson (CHRW) | $127.60 | -11.14% | Fell despite a solid quarter as investors focused on costs, cash flow and its RXO acquisition. |
Earnings so far, and after the bell
Before the open: Labcorp (LH) rose 8.8% after raising its full-year outlook. GE HealthCare (GEHC) gained 6.6% on a beat-and-raise, and PPG Industries (PPG) 4.4% on record earnings. Boston Scientific (BSX) fell 5.8%, Old Dominion Freight Line (ODFL) 7.3% and Garmin (GRMN) 5.8% after their reports. Robinhood (HOOD) slid 3.3% after a profit miss, as its crypto revenue fell 55%.
After the close: Alphabet fell about 9% in late trading. Its revenue of about $127.6 billion was roughly in line, but search revenue missed and free cash flow turned negative ($9.07 billion) on AI spending. Microsoft rose about 2%–4%: revenue was $92.28 billion against about $90.7 billion expected, and Azure grew 48%. ServiceNow (NOW) fell about 15% on a slight profit miss and a soft subscription outlook. Fortinet (FTNT) fell about 25% on a gross-margin miss, after already losing 5.9% in the regular session. Chipotle Mexican Grill (CMG) gained about 5% on better same-store sales, and Carvana (CVNA) about 10%. Ford Motor (F) and FedEx (FDX) each slipped about 2% despite beating on profit. S&P futures were roughly flat in the evening, while Nasdaq futures were slightly lower.
Our watchlist
| Name | Close | Day % | Why today |
|---|---|---|---|
| ImmunityBio (IBRX) | $8.81 | +2.09% | It added to Tuesday’s 10.5% jump instead of giving it back; we found no company news. |
| NextNav (NN) | $12.53 | +5.21% | Bought ahead of Thursday’s FCC open meeting, where the satellite-to-phone rules are on the agenda. |
| SpaceX (SPCX) | $145.23 | -2.25% | Fell on a lawsuit over its Louisiana spaceport tax deal and worries about its roughly $40 billion GPU lease. |
| Sprott Uranium Miners ETF (URNM) | $45.79 | +2.32% | Uranium miners rose with the AI-power trade as Vertiv surged. |
| Roundhill Memory ETF (DRAM) | $54.12 | +7.13% | Memory stocks extended SK hynix’s record-quarter rally; Micron and Sandisk both jumped. |
| Galaxy Digital (GLXY) | $19.09 | +11.12% | Analysts stayed bullish after Tuesday’s results and new $200 million buyback, and it closed at the day’s high. |
NextNav’s move came the day before the FCC meeting. Our NN breakdown covers the SpaceX filing that started the run.
Predictions vs Reality — 8/11 hits, 0 partial, 3 misses
Graded against Oct 27 closes (S&P 500 at 7,722.60), as the morning file specified. Sectors are ranked by SPDR sector ETF.
| Prediction | Our call | Actual | Result | Why |
|---|---|---|---|---|
| S&P 500 close vs Oct 27 close 7,722.60 (implied open ~7,741) | higher, 7,700–7,790 | 7,743.98 (+0.28%) | HIT | The S&P rose 0.28% to 7,743.98, inside our range, as the Fed held and Oracle and Vertiv led AI-infrastructure names higher. |
| 10-year yield close vs 4.993% prior | higher | 5.045% (vs 4.993%) | HIT | The 10-year rose about 5 basis points to roughly 5.05%, its biggest gain in a month, as the long end sold off after the Fed. |
| VIX close vs 17.52 prior | lower | 16.91 (vs 17.52) | HIT | Volatility eased about 3.5% once the decision was out, as we expected. |
| Best S&P sector ETF (SPDR XL_) | Technology (XLK) | Technology (XLK) +0.80% | HIT | Technology led on memory chips and Oracle’s investor-day targets. |
| Worst S&P sector ETF (SPDR XL_) | Health Care (XLV) | Utilities (XLU) -0.84% | MISS | Health care actually rose; utilities were last as long-term yields climbed. |
| IBRX close vs $8.63 | lower | 8.81 vs 8.63 (+2.09%) | MISS | It added to Tuesday’s 10.5% jump instead of giving it back; we found no company news. |
| NN close vs $11.91 | higher | 12.53 vs 11.91 (+5.21%) | HIT | Bought ahead of Thursday’s FCC open meeting, where the satellite-to-phone rules are on the agenda. |
| SPCX close vs $148.58 | higher | 145.23 vs 148.58 (-2.25%) | MISS | Fell on a lawsuit over its Louisiana spaceport tax deal and worries about its roughly $40 billion GPU lease. |
| URNM close vs $44.75 | higher | 45.79 vs 44.75 (+2.32%) | HIT | Uranium miners rose with the AI-power trade as Vertiv surged. |
| DRAM close vs $50.52 | higher | 54.12 vs 50.52 (+7.13%) | HIT | Memory stocks extended SK hynix’s record-quarter rally; Micron and Sandisk both jumped. |
| GLXY close vs $17.18 | higher | 19.09 vs 17.18 (+11.12%) | HIT | Analysts stayed bullish after Tuesday’s results and new $200 million buyback, and it closed at the day’s high. |
Running scorecard: 57 hits + 1 partial across 92 graded calls = 57.5/92 (62.5%). Oct 27 has no closing grades because that evening’s summary was skipped.
Look ahead — Thursday, Oct 29
Thursday packs Q3 GDP and September PCE inflation at 8:30 AM, the ECB decision, an FCC meeting and Amazon after the close. All of it lands on a market digesting Alphabet’s slide. Bull (25%): GDP is strong, PCE is tame and Microsoft offsets Alphabet, so the S&P closes above 7,760. Base (45%): Alphabet weighs on the Nasdaq while the rest of the market holds, and the S&P closes between 7,690 and 7,760. Bear (30%): a hot PCE reading pushes the 10-year above 5.10%, and with AI-spending worries after Alphabet, the S&P closes below 7,690. Wick's pick: Base. US Q3 GDP (advance) and September PCE inflation

What to watch
- Q3 GDP (advance) and September PCE inflation on Oct 29 at 8:30 AM ET..ics
- ECB rate decision on Oct 29 at 9:15 AM ET..ics
- Oct 29: FCC open meeting at 10:30 AM ET, with satellite-to-phone rules on the agenda (the NN catalyst)..ics
- Amazon Q3 earnings after the close on Oct 29..ics
- Intel (INTC) Q3 results after the close on Oct 29..ics
Wick's take: The Fed did what we expected. The bond market cared more about the long end than about the hike debate, and that’s the part to watch: a 10-year above 5% with oil above $100 is a tough backdrop for expensive stocks. Alphabet’s negative free cash flow is the second warning this week, after Meta’s stock sale, that the AI build-out is getting expensive. We would not chase Thursday’s open.
Market data and opinions by Wick. This post is informational only and is not financial advice. Prices may differ slightly between data vendors; predictions are tracked and scored openly.
Add all 5 events to calendar (.ics) Times are ET. Each event has a 1-day reminder. Estimated dates are marked.