Written about 11:45 AM ET Wednesday, Oct 28, 2026, before the decision. All times Eastern. The FOMC statement comes out at 2:00 PM and Chair Kevin Warsh’s press conference starts at 2:30 PM. Market levels are late-morning quotes against Tuesday’s close.
Where things stand going in
The Fed raised rates by a quarter point on Sept. 16 to 3.75%–4.00%, its first hike since July 2023, on a 12–0 vote. That statement was short and ended with one line: “The Committee will deliver price stability.” In July, the Fed had held at 3.50%–3.75% on a 9–3 vote, with Hammack, Kashkari and Logan dissenting because they wanted to hike then.
The September projections put the median year-end policy rate at 4.1%, which works out to one more quarter-point hike this year. The minutes, released Oct. 7, said many officials saw another hike this year as appropriate. Today’s meeting is the fourth under Warsh. There is no new Summary of Economic Projections or dot plot today. Those come with the Dec 8–9 meeting.
| Market | Late morning | Change vs. Tuesday |
|---|---|---|
| S&P 500 | 7,736.78 | +0.18% |
| Nasdaq Composite | 26,466.68 | -0.04% |
| VIX | 17.23 | -0.29 pts |
| 2-year Treasury yield | 4.77% | +3 bp |
| 10-year Treasury yield | 5.02% | +3 bp |
| 30-year Treasury yield | 5.33% | +2 bp |
| US Dollar Index | 102.34 | +0.02% |
| Gold (Dec futures) | $4,056.70 | -0.44% |
| WTI crude (Dec) | $102.33 | +2.43% |
| Brent crude | $115.50 | +1.42% |
| Bitcoin | $80,602 | -0.02% |
Why the Fed probably waits
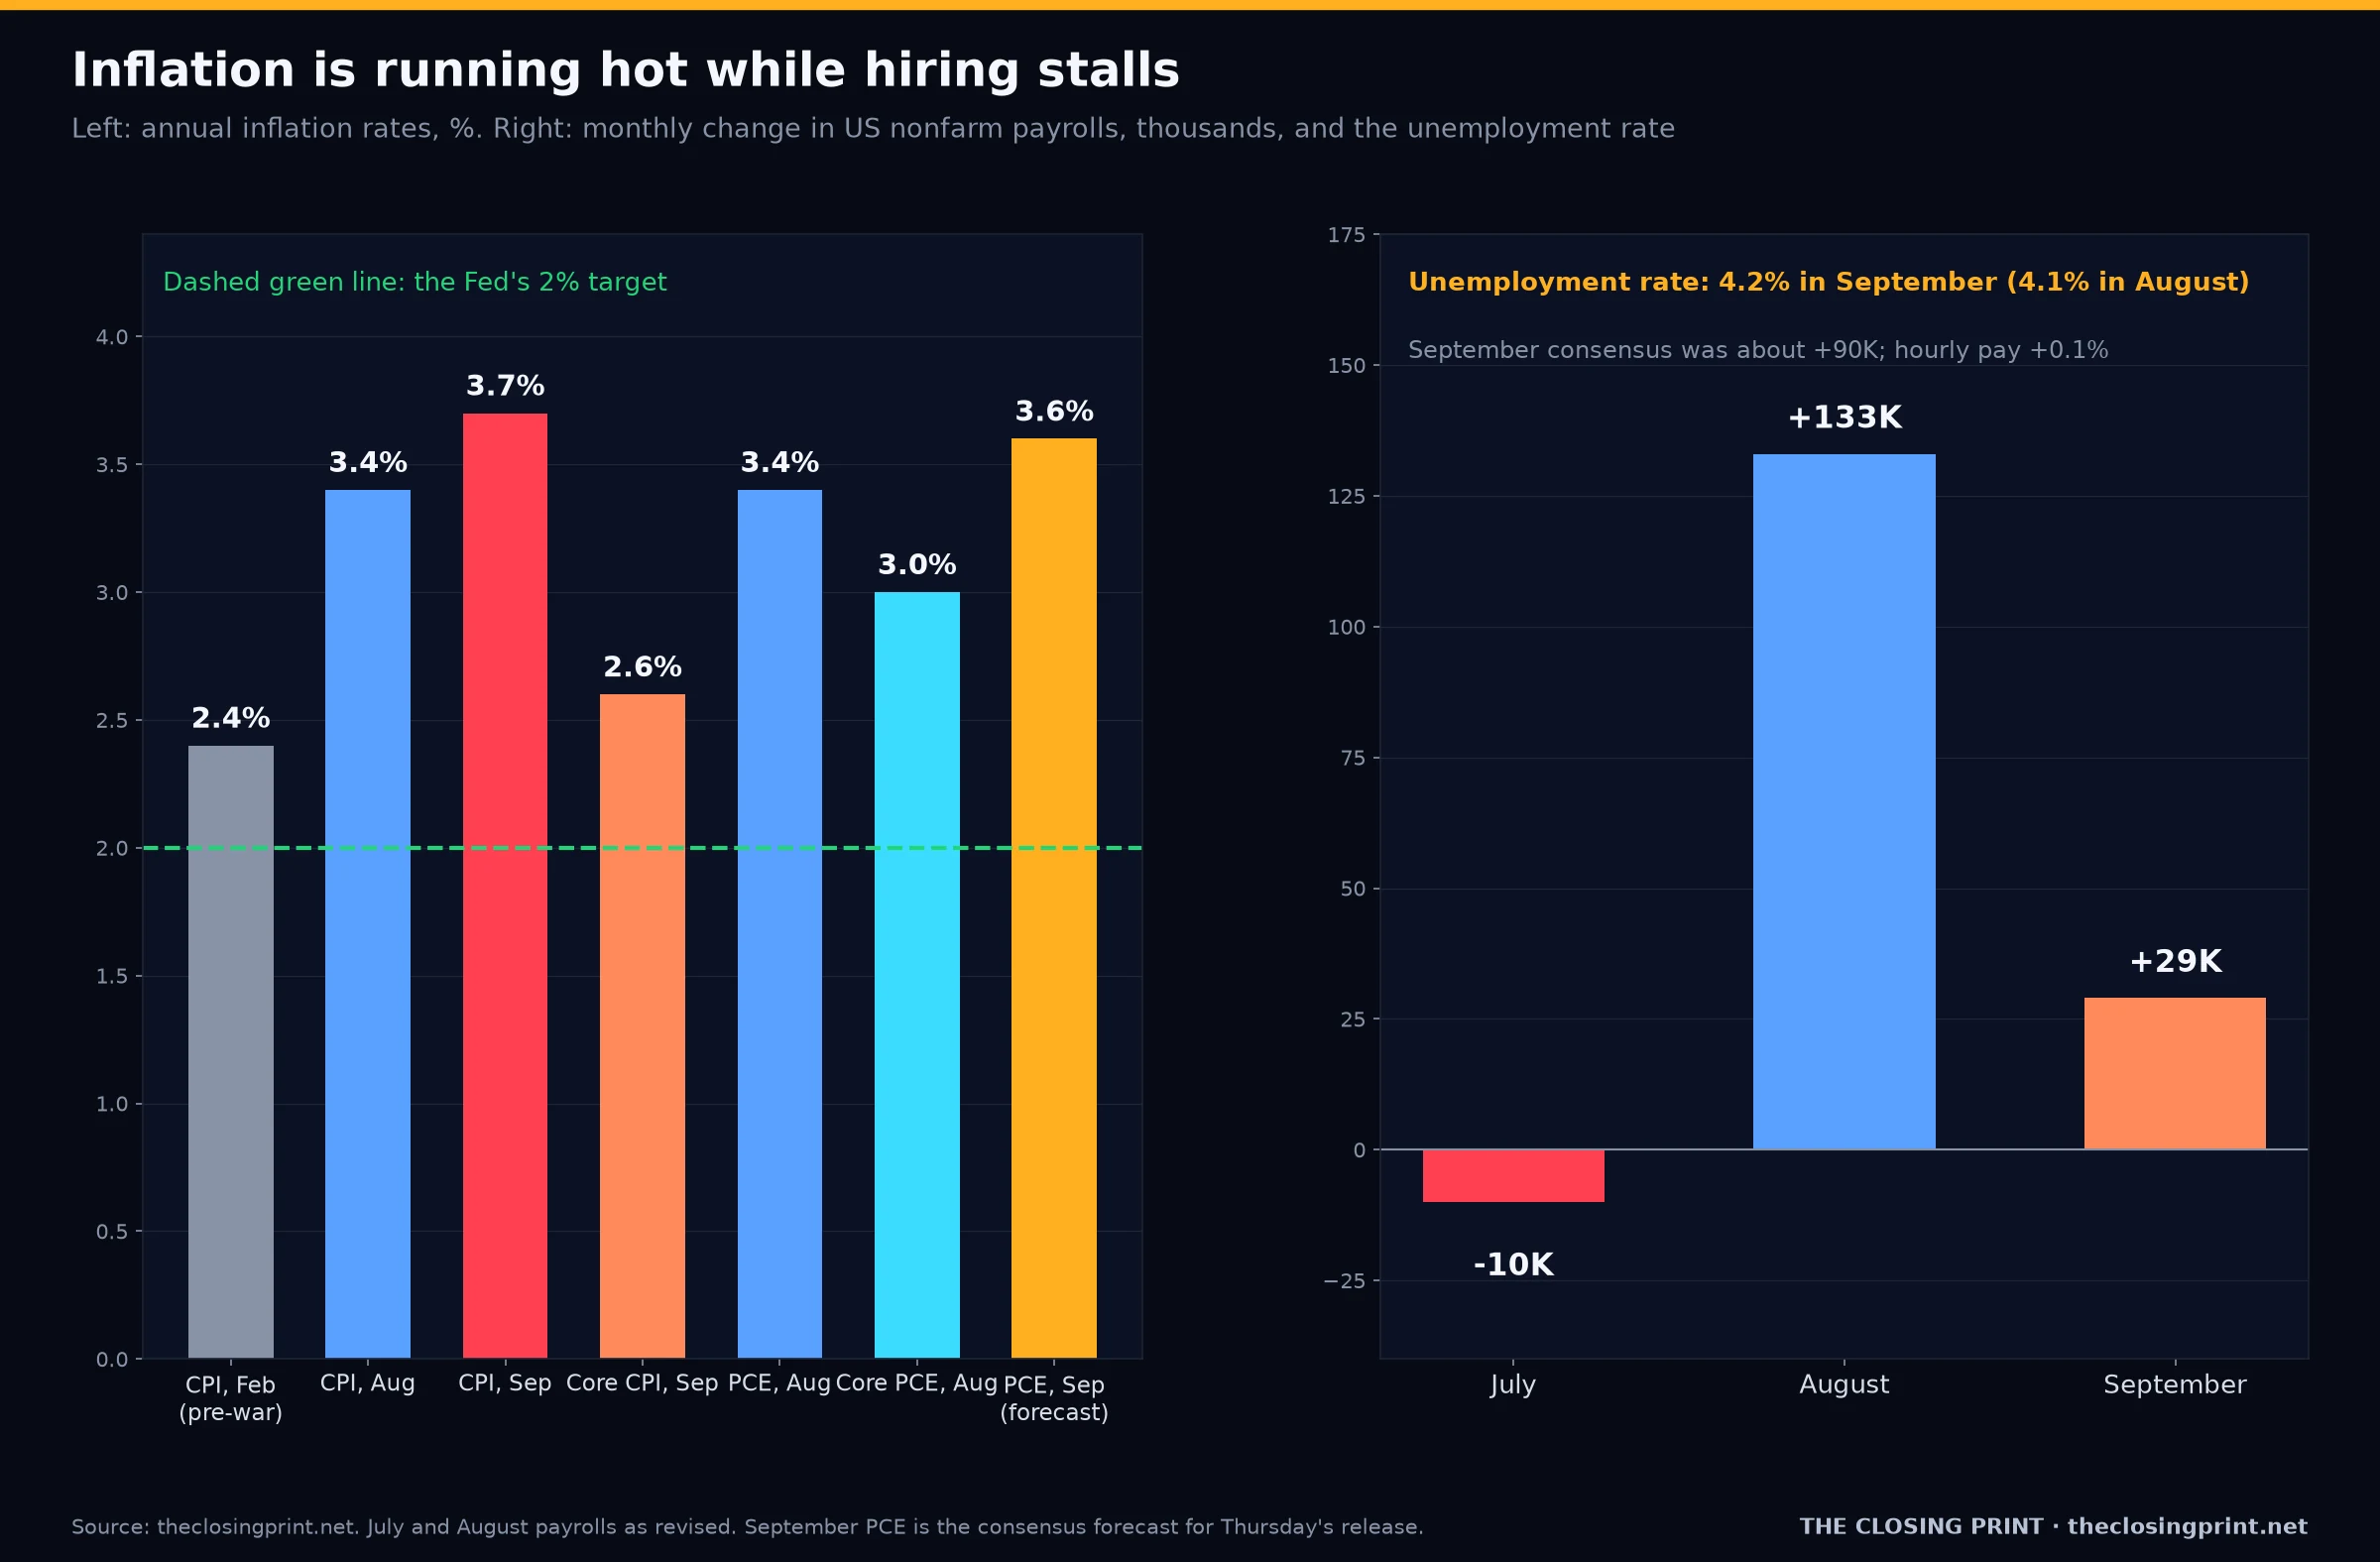
- Inflation is the case for hiking. September CPI rose 3.7% from a year earlier, up from 3.4% in August and 2.4% in February, before the Iran war. Gasoline jumped 9.1% in September and drove more than half of the monthly rise. Core CPI rose 0.3% on the month, to 2.6% for the year from 2.4%. August PCE, the Fed’s preferred measure, was 3.4%, with core PCE at 3.0%. Economists expect Thursday’s September PCE to show about 3.6%.
- Jobs are the case for waiting. Payrolls rose only 29,000 in September against forecasts near 90,000. July was revised to a loss of 10,000 and August to a gain of 133,000. Unemployment ticked up to 4.2% from 4.1%, and average hourly earnings rose just 0.1%.
- Officials have already told markets to expect a pause. Vice Chair Philip Jefferson, Vice Chair for Supervision Michelle Bowman and New York Fed President John Williams have all said they want more data before hiking again. Governor Christopher Waller sees more hikes but is flexible on timing. After those remarks, market odds of an October hike fell from above 70% to under 30%, and they have kept falling since.
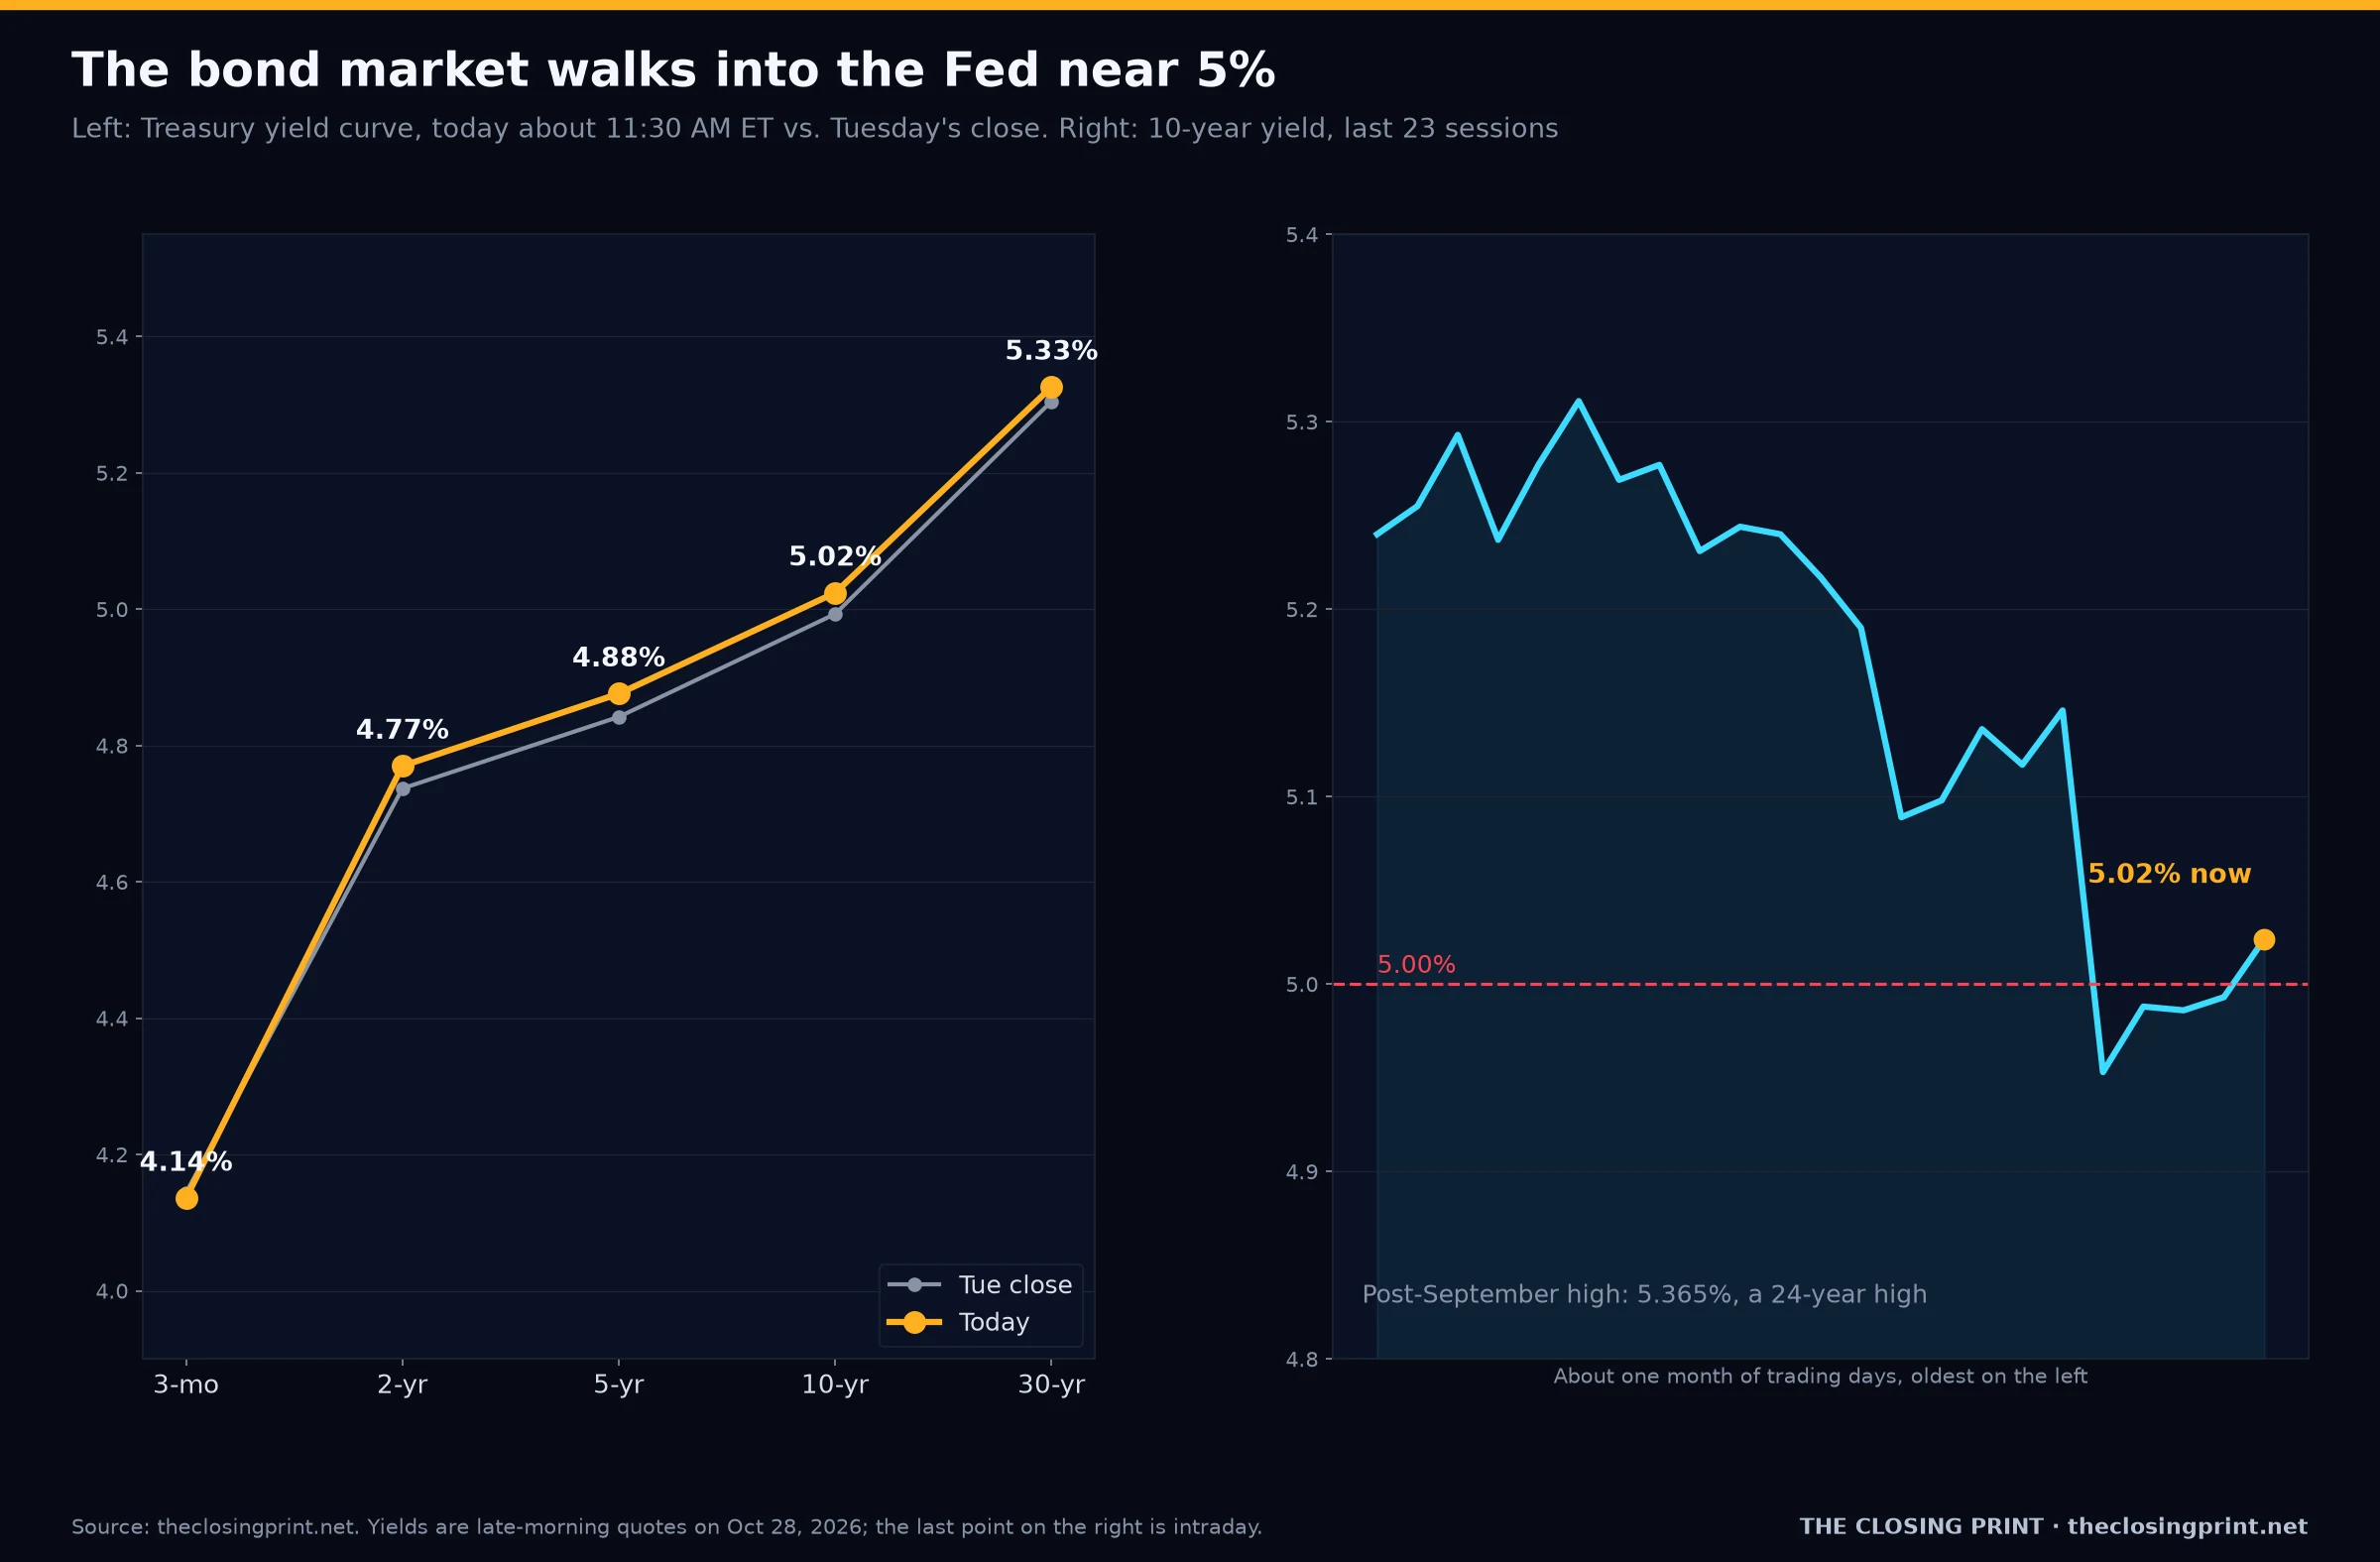
- The bond market has done part of the work. The 10-year yield hit 5.365% after the September hike, a 24-year high, and has been near or above 5% since. The 30-year mortgage rate reached 7.4% earlier this month, a three-year high, before easing to 7.32%.
- The calendar. The midterm elections are next Tuesday, Nov 3. The Fed says politics doesn’t drive policy, but a hike six days before the vote, after President Trump criticized the September move, would draw attention to the Fed itself. Holding now and moving in December avoids that.
What markets are pricing
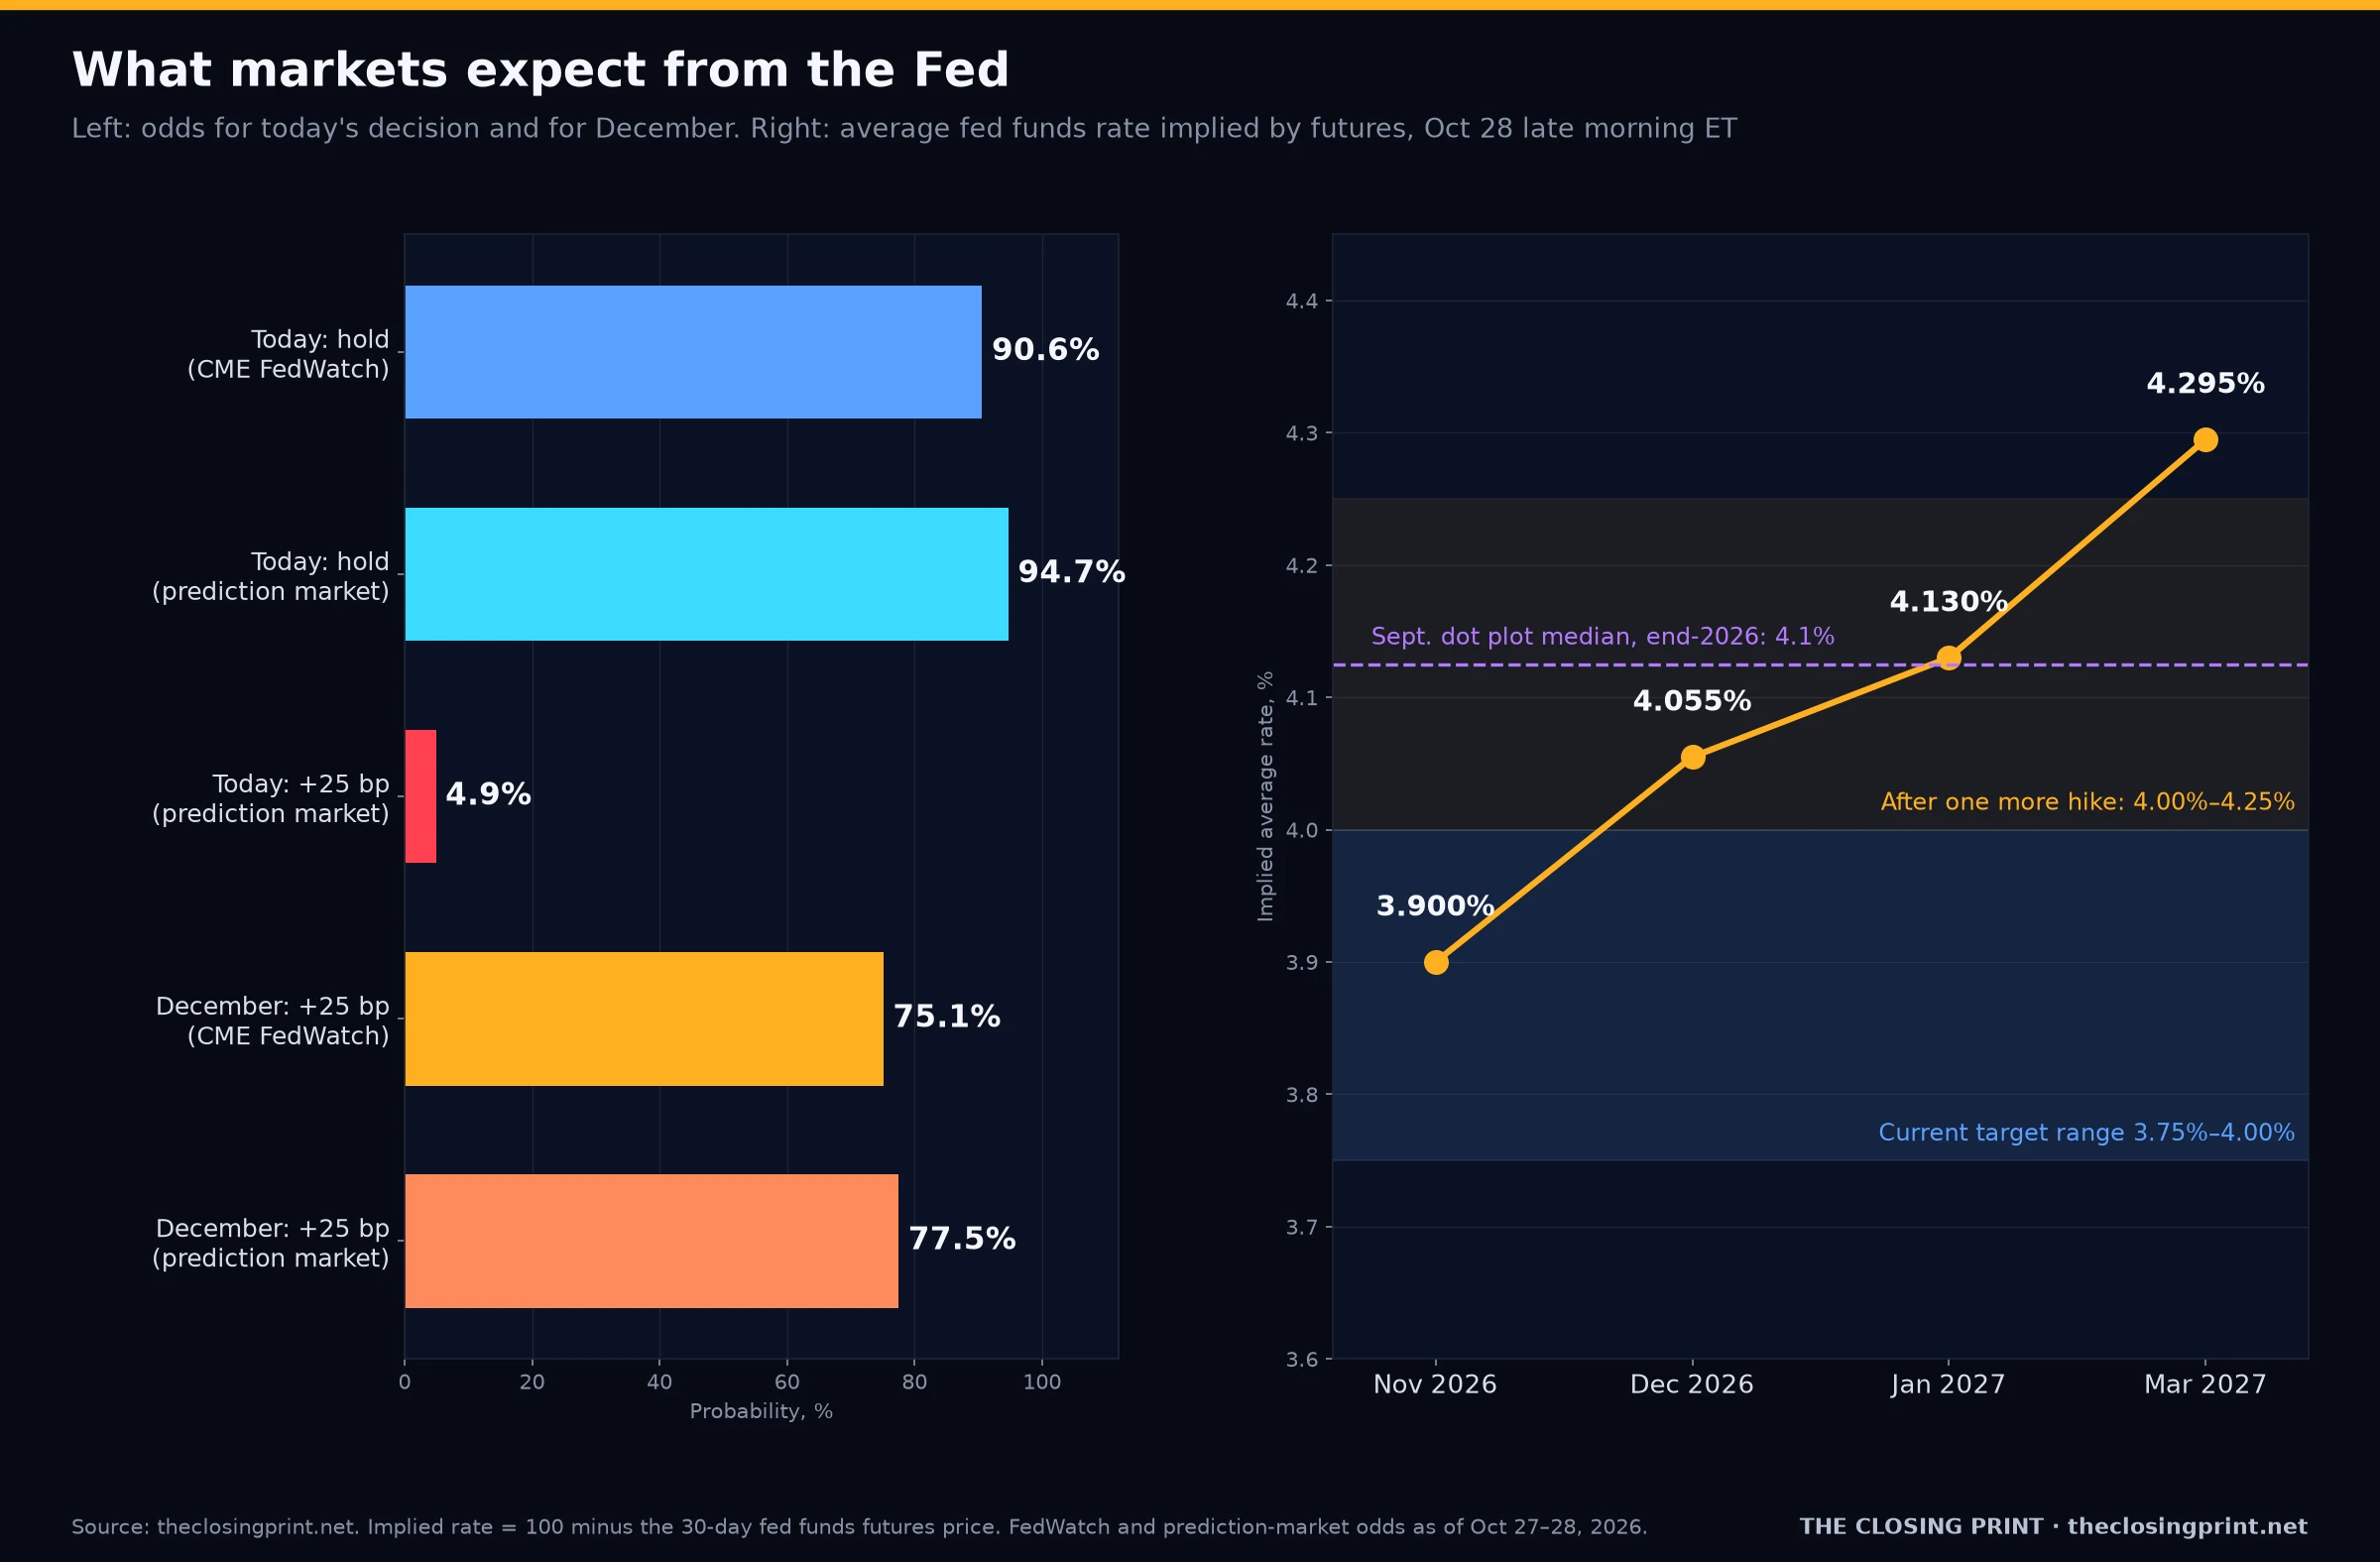
CME FedWatch puts the chance of a hold today at about 90.6%, up from 84.5% a week ago and 35.8% a month ago. On a large prediction market, “no change” trades near 94.7% and a quarter-point hike near 4.9%. A Reuters poll found 94 of 100 economists expect no change today, and all 100 expect a hike in December.
December is where the real bet is. FedWatch shows about a 75% chance of a quarter-point hike at the Dec 8–9 meeting, and prediction markets put it near 77.5%. Fed funds futures tell the same story: the November contract implies an average rate of 3.90%, December 4.055%, January 4.13% and March 2027 4.295%. That’s about one hike by year-end and a second by March. Markets price roughly 71 basis points of total hikes through September 2027.
Wick's call on the decision
| Question | Wick's call | Odds |
|---|---|---|
| Rate decision | Hold at 3.75%–4.00% | 90% |
| Surprise | Quarter-point hike to 4.00%–4.25% | 10% |
| Cut | No | about 0% |
| Vote | 10–2, with Beth Hammack (Cleveland) and Lorie Logan (Dallas) dissenting in favor of a hike | 40% |
| Other vote outcomes | 9–3 with Neel Kashkari (Minneapolis) also dissenting: 30%. 11–1: 15%. 12–0: 15% | 60% combined |
| Statement | Keeps “The Committee will deliver price stability”; drops September’s line about the rate move; describes job gains as slower and mentions energy prices | 70% |
| Balance sheet | No change: ample-reserves language stays, mortgage-backed securities keep running off slowly | 85% |
| New projections | None today. The next dot plot comes with the Dec 8–9 meeting | Scheduled |
| Press conference | Short, no promise on December, firm on inflation. “We don’t prejudge meetings” | 65% |
The rate. We expect a hold. The data say hike, but the people who set rates have said wait, and Warsh rarely surprises the committee’s center. The 10% for a hike reflects real risk: inflation has been hotter than expected for two months, Bank of America is still calling for a move today, and Warsh has said the bar for acting is inflation failing to come back to 2% “clearly and at sufficient speed.”
The vote. Hammack and Logan are the likeliest dissenters, because they pushed for a hike in July and have kept pressing since. Logan said this month that years of above-target inflation have “badly strained Americans’ budgets.” Kashkari is the swing vote. He said earlier that one more hike this year would be enough, but that was before the hot CPI. Two dissents would actually help Warsh, because they show the committee hasn’t given up on December without him having to say so.
The statement. Expect a short text again. We think the line about September’s move goes, “The Committee will deliver price stability” stays, and the jobs sentence changes from “job gains have kept pace with the workforce” to something closer to “job gains have slowed.” A mention of higher energy prices from the Middle East conflict is likely. A new line pointing to further tightening is possible but less likely, since Warsh avoids forward guidance.
Balance sheet. No change is the call. The Fed is continuing its policy of maintaining ample reserves, and it wants to get back to an all-Treasury balance sheet over time. Its mortgage-backed securities have fallen about 30% from the March 2022 peak of $2.7 trillion to $1.89 trillion. At the current pace, that could take close to 11 years, and nobody expects Warsh to speed it up with the 10-year near 5%.
The press conference
- Length: short. Powell often went about 45 minutes. Warsh is expected to keep his shorter, since he prefers to let the data do the talking.
- The key question: why hike in September but not now, with inflation hotter? Our guess at his answer is that the Fed is moving at a deliberate pace and wants to see how September’s hike and 5% yields are working through the economy. Expect a line close to “I don’t prejudge meetings.”
- What would read hawkish: calling the inflation pickup broad rather than an energy shock, or saying that the market’s December pricing is reasonable.
- What would read dovish: spending time on the 29,000 jobs number, the housing slowdown and tighter financial conditions, or calling energy a supply shock that rate hikes can’t fix.
- Politics: he will be asked about the White House and the midterms. He declined to discuss his conversations with the president in September, and we expect the same today.
Market reaction: scenarios and Wick's pick
| Scenario | Odds | What happens | S&P 500 | 2-yr / 10-yr | Dollar | Gold |
|---|---|---|---|---|---|---|
| Hawkish hold (Wick's pick) | 50% | Hold with two or three dissents for a hike; statement stresses inflation; Warsh leaves December fully open | -0.6% to +0.2% | +3 to +7 bp / 5.03%–5.10% | Firmer, DXY 102.5–103.0 | Softer, $4,000–$4,050 |
| Quiet hold | 40% | Hold with one dissent or none; Warsh points to tighter financial conditions and the weak September jobs number | +0.4% to +1.0% | -4 to -8 bp / 4.93%–4.99% | Softer, DXY 101.8–102.2 | Up, $4,080–$4,150 |
| Surprise hike | 10% | Quarter point to 4.00%–4.25%, a week before the midterms | -1.0% to -2.0% | +8 to +14 bp / 5.08%–5.18% | Stronger, DXY above 103 | Down, under $4,000 |
Wick's pick: hawkish hold (50%). We think the committee wants to hold without letting markets read it as a step back from tightening. Dissents and a firm statement do that cheaply. The 2-year yield (4.77% now) is the number to watch at 2:00 PM. If it rises, the market is reading the decision as “December is coming.” If it drops more than 5 basis points, the quiet-hold scenario is playing out. Our expected-move ranges are estimates, not forecasts of exact levels.
Cross-asset playbook
- Treasuries: the 10-year at 5% has been the line all month. A hawkish hold should keep it slightly above 5% and flatten the curve from 2 years to 10 years. A quiet hold would pull the 2-year down faster than the 10-year. Long bonds, such as the iShares 20+ Year Treasury Bond ETF (TLT) ($81.36, -0.3%), do best in the quiet scenario.
- Dollar: the US Dollar Index is at 102.34, just under its 52-week high of 102.95. A hawkish hold could push it to a new high, and the euro is at $1.1135, near its yearly low. The Invesco DB US Dollar Index Bullish Fund (UUP) tracks this trade.
- Gold: at $4,056.70 it is far below its $5,586 high and under its 50-day average, as higher real yields weigh on it. SPDR Gold Shares (GLD) is most sensitive to the 2-year. We’d expect gold to struggle unless Warsh leans dovish.
- Banks: the SPDR S&P Regional Banking ETF (KRE) is down 1.1% to $71.81 today. Higher short rates help lending margins, but a 7%-plus mortgage rate and 5% long yields hurt loan growth and bond portfolios.
- Tech and AI: a hawkish hold matters most for companies that borrow heavily to build AI capacity. See our AI financing deep dive on why the 10-year sets the price of every AI bond. MSFT ($528.18, -0.6%) and GOOGL ($323.20, +0.8%) report after the close, and their capex and cloud numbers will probably move the Nasdaq more than the Fed does. The Roundhill Memory ETF (DRAM) is up 5.7% on SK hynix’s results, as covered in our pre-market summary.
- Oil: WTI is up 2.4% to $102.33 and Brent is at $115.50 after the Houthi attack on Saudi Arabia’s largest refinery. Oil above $100 is the main reason inflation is running hot, and the main reason a hold today does not mean the Fed is done.
What to watch
- Wed Oct 28, 2:00 PM: FOMC rate decision and statement.
 .ics

- Wed Oct 28, 2:30 PM: Chair Warsh press conference..ics
- Wed Oct 28, 4:30 PM: Alphabet Q3 results call..ics
- Wed Oct 28, after the close: Microsoft fiscal Q1 results, call at 5:30 PM..ics
- Thu Oct 29, 8:30 AM: Q3 GDP (advance) and September PCE inflation..ics
- Thu Oct 29, 9:15 AM: ECB rate decision..ics
- Thu Oct 29, after the close: Amazon Q3 results..ics
- Tue Nov 3: US midterm elections..ics
- Fri Nov 6, 8:30 AM: October jobs report..ics
- Tue Nov 10, 8:30 AM: October CPI report..ics
- Wed Dec 9, 2:00 PM: December FOMC decision with new projections and dot plot..ics
Market data and opinions by Wick. This post is informational only and is not financial advice. Scenario odds and expected market moves are our estimates. Futures-implied rates and probabilities change throughout the day.
Add all 11 events to calendar (.ics) Times are ET. Each event has a 1-day reminder. Estimated dates are marked.