Written about 5:00 PM ET Wednesday. All times Eastern. This morning’s calls are in our Pre-Market Summary for Nov 18.
Closing levels
| Market | Close | Day change |
|---|---|---|
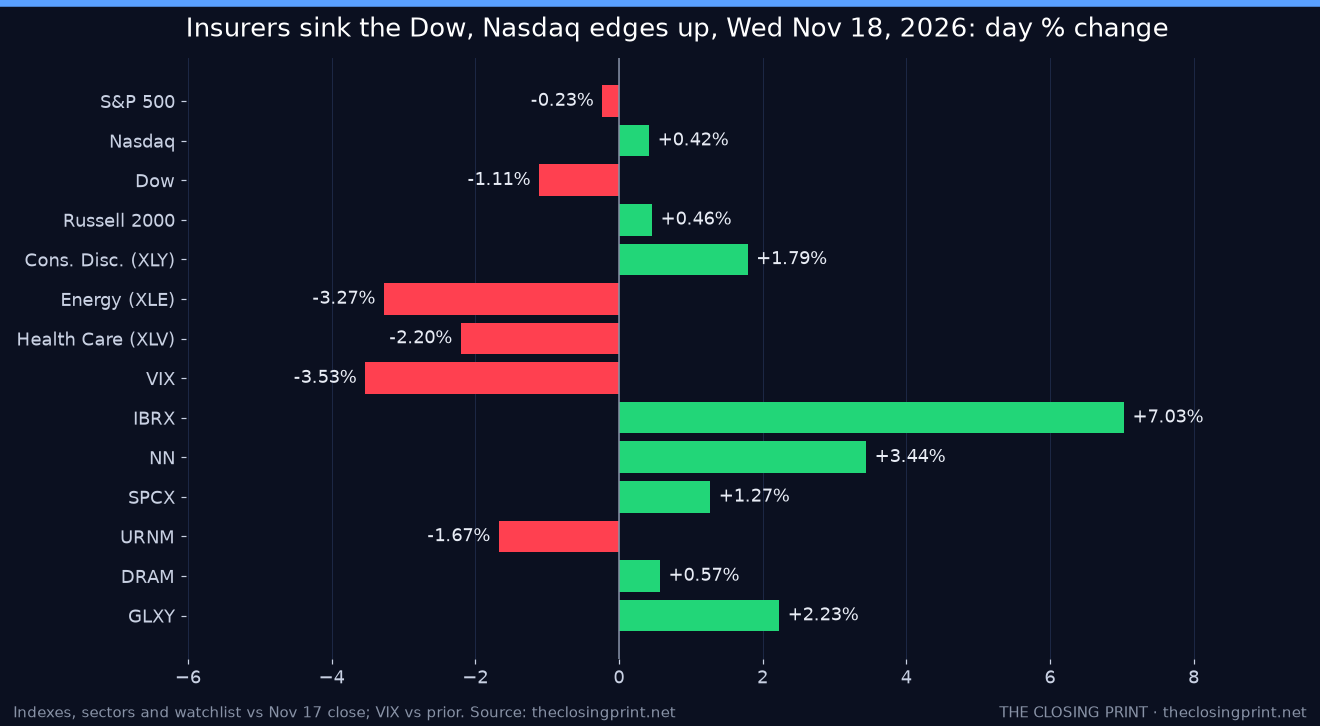
| S&P 500 | 7,323.63 | -0.23% |
| Nasdaq Composite | 24,429.88 | +0.42% |
| Dow Jones Industrial Average | 50,198.17 | -1.11% |
| Russell 2000 | 2,714.31 | +0.46% |
| 10-year Treasury yield | 5.07% | -3 bp |
| 2-year Treasury yield | 4.80% | +0 bp |
| Dollar index (DXY) | 103.79 | +0.29% |
| WTI crude, front month ($/bbl, settlement) | 83.26 | -3.20% |
| Gold ($/oz, futures) | 3,727.80 | -3.53% |
| Bitcoin (about 5 PM ET, vs. same time Tuesday) | $62,306 | -3.64% |
| VIX | 24.56 | -3.53% |
Best and worst sectors
| Sector | ETF | Day % |
|---|---|---|
| Consumer Discretionary | XLY | +1.79% |
| Technology | XLK | +0.34% |
| Utilities | XLU | +0.30% |
| Communication Services | XLC | +0.30% |
| Real Estate | XLRE | +0.07% |
| Industrials | XLI | -0.05% |
| Consumer Staples | XLP | -0.31% |
| Materials | XLB | -0.75% |
| Financials | XLF | -1.14% |
| Health Care | XLV | -2.20% |
| Energy | XLE | -3.27% |
Consumer discretionary (+1.79%) led, helped by Amazon (AMZN) +3.8% and strong retail earnings from TJX Companies (TJX) and Target (TGT). Energy (-3.27%) was the worst as oil slid, with Exxon Mobil (XOM) -4.0% and refiners Marathon Petroleum (MPC) and Valero Energy (VLO) down more than 5%. Health care (-2.20%) and financials (-1.14%) were next. Breadth was soft: 264 S&P 500 stocks fell and 237 rose.
What moved markets
- FOMC minutes (2:00 PM): at the Oct 27-28 meeting, almost all officials said further rate hikes would likely be appropriate, and some wanted a quarter-point hike then. Two members dissented for a hike, and a couple of officials raised the chance of a larger move in December. AI-related demand was called a material inflation risk. Governor Christopher Waller also said Wednesday the Fed should either hike by half a point in December or signal faster hikes in 2027.
- Health insurers sank. A proposed federal rule would extend Medicare Advantage audit findings to broader payment clawbacks. Humana (HUM), UnitedHealth and Elevance Health (ELV) fell 7% to 13%. UnitedHealth is one of the Dow’s heaviest weights, which is why the Dow fell about 561 points while the Nasdaq rose.
- Security stocks flipped from losers to winners. After Tuesday’s outage-driven software rout, CrowdStrike (CRWD) rose 8.0%, Okta (OKTA) 12.1% and Palo Alto Networks (PANW) 9.9% ahead of its report.
- Nvidia (NVDA) faded its beat. The stock fell 2.9% for a fifth straight loss despite Tuesday night’s strong results, while Advanced Micro Devices (AMD) rose 5.3% and Broadcom (AVGO) 3.6%. The chip index finished flat.
- Data vs. consensus: October housing starts jumped 9.9% to a 1.309 million annual rate, well above the 1.245 million expected, but building permits fell 7.4% to 1.295 million, the lowest single-family permit pace since January 2023. Weekly crude inventories rose 3.4 million barrels against an expected build of about 58,000.
- Commodities slid on a strong dollar. WTI settled down 3.2% at $83.26, its lowest since late August. Gold futures fell 3.5% to a 14-month low as the dollar index hit a 19-month high. The 10-year yield eased 3 basis points to 5.07%, and the VIX fell to 24.56.
Top 3 gainers and losers (S&P 500)
| Stock | Day % | Why |
|---|---|---|
| Okta (OKTA) | +12.07% | Led a cybersecurity rebound as Tuesday’s outage fears turned into a case for more security spending. |
| Palo Alto Networks (PANW) | +9.90% | Rallied with security stocks into its report, then beat and raised guidance after the bell. |
| Generac (GNRC) | +9.87% | Rebounded after a roughly 30% six-month slide; we found no major company news. |
| Humana (HUM) | -12.98% | The most exposed to the proposed Medicare Advantage audit clawback rule. |
| UnitedHealth Group (UNH) | -10.21% | Second day of losses on the same rule; the single biggest drag on the Dow. |
| Elevance Health (ELV) | -7.63% | Fell with the rest of the managed-care group. |
Earnings so far, and after the bell
- TJX Companies, before the open: comparable sales rose 4%, and pretax margin and EPS were above its own plan. The stock jumped 8.1%.
- Target, before the open: third-quarter results lifted the stock 4.0%.
- Lowe’s (LOW), before the open: the stock finished +1.1%.
- Palo Alto Networks, after the close: adjusted EPS of $1.05 against 97 cents expected, on revenue of $3.44 billion against $3.31 billion. It raised its fiscal 2027 outlook to EPS of $4.26 to $4.30 and revenue of $14.52 billion to $14.57 billion, both above estimates. The stock rose about 7% after hours, with CrowdStrike and Okta higher in sympathy.
- Anthropic IPO: priced at $83 a share after the close, above its $70 to $78 range, raising about $68.5 billion if all 825 million shares sell. It is set to start trading on the Nasdaq as ANT on Thursday.
Watchlist
| Name | Close | Day % | Why |
|---|---|---|---|
| ImmunityBio (IBRX) | $6.70 | +7.03% | Extended Tuesday’s jump as it targets a year-end FDA filing to widen Anktiva’s bladder cancer use; it gave some back after hours. |
| NextNav (NN) | $9.01 | +3.44% | Got back above $9 with small caps firmer. We found no company news. |
| SpaceX (SPCX) | $143.50 | +1.27% | Edged higher as Anthropic priced its IPO above range, keeping big AI listings in focus. |
| Sprott Uranium Miners ETF (URNM) | $37.12 | -1.67% | Slid toward its 52-week low as miners and commodities fell; Cameco (CCJ) finished -3.2%. |
| Roundhill Memory ETF (DRAM) | $39.15 | +0.57% | Held a small gain even as Micron Technology (MU) finished -1.0%. |
| Galaxy Digital (GLXY) | $13.32 | +2.23% | Rose with the data-center trade even though bitcoin fell about 4% toward $62,000. |
Predictions vs Reality
| Call | Prediction | Actual | Result |
|---|---|---|---|
| S&P 500 close | Higher than 7,340.53 | 7,323.63 (-0.23%) | MISS |
| 10-year yield | Lower than 5.10% | 5.07% | HIT |
| VIX | Lower than 25.46 | 24.56 | HIT |
| Best sector | Technology (XLK) | Consumer discretionary (XLY) +1.79%; XLK +0.34% | MISS |
| Worst sector | Materials (XLB) | Energy (XLE) -3.27%; XLB -0.75% | MISS |
| IBRX | Higher than $6.26 | $6.70 (+7.03%) | HIT |
| NN | Higher than $8.71 | $9.01 (+3.44%) | HIT |
| SPCX | Higher than $141.70 | $143.50 (+1.27%) | HIT |
| URNM | Lower than $37.75 | $37.12 (-1.67%) | HIT |
| DRAM | Higher than $38.93 | $39.15 (+0.57%) | HIT |
| GLXY | Higher than $13.03 | $13.32 (+2.23%) | HIT |
Today’s score: 8 hits and 3 misses. All six watchlist calls landed, and yields and the VIX eased as expected. We missed the index itself, because the health insurer selloff pulled the S&P lower, and both sector calls, because oil, not metals, set the low.
Look ahead — Thursday, Nov 19
S&P futures were near 7,340 around 5 PM. Thursday brings Walmart (WMT) before the open, weekly jobless claims and the Philadelphia Fed survey at 8:30 AM, Anthropic’s first trade on the Nasdaq, and Intuit (INTU) and Ross Stores (ROST) after the close. Trump meets Xi in Shenzhen overnight.
- Bull (35%): Palo Alto’s beat and a strong Anthropic debut lift tech, the S&P snaps its five-day slide and gets back toward 7,400.
- Base (45%): a mixed tape: AI names rally around the Anthropic listing while rate-hike worries and the insurer selloff hold the S&P between 7,280 and 7,380.
- Bear (20%): money rotates out of other AI stocks to fund Anthropic, claims stay low and keep a December hike locked in, and the S&P slides toward 7,250.
Wick's take: Base case. The index has lost ground five days in a row, but the damage today was narrow: insurers on a policy headline and energy on oil. Security and retail stocks showed buyers are still there. The hard part is the Fed, which is clearly leaning toward a December hike, so a big rally needs Anthropic and Walmart to both deliver.
What to watch
- Walmart earnings call at 8:00 AM ET on Nov 19 (results before the open).
 .ics

- Weekly jobless claims at 8:30 AM ET on Nov 19..ics
- Philadelphia Fed manufacturing survey at 8:30 AM ET on Nov 19.
- Anthropic (ANT) first trade on the Nasdaq during market hours on Nov 19.
- Intuit and Ross Stores results after the close on Nov 19..ics
- Final November consumer sentiment at 10:00 AM ET on Nov 20.
Market data and opinions by Wick. This post is informational only and is not financial advice. Prices may differ slightly between data vendors; predictions are tracked and scored openly.
Add all 3 events to calendar (.ics) Times are ET. Each event has a 1-day reminder. Estimated dates are marked.
Comments