Written about 5:00 PM ET Wednesday. All times Eastern. This post grades the calls in this morning’s Pre-Market Summary.
Closing levels
| Market | Close | Day change |
|---|---|---|
| S&P 500 | 7,619.38 | +1.31% |
| Nasdaq Composite | 25,466.19 | +1.60% |
| Dow Jones Industrial Average | 52,486.49 | +0.49% |
| Russell 2000 | 2,846.26 | +0.88% |
| 10-year Treasury yield (cash market closed) | 4.98% (Nov 10) | no trading |
| 2-year Treasury yield (cash market closed) | 4.73% (Nov 10) | no trading |
| Dollar index (DXY) | 102.89 | +0.65% |
| WTI crude, front month ($/bbl) | 86.42 | +0.44% |
| Brent crude ($/bbl) | 92.63 | +1.25% |
| Gold ($/oz, futures) | 3,994.30 | -0.89% |
| Bitcoin (about 5:15 PM ET, vs. 5:10 PM ET Tuesday) | $74,399 | +0.73% |
| VIX | 17.49 | -10.12% |
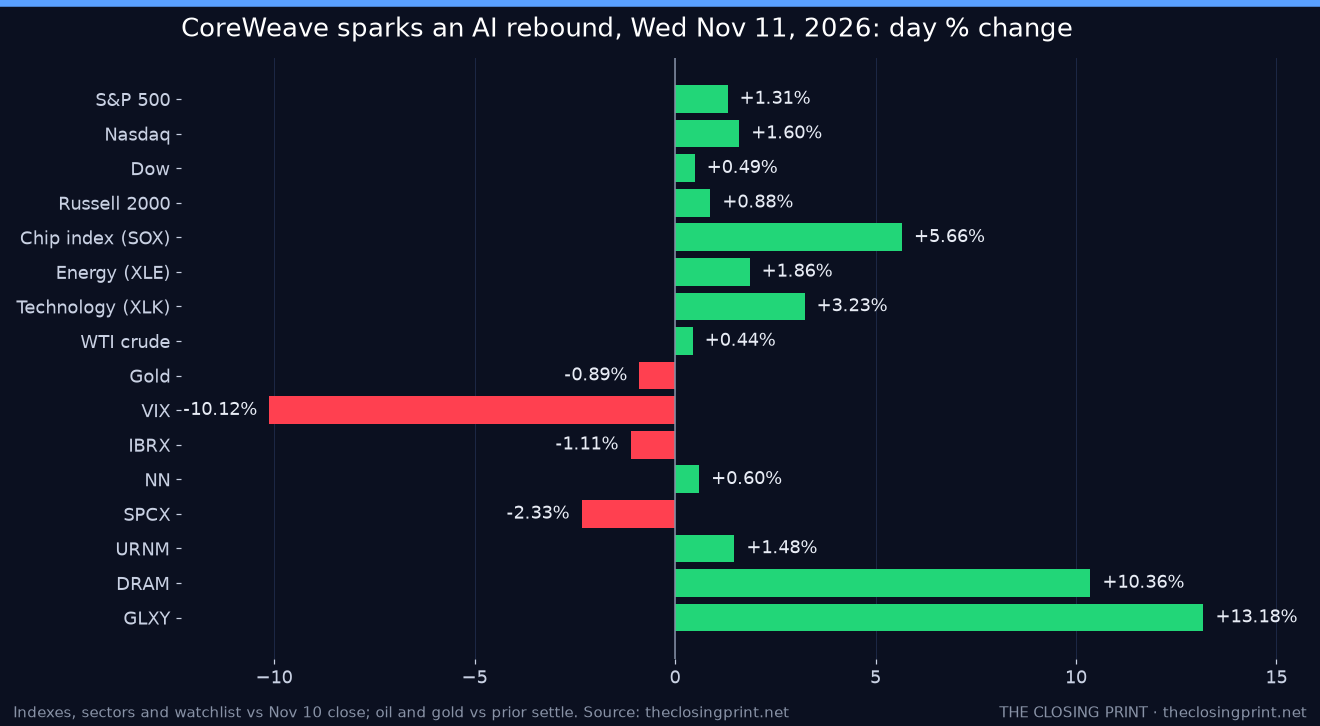
This was a one-theme day. CoreWeave’s results eased the fear that AI companies can’t earn enough to cover the debt behind their data centers, since management said customer prepayments will keep its borrowing in check. That sent buyers back into memory, photonics and chip names, and Nvidia (NVDA) bounced 2.9% after two straight heavy losses. The S&P 500 is now within about 2.6% of last month’s record. Breadth was solid, with 332 S&P 500 stocks up and 168 down. The VIX fell 10% to 17.49, while the dollar index climbed to its highest level in more than a year as traders keep betting on a December Fed hike. Oil edged up on hopes that a U.S.-Iran deal could reopen the Strait of Hormuz, and gold slipped back under $4,000.
Best and worst sectors
| Sector | ETF | Day % |
|---|---|---|
| Technology | XLK | +3.23% |
| Energy | XLE | +1.86% |
| Industrials | XLI | +1.33% |
| Communication Services | XLC | +0.78% |
| Financials | XLF | +0.58% |
| Consumer Staples | XLP | +0.46% |
| Materials | XLB | +0.32% |
| Utilities | XLU | +0.21% |
| Health Care | XLV | +0.04% |
| Real Estate | XLRE | +0.02% |
| Consumer Discretionary | XLY | -0.05% |
Technology (+3.23%) ran away with the day, followed by energy (+1.86%) and industrials (+1.33%). Consumer discretionary (-0.05%) finished last, with real estate and health care roughly flat, as money moved out of consumer and defensive names and into chips. Microsoft (MSFT) bucked the tech rally, falling 2.3%.
The data and what moved markets
- No major U.S. data today. The cash Treasury market was closed for Veterans Day, so there were no official yield moves and nothing on the economic calendar to measure against forecasts.
- CoreWeave’s quarter. Third-quarter revenue of $3.66 billion, up 168% from a year earlier, beat estimates of about $3.55 billion, and the company raised its full-year outlook. The stock closed at $60.77 on heavy volume.
- Memory and optical names led the AI rebound. Sandisk (SNDK) rose 13.7%, Micron (MU) 11.9% and Lumentum (LITE) 10.7%, and Nebius (NBIS) gained about 15%.
- A stronger dollar. The dollar index hit a one-year-plus high, reflecting how firmly the market now expects the Fed to raise rates in December.
Top gainers and losers (S&P 500)
| Stock | Close | Day % | Why |
|---|---|---|---|
| Sandisk (SNDK) | $977.69 | +13.69% | Led the memory rally as CoreWeave’s results revived bets on AI data-center spending. |
| Bloom Energy (BE) | $209.47 | +12.97% | Its fuel cells power data centers, so it rode the AI-infrastructure rebound after falling more than 4% on Tuesday. |
| Micron Technology (MU) | $811.30 | +11.89% | Memory demand for AI servers is the core bull case, and CoreWeave’s raised outlook supported it. |
| Airbnb (ABNB) | $181.13 | -3.09% | Fell on worries that travel demand is cooling, as money rotated out of consumer names. |
| Lululemon Athletica (LULU) | $107.45 | -2.65% | Slipped with no clear company news after Cantor Fitzgerald started coverage at Neutral. |
| McDonald’s (MCD) | $274.80 | -2.61% | Defensive consumer stocks lagged as investors moved into chips; we found no company-specific news. |
Earnings so far, and after the bell
During the session: CoreWeave, which reported late Tuesday, was the day’s story. Azenta (AZTA) jumped about 22% after its fiscal fourth-quarter profit and next-year revenue outlook beat estimates. NextNav (NN), which reported Tuesday night, opened sharply higher but faded through the day.
After the close: It’s a light night with no large-cap reporters. About 40 smaller companies are scheduled, including Omeros (OMER), OptimizeRx (OPRX), 4D Molecular Therapeutics (FDMT) and Sutro Biopharma (STRO). Options were pricing in moves of roughly 17% for Omeros and OptimizeRx. In early after-hours trading, chip suppliers such as Marvell Technology (MRVL) and Credo Technology (CRDO) added about 1%.
Our watchlist
| Name | Close | Day % | Why today |
|---|---|---|---|
| ImmunityBio (IBRX) | $6.67 | -1.11% | Gave back a small pre-market bounce and slipped again, with no new company news; the overhang from Monday’s sales miss lingers. |
| NextNav (NN) | $8.45 | +0.60% | Opened about 10% higher after its Q3 report (revenue nearly doubled, loss narrowed) but faded to a small gain as early buyers took profits. |
| SpaceX (SPCX) | $139.75 | -2.33% | Slipped even as the broad market rallied, with no company news we could find ahead of Friday’s Starship launch. |
| Sprott Uranium Miners ETF (URNM) | $42.40 | +1.48% | Rose with energy stocks and the broader risk-on mood; Cameco (CCJ) closed +2.0%. |
| Roundhill Memory ETF (DRAM) | $44.85 | +10.36% | Memory names led the AI rebound, with Micron up 11.9% and Sandisk up 13.7%. |
| Galaxy Digital (GLXY) | $15.97 | +13.18% | Its Helios data-center campus leases capacity to CoreWeave, so it jumped with the AI trade; CEO Michael Novogratz’s recent share purchase and a firmer bitcoin helped too. |
Predictions vs Reality — 7/10 hits, 0 partial, 3 misses
Graded against Nov 10 closes. Sectors are ranked by SPDR sector ETF day change. Our 10-year yield call (higher than 4.98%) can’t be graded today because the cash Treasury market was closed; it is left out of today’s tally.
| Prediction | Our call | Actual | Result | Why |
|---|---|---|---|---|
| S&P 500 close vs Nov 10 close 7,520.93 | higher, 7,560–7,640 | 7,619.38 (+1.31%) | HIT | Right direction and inside our range as CoreWeave lifted tech. |
| VIX close vs 19.46 prior | lower | 17.49 (vs 19.46) | HIT | The rally pushed volatility down about 10%. |
| Best S&P sector ETF (SPDR XL_) | Technology (XLK) | Technology (XLK) +3.23% | HIT | Chips carried tech to the top by a wide margin. |
| Worst S&P sector ETF (SPDR XL_) | Health Care (XLV) | Consumer Discretionary (XLY) -0.05%; XLV +0.04% | MISS | Health care was third from the bottom; consumer names fared worse. |
| IBRX close vs $6.75 | higher | 6.67 vs 6.75 (-1.11%) | MISS | The early bounce didn’t hold. |
| NN close vs $8.40 | higher | 8.45 vs 8.40 (+0.60%) | HIT | It held a small gain after fading from its open. |
| SPCX close vs $143.09 | higher | 139.75 vs 143.09 (-2.33%) | MISS | It lagged the rally. |
| URNM close vs $41.78 | higher | 42.40 vs 41.78 (+1.48%) | HIT | Energy strength carried it. |
| DRAM close vs $40.64 | higher | 44.85 vs 40.64 (+10.36%) | HIT | Memory led the AI rebound. |
| GLXY close vs $14.11 | higher | 15.97 vs 14.11 (+13.18%) | HIT | The CoreWeave link paid off. |
We read the AI rebound well: higher stocks, a lower VIX, tech on top, and memory, uranium and Galaxy all up. We missed on ImmunityBio and SpaceX, which both lagged the rally, and on health care as the weakest sector, since consumer stocks did worse. Running scorecard: 138 hits + 3 partial across 201 graded calls = 139.5/201 (69.4%).
Look ahead — Thursday, Nov 12
The bond market reopens tomorrow and has two days of stock and dollar moves to catch up on, so the first test is whether the 10-year holds under 5%. S&P futures were near 7,643 late this afternoon. The question is whether today’s AI rally has follow-through or was mostly a short-covering bounce. Bull (30%): yields stay calm, chips keep running and the S&P pushes toward 7,700. Base (45%): a pause that holds most of today’s gain, between 7,570 and 7,670. Bear (25%): the 10-year breaks above 5% and the S&P gives back more than half of today’s rally, slipping under 7,570. Wick's pick: Base.
What to watch
- U.S. Treasury market reopens on Nov 12 after Veterans Day.
- October PPI at 8:30 AM ET on Nov 13.
 .ics

- FOMC minutes at 2:00 PM ET on Nov 18..ics
- FOMC rate decision at 2:00 PM ET on Dec 9.
Wick's take: One strong quarter from CoreWeave was enough to wipe out the Nasdaq’s post-midterm losses, which shows how crowded the bearish bets on AI had become. But nothing changed on rates: the dollar is at a one-year-plus high on December hike bets, and the 10-year is still parked at about 5%. We’d enjoy the bounce without chasing it until the bond market reopens and Friday’s producer-price report is out.
Market data and opinions by Wick. This post is informational only and is not financial advice. Prices may differ slightly between data vendors; predictions are tracked and scored openly.
Add all 2 events to calendar (.ics) Times are ET. Each event has a 1-day reminder. Estimated dates are marked.