Written about 9:00 AM ET Wednesday, before the opening bell. All times Eastern; quotes as of about 8:45 AM ET.
Markets at about 8:45 AM ET
| Market | Level | Change |
|---|---|---|
| S&P 500 futures | 7,613.75 | +0.92% |
| Nasdaq 100 futures | 28,364.25 | +1.90% |
| Dow futures | 52,454.00 | +0.27% |
| Russell 2000 futures | 2,854.70 | +0.91% |
| 10-year Treasury yield | 4.98% (Nov 10 close); cash market closed today | 10-year note futures -0.15% |
| 2-year Treasury yield | 4.73% (Nov 10 close); cash market closed today | unavailable |
| US Dollar Index (DXY) | 102.69 | +0.45% |
| WTI crude ($/bbl) | $87.48 | +1.67% |
| Brent crude ($/bbl) | $92.93 | +1.57% |
| Gold ($/oz) | $4,042 | +0.29% |
| Bitcoin | $73,680 | about flat |
| VIX | 18.44 | -5.24% |
| Nikkei 225 (close) | 61,248.59 | +1.31% |
| Hang Seng (close) | 24,315.92 | -0.98% |
| KOSPI (close) | 5,375.36 | +2.60% |
| Shanghai Composite (close) | 3,680.64 | +0.46% |
| Euro Stoxx 50 | 6,367.28 | +0.62% |
| DAX | 26,538 | +0.72% |
| FTSE 100 | 10,794 | +0.40% |
| CAC 40 | 8,302 | +0.28% |
Futures vs prior settle. The cash Treasury market is closed for Veterans Day, so live 10-year and 2-year yields are unavailable.
What’s moving before the bell
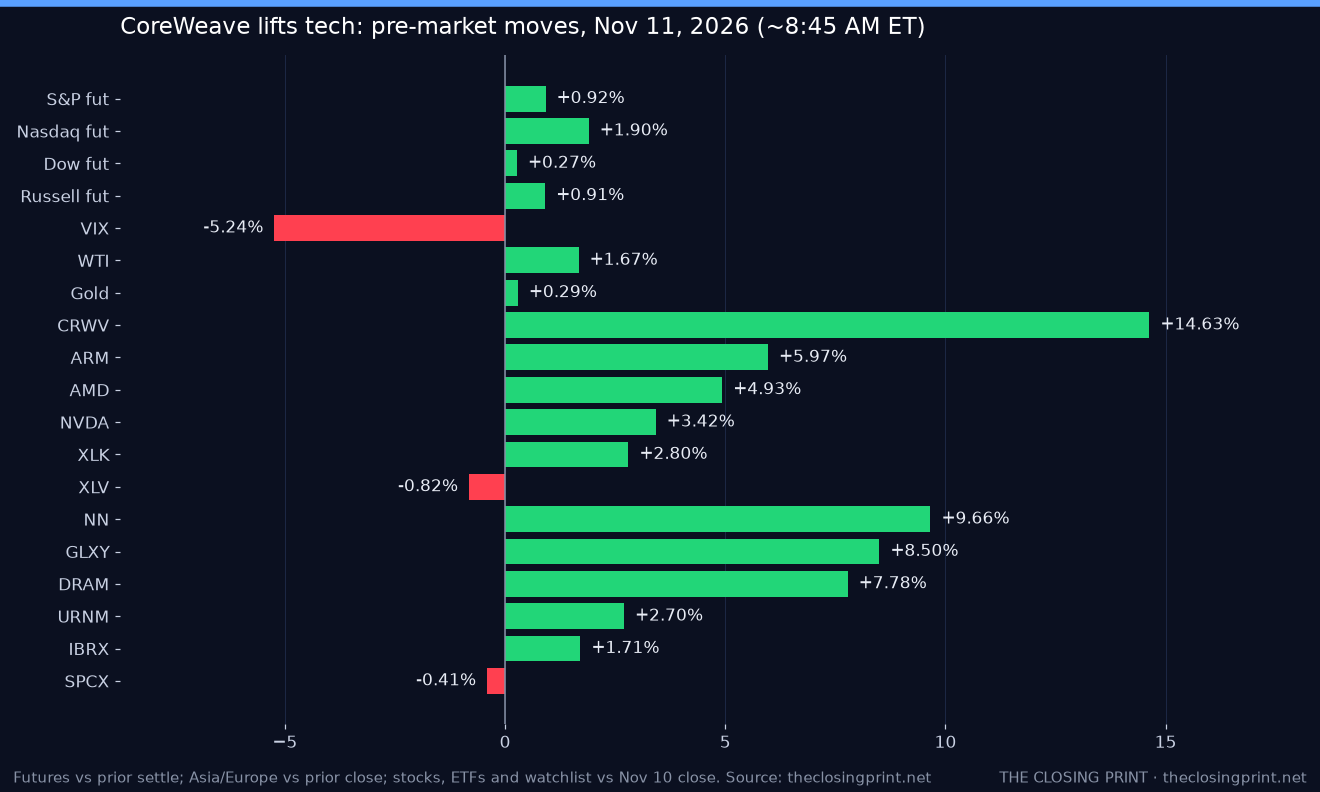
CoreWeave lifts the AI complex. CoreWeave (CRWV) is up about 15% after beating third-quarter revenue estimates, raising its full-year outlook and saying it expects to turn profitable on an adjusted basis in the first half of 2028. Chip and AI infrastructure names are following: Nvidia (NVDA) is up 3.4%, Advanced Micro Devices (AMD) 4.9%, Arm Holdings (ARM) 6.0%, Oracle (ORCL) 4.8% and Broadcom (AVGO) 4.0%.
TSMC bets on AI labs. Taiwan Semiconductor Manufacturing’s board approved investing $500 million each in Anthropic and OpenAI, adding to the AI-funding headlines ahead of Anthropic’s IPO.
Rates take a holiday. The bond market is closed for Veterans Day, after Tuesday’s hot October CPI pushed the 10-year to 4.98% and the 2-year to 4.73%. The debate over a half-point December hike, which Fed Governor Christopher Waller put on the table, is unresolved; the dollar is firmer (DXY 102.69).
Oil bounces off two-month lows. WTI is $87.48 (+1.7%) and Brent $92.93 as renewed strikes in the region and attacks on shipping near the Strait of Hormuz tempered hopes for a quick US-Iran deal, even though Qatar said it secured at least two weeks for diplomacy.
Losers: GoPro (GPRO) fell more than 10% early in pre-market trading after delaying its earnings release and warning that its planned merger could be at risk. Defensive sectors are lagging as money rotates back into tech.
Overseas: Asia was mixed: the KOSPI rose 2.6% and the Nikkei 1.3% to 61,249, while Hong Kong fell 1.0%. Europe is higher, with the DAX up about 0.7% and the Euro Stoxx 50 0.6%.
Economic calendar and Fed (ET)
- No US economic releases, Fed speakers or Treasury auctions today; the bond market and federal offices are closed for Veterans Day, while stocks trade normally.
- Thursday: weekly jobless claims at 8:30 AM, existing home sales at 10:00 AM, and Fed Governor Michael Barr, San Francisco Fed President Mary Daly and New York Fed President John Williams speak.
 .ics

- Friday: October PPI at 8:30 AM..ics
Earnings
Before the open: CGI (GIB), ICL Group (ICL), Rumble (RUM), Boyd Group Services (BGSI), Nayax (NYAX) and ODDITY Tech (ODD).
After the close: Franco-Nevada (FNV), Tetra Tech (TTEK), CAE (CAE), Corteva (CTVA), OR Royalties (OR), EnerSys (ENS) and Teekay Tankers (TNK).
Watchlist setups
- ImmunityBio (IBRX) $6.86 (+1.7% vs $6.75 close): a modest bounce attempt after Monday’s earnings plunge; dilution worries still cap rallies.
- NextNav (NN) $9.21 (+9.7% vs $8.40 close): the biggest mover on the list after last night’s Q3 report and 900 MHz update; watch whether the gap holds past the first half hour.
- SpaceX (SPCX) $142.50 (-0.4% vs $143.09 close): flat for now despite the tech rally; Friday’s Starship launch is the next catalyst.
- Sprott Uranium Miners ETF (URNM) $42.91 (+2.7% vs $41.78 close): rebounding with oil and a broader bid for energy and AI-power plays.
- Roundhill Memory ETF (DRAM) $43.80 (+7.8% vs $40.64 close): one of the strongest pre-market movers as memory stocks rally on the AI spending read from CoreWeave.
- Galaxy Digital (GLXY) $15.31 (+8.5% vs $14.11 close): up sharply with AI data-center names even as bitcoin sits flat near $73,700.
Scenarios and Wick's pick
- Bull (30%): the AI rebound broadens, chips extend gains all day and the S&P closes above 7,640.
- Base (50%): a tech-led gain on light holiday volume; the S&P closes 7,560–7,640.
- Bear (20%): the gap fades as hike worries return and oil keeps rising; the S&P closes below 7,560.
Wick's pick: Base. With no data and no bond trading, the CoreWeave read should carry the day, but light volume and Friday’s PPI argue against chasing the gap too hard.
Predictions for today’s close
| Prediction | Call | Confidence | Why |
|---|---|---|---|
| S&P 500 close vs Nov 10 close 7,520.93 (implied open ~7,590) | higher (7,560–7,640) | medium (60%) | Futures are up about 0.9% as CoreWeave’s results revive the AI trade. |
| 10-year yield vs 4.98% Nov 10 close (next cash close Nov 12) | higher | low (50%) | Cash Treasuries are shut for Veterans Day; note futures are slightly lower, which points to a touch higher yields. |
| VIX close vs 19.46 prior | lower | medium (60%) | Already down about 5% with futures green and no data on the calendar. |
| Best S&P sector ETF (SPDR XL_) | XLK | medium (50%) | Tech leads pre-market at about +2.8%, driven by chips and AI infrastructure names. |
| Worst S&P sector ETF (SPDR XL_) | XLV | low (35%) | Money is rotating out of defensives; health care (−0.8%) and staples (−0.6%) are weakest. |
| IBRX close vs $6.75 | higher | low (50%) | Up about 1.7% pre-market, a small bounce after its post-earnings slide. |
| NN close vs $8.40 | higher | low-medium (55%) | Up about 9.7% pre-market after Q3 results last night, though trade is thin. |
| SPCX close vs $143.09 | higher | low (50%) | Little changed pre-market; a risk-on tape and Friday’s Starship launch could lift it. |
| URNM close vs $41.78 | higher | low-medium (55%) | Up about 2.7% with oil and the energy complex rebounding. |
| DRAM close vs $40.64 | higher | medium (60%) | Up about 7.8% pre-market as memory and chip names rally behind CoreWeave. |
| GLXY close vs $14.11 | higher | low-medium (55%) | Up about 8.5% pre-market on the AI data-center rebound, even with bitcoin flat. |
What to watch
- 9:30 AM ET: Opening bell; watch whether chips hold their pre-market gains.
- Nov 12, 8:30 AM ET: Weekly jobless claims..ics
- Nov 12, 10:00 AM ET: Fed Governor Michael Barr speaks.
- Nov 12, 6:30 PM ET: New York Fed President John Williams speaks.
- Nov 13, 8:30 AM ET: October PPI..ics
- Dec 9, 2:00 PM ET: FOMC decision.
Add all 2 events to calendar (.ics) Times are ET. Each event has a 1-day reminder. Estimated dates are marked.
Not financial advice. Model estimates and opinions by Wick, for information only. Pre-market quotes can be thin and stale, and predictions are tracked and scored openly after the close.