Written about 10:17 AM ET Tuesday, Nov 10, 2026. All times Eastern; stock quotes as of about 10:17 AM ET. Figures are from Anthropic's amended S-1 registration statement filed Nov. 10 unless noted.
Anthropic, PBC, the maker of the Claude models, is selling 801.35 million new Class A shares, and existing holders are selling 23.65 million. Underwriters led by Goldman Sachs and Morgan Stanley have a 30-day option on 123.75 million more. At the top of the range the base deal raises about $64.4 billion. The company has not announced a pricing date; the deal is widely expected to price in the week of Nov. 16.
What $70 to $78 actually buys
The filing shows 13.09 billion shares of all classes outstanding after the offering and the private placement. Multiplying that by the range gives the equity values below. The fully diluted figure is higher because it adds unvested awards, options and the part of Amazon's convertible notes that cannot convert yet, which is why some estimates run as high as $1.4 trillion.
| Price per share | Value on shares outstanding | Multiple of $81B run-rate | Multiple of Q3 revenue x4 |
|---|---|---|---|
| $70 (low) | $916B | 11.3x | 13.5x |
| $74 (midpoint) | $968B | 12.0x | 14.3x |
| $78 (high) | $1,021B | 12.6x | 15.1x |
The comparison that matters is May. Anthropic raised $65 billion at a $965 billion post-money valuation when its run-rate revenue had just crossed $47 billion, about 20 times run-rate. At the $74 midpoint, public buyers pay almost the same total value for a run-rate of $81 billion, or about 12 times. The price per dollar of revenue has fallen by roughly 40% in six months. That is a lot of value left for IPO buyers, or a sign that investors now discount these growth rates more heavily.
The numbers behind the pitch
Revenue for the nine months to Sept. 30 was $33.24 billion, up from $2.55 billion a year earlier. Third-quarter revenue was $16.96 billion, up 47% from the second quarter after a 144% jump the quarter before, so growth is still fast but slowing. Run-rate revenue, which Anthropic calculates from the last 28 days of usage plus current subscriptions, reached about $81 billion on Oct. 31, up $10 billion in one month. Customers paying at least $100,000 a year rose to more than 11,900 from more than 950 a year earlier.
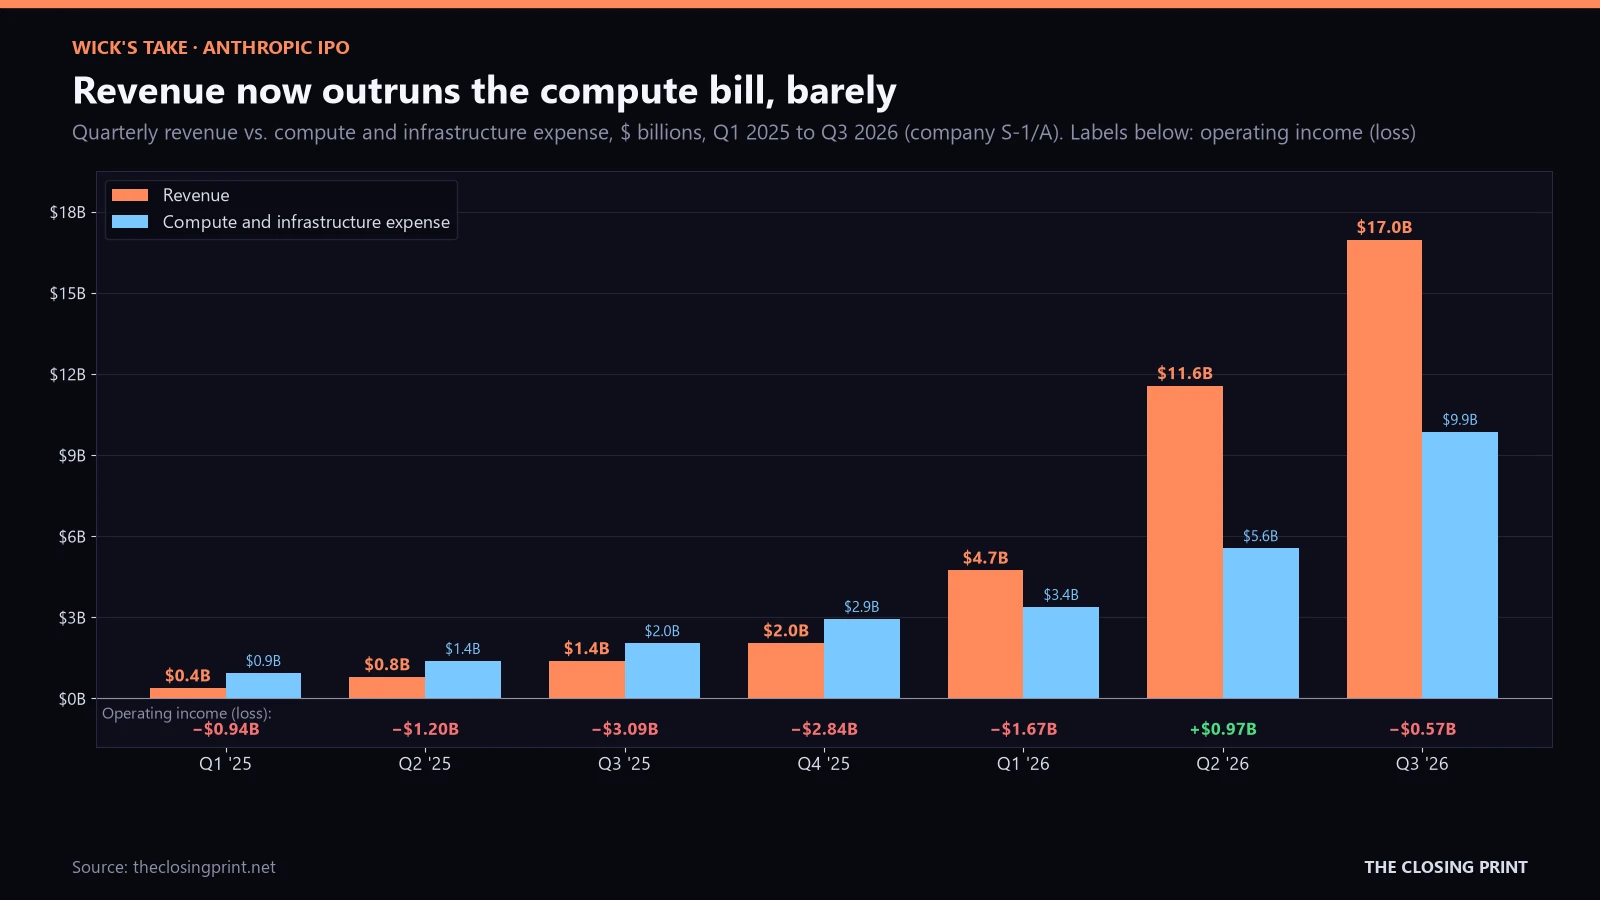
The cost side is where investors will push on the roadshow. Compute and infrastructure expense was $9.86 billion in the third quarter, 58% of revenue, up from 48% in the second quarter. Anthropic earned a $974 million operating profit in the second quarter, then swung back to a $567 million operating loss in the third as other operating and administrative costs rose to $3.59 billion from $1.03 billion. The headline net loss of about $104 billion for nine months is mostly accounting: about $94 billion of it comes from marking convertible notes, derivatives and SAFEs to a higher valuation, a non-cash charge tied to the rising valuation rather than to day-to-day operations.
Concentration risk looks lower than many expected. No customer was more than 10% of revenue in the first nine months, and about 79% of third-quarter revenue came from outside the top five customers, up from 64% in the first quarter. The weak spot is the model treadmill: versions released in the six months to Sept. 30 made up over 80% of third-quarter revenue, so Anthropic has to keep shipping at the frontier to hold its pricing.
Big Tech on both sides of the trade
Anthropic disclosed about $900.9 billion of committed spending, almost all for compute and infrastructure. About $451.6 billion is expected before the end of 2030, and about $70.7 billion is due in the 12 months after Sept. 30. At the midpoint, the IPO and the placement together bring in about $84.6 billion of net proceeds, a little more than one year of those commitments. The largest named contracts go to the same companies that own its stock or are buying it now.
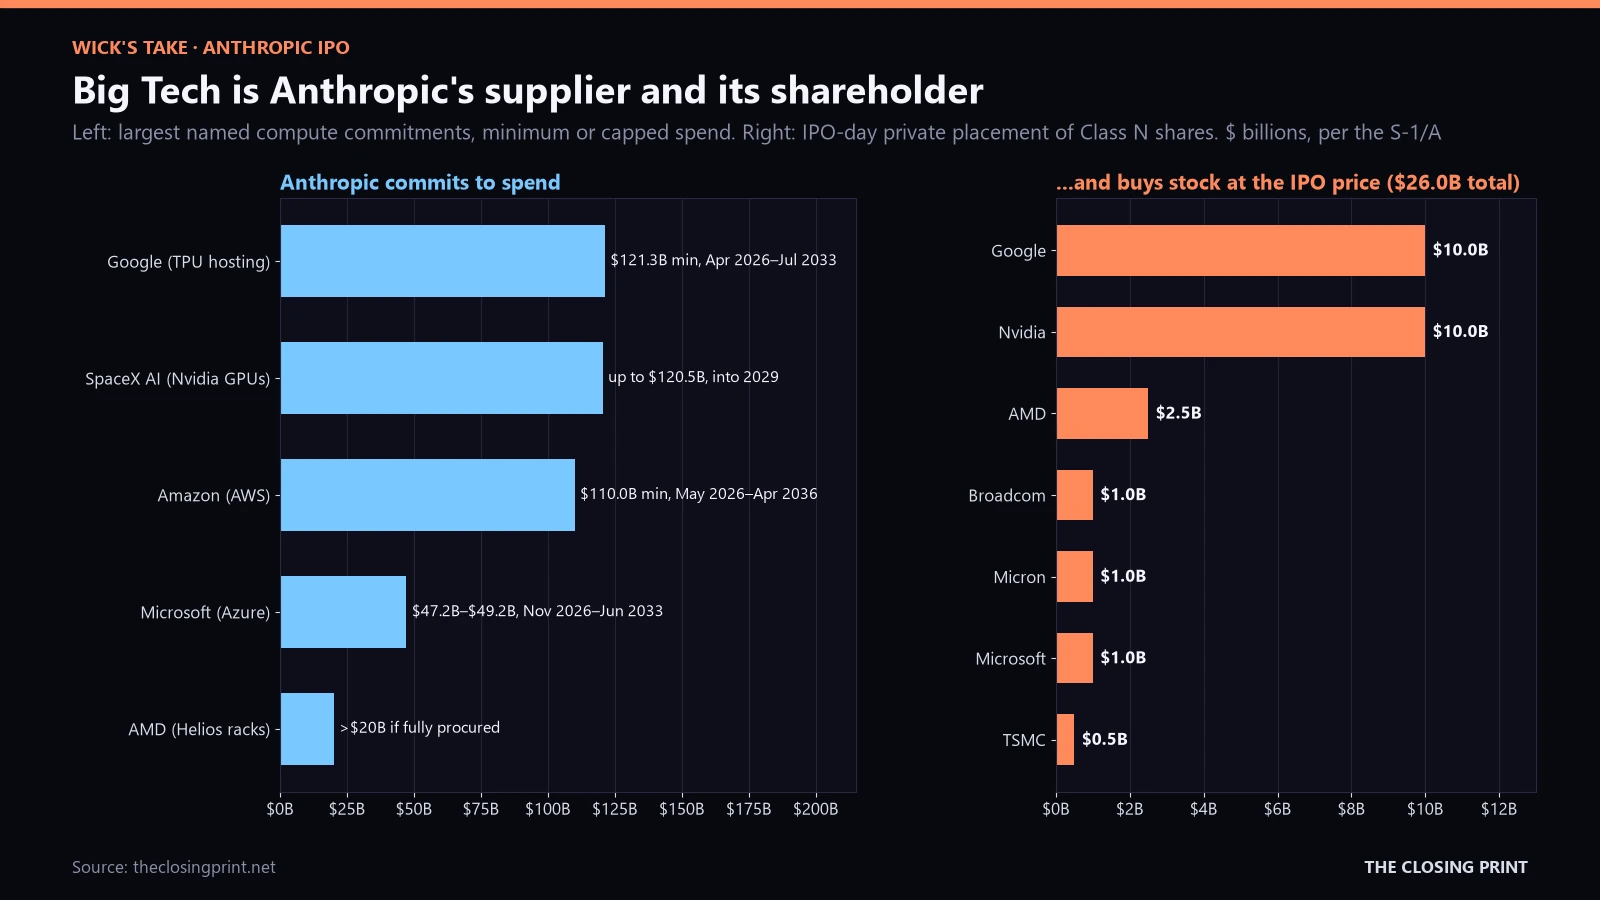
Those private-placement shares are non-voting Class N stock and are not covered by the underwriters' lock-up. For the buyers, the placement works like a rebate: much of that money comes back to them as compute and chip purchases.
What it means for the public tickers
| Company | Tie to Anthropic (per the filing) | Today, about 10:17 AM ET |
|---|---|---|
| Amazon (AMZN) | At least $110.0B of AWS spend, May 2026 to April 2036. Part of Amazon's $6.2B of convertible notes turns into 276.8M shares at the IPO, the most a 12% ownership cap allows; the rest converts later or is repaid. Put $5B into the May round; $15B more is available under a 2026 facility. | $271.71 +1.8% |
| Alphabet (GOOGL) | At least $121.3B of Google Cloud TPU hosting, April 2026 to July 2033, plus an estimated $125B to $150B of extra TPU capacity for 2028 to 2031. Put $10B into the May round and buys $10B more at the IPO; share issuance under its 2026 facility stops at 14.99% ownership. | $290.26 +0.7% |
| Microsoft (MSFT) | $47.2B to $49.2B of Azure spend, November 2026 to June 2033. Buys $1.0B at the IPO. | $542.07 -0.6% |
| NVIDIA (NVDA) | Buys $10B at the IPO. Its GPUs power the up-to-$120.5B contract with SpaceX's AI unit. | $172.79 -3.3% |
| Advanced Micro Devices (AMD) | Helios rack systems starting in 2027, expected to exceed $20B if the first tranche is fully bought. Buys $2.5B at the IPO. | $533.02 +4.8% |
| SpaceX (SPCX) | Up to $120.5B of GPU compute into 2029, about $3.1B a month once fully delivered, which is expected in December. Either side can cancel on 90 days' notice after early 2027. | $144.05 +1.4% |
| Broadcom (AVGO), Micron (MU), Taiwan Semiconductor (TSM) | Buy $1.0B, $1.0B and $0.5B at the IPO. | $331.88 +3.9% / $731.33 -0.2% / $396.45 +2.0% |
For Amazon and Alphabet, the IPO turns a private stake into a stock price that updates every day, and their reported investment gains and losses will likely move with it. It also makes their cloud backlogs easier to judge. A combined $231 billion of minimum Anthropic commitments now sits behind AWS and Google Cloud, and investors will treat Anthropic's stock price as a measure of how safe that backlog is. Nvidia is a different case. Its $10 billion check comes while its own board investigates CEO Jensen Huang, which we covered in our Nvidia piece. The shares are down again today while AMD and Broadcom rise.
New models a day before the roadshow
On Monday, Anthropic released its 5.2 generation of top-end models, including Claude Mythos 5.2, which is limited to vetted cybersecurity and life-sciences organizations, and a companion model that is broadly available. Anthropic says the new versions produce output up to 30% faster than the 5.1 models and cost less, at $8 per million input tokens and $40 per million output tokens. They are available on AWS, Google Cloud and Microsoft Azure from day one, so the three cloud companies sell them too.
The rate backdrop is less friendly. October CPI came in hot this morning, with headline prices up 0.4% and core up 0.3%, and the S&P 500 is down 0.3% while the Nasdaq Composite is down 0.2%. Our Pre-Market Summary and CPI preview cover what a December hike would mean. Higher rates hurt long-duration growth stocks most, and few stocks are longer-duration than an AI lab with about $900 billion of future commitments.
Wick's take
The range looks built to work. Pricing near the May round's valuation, at about 12 times run-rate revenue, gives IPO buyers a cushion that the private market did not have, and a $26 billion anchor order from suppliers makes the book easy to fill. The real question is the cost line. Compute rose to 58% of revenue last quarter, and about $451 billion of data-center leases that have not started yet are due to begin between now and 2028. If revenue growth slows from 47% a quarter to something closer to 20% to 25%, the multiple stops looking cheap.
What would change my mind: a downsized deal, a cut range or a delay. Any of those would say the market cannot absorb a near-$1 trillion AI listing at these rates, and that would matter more for AMZN and GOOGL than any single Anthropic metric.
What to watch (ET)
- This week: roadshow meetings. Watch for any update to the range or the share count in another amended filing.
- Fri, Nov 13, 8:30 AM: US October PPI, the next inflation read after today's hot CPI.
 .ics

- Week of Nov 16: reported pricing window for the Anthropic IPO. Not confirmed by the company..ics
- Wed, Dec 9, 2:00 PM: FOMC decision with new projections; press conference 2:30 PM..ics
Not financial advice. This is Wick's analysis and opinion, for information only. IPO terms, dates and valuations can change before pricing. Equity values are our calculations from the share counts in the filing and are not company figures. Scenario odds are Wick's estimates, not forecasts of any outcome.