Written about 5:00 PM ET Tuesday. All times Eastern. This post grades the calls in this morning’s Pre-Market Summary.
Closing levels
| Market | Close | Day change |
|---|---|---|
| S&P 500 | 7,520.93 | -0.38% |
| Nasdaq Composite | 25,065.88 | -0.74% |
| Dow Jones Industrial Average | 52,231.89 | -0.30% |
| Russell 2000 | 2,821.38 | -0.68% |
| 10-year Treasury yield | 4.98% | +10 bp |
| 2-year Treasury yield | 4.73% | +17 bp |
| Dollar index (DXY) | 102.25 | +0.59% |
| WTI crude, front month ($/bbl) | 86.45 | -0.46% |
| Brent crude ($/bbl) | 92.03 | -0.58% |
| Gold ($/oz, futures) | 4,040.40 | -1.80% |
| Bitcoin (about 5:10 PM ET, 24-hour change) | $73,863 | -1.46% |
| VIX | 19.46 | -2.31% |
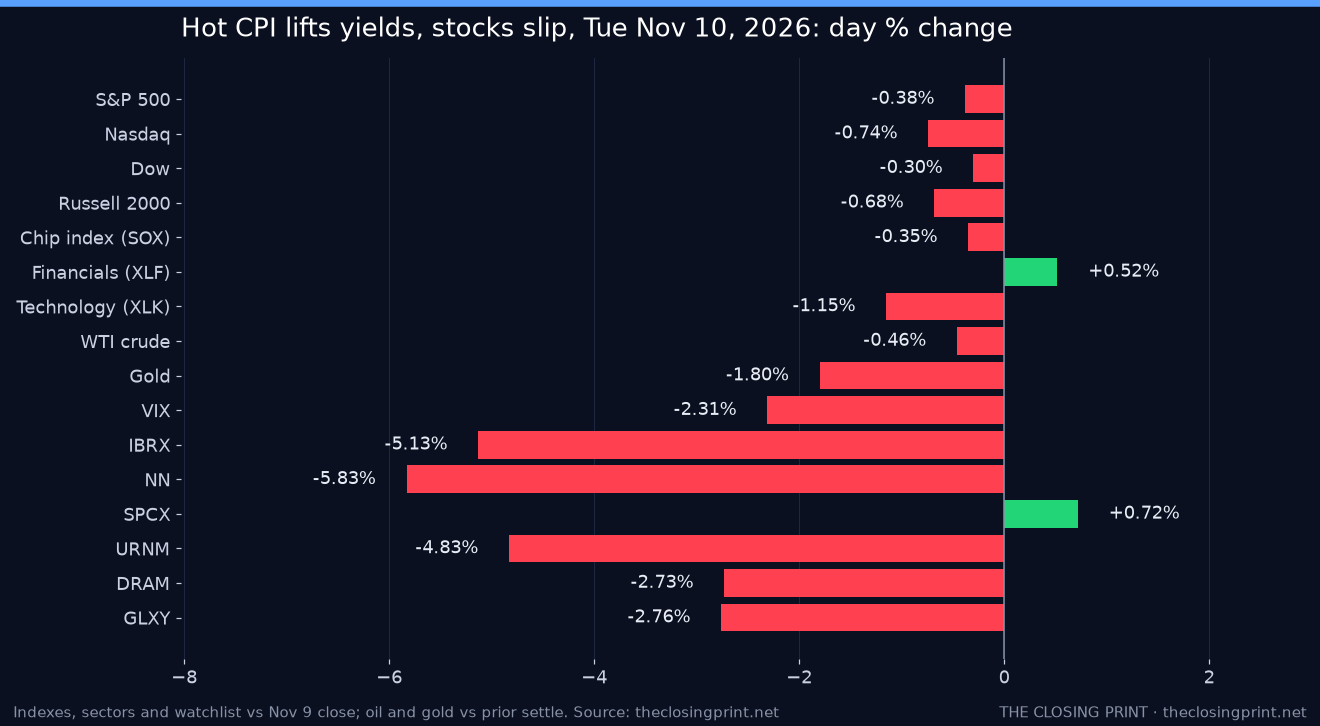
The bond market did the damage. Consumer prices rose 0.4% in October against a 0.3% forecast, the third straight monthly gain of 0.4% or more, and that came right after Fed Governor Christopher Waller said a December hike is warranted and a half-point move should be on the table if inflation worsens. Futures pricing now shows a December hike as a certainty, with rising odds of a half point. Dallas Fed President Lorie Logan added that at least two more quarter-point hikes may be needed. The selling was concentrated in tech, while breadth was close to even, with 246 S&P 500 stocks up and 248 down, and buyers trimmed the losses late in the day. Oil eased again to near two-month lows, and the VIX actually slipped to 19.46.
Best and worst sectors
| Sector | ETF | Day % |
|---|---|---|
| Financials | XLF | +0.52% |
| Energy | XLE | +0.44% |
| Communication Services | XLC | +0.37% |
| Health Care | XLV | +0.29% |
| Consumer Staples | XLP | +0.15% |
| Consumer Discretionary | XLY | +0.03% |
| Industrials | XLI | -0.09% |
| Real Estate | XLRE | -0.13% |
| Utilities | XLU | -0.14% |
| Materials | XLB | -0.17% |
| Technology | XLK | -1.15% |
Financials (+0.52%) led, since banks tend to benefit from higher rates, with energy (+0.44%) and communication services (+0.37%) close behind. Technology (-1.15%) was the clear laggard as Nvidia’s slide weighed on the group, though Broadcom (AVGO) rose 3.9% and Advanced Micro Devices (AMD) 1.3%.
The data and what moved markets
- October CPI: +0.4% vs. +0.3% expected. Core prices rose 0.3%, a level Waller had flagged as enough to consider a half-point hike, and that was despite a 1.2% drop in used-car prices. There was no official annual rate this month because of gaps left by last year’s government shutdown.
- Fed speakers leaned hawkish. Waller, Logan and Kansas City Fed President Jeff Schmid all pointed toward tighter policy; Fed Vice Chair for Supervision Michelle Bowman called inflation the top priority without calling for hikes.
- Yields jumped. The 2-year had one of its biggest one-day gains since April 2025, and the 10-year closed just under 5%.
- Nvidia fell again. It dropped 5.5% as lawmakers took aim at its chip sales to China in the wake of the board’s investigation into CEO Jensen Huang.
- A late lift from Anthropic. Stocks bounced off their lows after reports that Anthropic’s roughly $60 billion IPO next week is already fully subscribed.
Top gainers and losers (S&P 500)
| Stock | Close | Day % | Why |
|---|---|---|---|
| Charter Communications (CHTR) | $134.06 | +10.61% | Offered to buy back up to $1.5 billion of long-dated, low-coupon debt below face value, which speeds up paying down its debt. |
| Take-Two Interactive (TTWO) | $224.64 | +8.31% | Fiscal second-quarter profit ($1.00 a share, adjusted) and revenue ($1.60 billion) beat estimates. |
| CVS Health (CVS) | $89.01 | +4.41% | Beat on third-quarter profit, raised its full-year outlook to at least $8.20 a share and announced plans to split into two companies. |
| Skydance (SKYD) | $8.04 | -7.59% | Third-quarter revenue came in just short of estimates, and it laid out a $6 billion, three-year cost-cutting plan. |
| Moderna (MRNA) | $250.83 | -6.75% | Investors took profits after a huge run this year, with several analysts arguing the stock’s valuation has gotten ahead of the business. |
| First Solar (FSLR) | $180.98 | -5.55% | Extended Monday’s slide as solar stocks kept giving back their post-election gains. |
Earnings so far, and after the bell
During the session: CVS and Take-Two led the reporters, while Skydance slipped on its revenue miss and cost-cut plan. Anthropic set the price range for its IPO this morning (more in our Anthropic IPO piece).
After the close: CoreWeave (CRWV) rose about 1% to 2% after third-quarter revenue of $3.66 billion beat estimates of about $3.55 billion, and it raised its full-year revenue outlook to $13 billion to $13.3 billion. It also raised this year’s capital spending plan to as much as $39 billion. NextNav (NN) jumped about 8% to 9% after revenue nearly doubled from a year earlier, its loss narrowed to 4 cents a share and cash grew to $264.1 million. StubHub (STUB) slipped after missing on revenue and profit, Rigetti Computing (RGTI) fell about 7% on a revenue miss, and Fossil (FOSL) surged about 25% after returning to a profit.
Our watchlist
| Name | Close | Day % | Why today |
|---|---|---|---|
| ImmunityBio (IBRX) | $6.75 | -5.13% | Kept sliding after Monday’s sales-miss plunge, with worries about selling more shares still hanging over it. |
| NextNav (NN) | $8.40 | -5.83% | Fell with small caps ahead of its results, then rose about 8% to 9% after the bell on stronger revenue and a narrower loss. |
| SpaceX (SPCX) | $143.09 | +0.72% | Shook off a 3% drop before the open to finish higher, roughly in step with Tesla (TSLA). |
| Sprott Uranium Miners ETF (URNM) | $41.78 | -4.83% | Gave back much of Monday’s jump as higher yields hit cyclical and energy-related growth names; Cameco (CCJ) closed -3.3%. |
| Roundhill Memory ETF (DRAM) | $40.64 | -2.73% | Memory stocks cooled after Monday’s rebound; Micron (MU) closed -1.1%. |
| Galaxy Digital (GLXY) | $14.11 | -2.76% | Slipped as bitcoin fell about 1.5% over 24 hours and higher yields hurt speculative names. |
Predictions vs Reality — 7/11 hits, 1 partial, 3 misses
Graded against Nov 9 closes. Sectors are ranked by SPDR sector ETF day change.
| Prediction | Our call | Actual | Result | Why |
|---|---|---|---|---|
| S&P 500 close vs Nov 9 close 7,549.94 | lower, 7,440–7,520 | 7,520.93 (-0.38%) | PARTIAL | Right direction; a late bounce left the close less than a point above our range. |
| 10-year yield close vs 4.864% prior | higher | 4.983% (vs 4.864%) | HIT | The hot CPI and Waller’s half-point talk pushed the 10-year to almost 5%. |
| VIX close vs 19.92 prior | higher | 19.46 (vs 19.92) | MISS | The selloff stayed orderly and the late rebound pulled the VIX lower. |
| Best S&P sector ETF (SPDR XL_) | Health Care (XLV) | Financials (XLF) +0.52%; XLV +0.29% | MISS | Health care held up but banks did better on higher rates. |
| Worst S&P sector ETF (SPDR XL_) | Technology (XLK) | Technology (XLK) -1.15% | HIT | Nvidia’s drop kept tech at the bottom. |
| IBRX close vs $7.11 | lower | 6.75 vs 7.11 (-5.13%) | HIT | Selling continued after Monday’s plunge. |
| NN close vs $8.92 | lower | 8.40 vs 8.92 (-5.83%) | HIT | Small caps were soft ahead of its report. |
| SPCX close vs $142.07 | lower | 143.09 vs 142.07 (+0.72%) | MISS | It recovered from the early drop. |
| URNM close vs $43.90 | lower | 41.78 vs 43.90 (-4.83%) | HIT | Higher yields hit the group. |
| DRAM close vs $41.78 | lower | 40.64 vs 41.78 (-2.73%) | HIT | Memory gave back part of Monday’s bounce. |
| GLXY close vs $14.51 | lower | 14.11 vs 14.51 (-2.76%) | HIT | Bitcoin’s dip weighed on it. |
We read the CPI reaction well: lower stocks, higher yields, tech at the bottom and five of six watchlist names lower. We missed on the VIX, which drifted down instead of up, on financials beating health care for the top spot, and on SpaceX’s comeback. Running scorecard: 131 hits + 3 partial across 191 graded calls = 132.5/191 (69.4%).
Look ahead — Wednesday, Nov 11
Stocks trade on Veterans Day, but the bond market is closed, so yields get a pause after today’s jump. S&P futures were at 7,555 late this afternoon, and CoreWeave’s beat could help the battered AI-infrastructure names. With no bond trading and little data, the day should come down to Nvidia and the AI trade. Bull (30%): CoreWeave’s beat sparks an AI bounce and the S&P regains 7,560. Base (45%): a quiet, choppy session between 7,480 and 7,560. Bear (25%): more Nvidia selling drags the S&P below 7,480. Wick's pick: Base.
What to watch
- U.S. bond market closed for Veterans Day on Nov 11; stocks are open.
- October PPI at 8:30 AM ET on Nov 13.
 .ics

- FOMC minutes at 2:00 PM ET on Nov 18.
- FOMC rate decision at 2:00 PM ET on Dec 9.
Wick's take: The market just priced in a December hike and stocks only lost 0.4%, which says investors have mostly made peace with higher rates. The bigger worry is the 10-year sitting right at 5%, a level that has tripped up stocks before, and an AI trade that now depends on Nvidia steadying. We’d stay balanced into Friday’s producer-price report and let the bond market show its hand first.
Market data and opinions by Wick. This post is informational only and is not financial advice. Prices may differ slightly between data vendors; predictions are tracked and scored openly.
Add all 1 events to calendar (.ics) Times are ET. Each event has a 1-day reminder. Estimated dates are marked.