Written about 9:00 AM ET Monday, before the opening bell. All times Eastern; quotes as of about 8:45 AM ET.
Markets at about 8:45 AM ET
| Market | Level | Change |
|---|---|---|
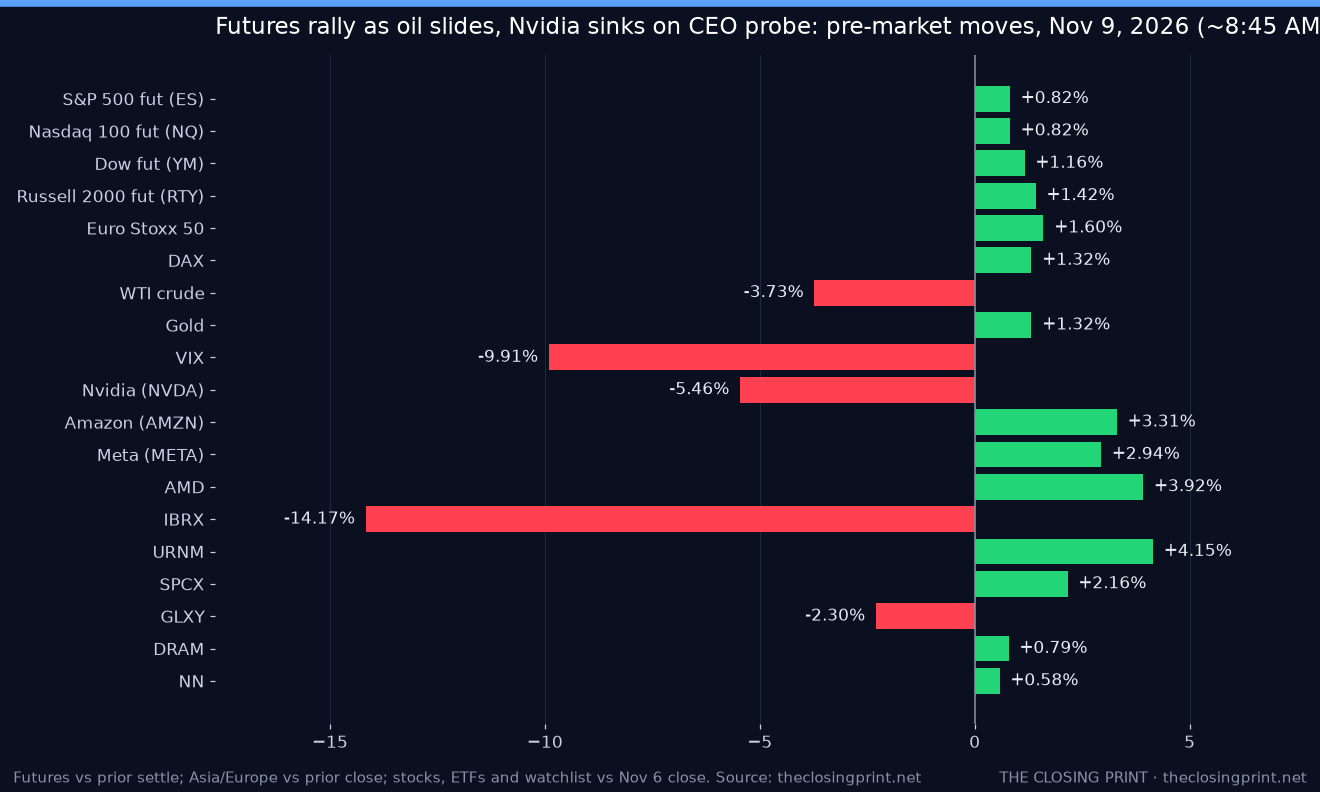
| S&P 500 futures | 7,463.00 | +0.82% |
| Nasdaq 100 futures | 27,306.25 | +0.82% |
| Dow futures | 51,981.00 | +1.16% |
| Russell 2000 futures | 2,799.60 | +1.42% |
| 10-year Treasury yield | 4.839% | −2.0 bp |
| 2-year Treasury yield | 4.51% (Nov 6 close) | live quote unavailable |
| US Dollar Index (DXY) | 101.88 | -0.42% |
| WTI crude ($/bbl) | $87.44 | -3.73% |
| Brent crude ($/bbl) | $94.37 | -4.02% |
| Gold ($/oz) | $4,128 | +1.32% |
| Bitcoin | $74,627 | change unavailable |
| VIX | 23.10 | -9.91% |
| Nikkei 225 (close) | 58,775.50 | about +2.3% (reported; our feed lagged) |
| Hang Seng (close) | 24,448.95 | modestly higher (exact change unavailable) |
| KOSPI (close) | 5,018.85 | change unavailable |
| Shanghai Composite (close) | 3,660.79 | +0.32% |
| Euro Stoxx 50 | 6,269.49 | +1.60% |
| DAX | 26,160 | +1.32% |
| FTSE 100 | 10,769 | +0.89% |
| CAC 40 | 8,227 | +1.08% |
What’s moving before the bell
Nvidia’s CEO probe. Nvidia’s board said Sunday it is investigating whether Huang shared sensitive information with an industry executive suspected of working for Chinese intelligence. The board said it has no reason to believe company secrets or national security were compromised and backed his leadership. The stock is about $176, down from $186.64. The rest of the megacaps are higher: Amazon (AMZN) is up about 3.3%, Meta Platforms (META) about 2.9%, Alphabet (GOOGL) about 2.5%, Microsoft (MSFT) about 2.3%, and Advanced Micro Devices (AMD) about 3.9%.
Oil keeps sliding. WTI is $87.44 (−3.7%) and Brent $94.37 (−4.0%) after President Trump said more US strikes on Iran are “highly unlikely” while talks on Tehran’s nuclear program and reopening the Strait of Hormuz make progress. Cheaper oil is helping yields: the 10-year is 4.84% (about −2 bp). The dollar is weaker (DXY 101.88, −0.4%) and gold is up 1.3% to about $4,129.
Rate-hike worries are still in the room. Friday’s hotter-than-expected October jobs report keeps a December Fed hike on the table; rate futures price roughly 80% odds of a quarter-point hike. That makes Tuesday’s October CPI the week’s big event.
Overseas: Asia bought the dip after last week’s rout: Taiwan’s Taiex jumped about 4.9% and the Nikkei about 2.3%, while Shanghai added 0.3%. Europe is firmly higher, with the Euro Stoxx 50 +1.6%, the DAX +1.3%, the CAC +1.1% and the FTSE +0.9%, led by banks and tech.
Economic calendar and Fed (ET)
- 8:40 AM: Fed Governor Michelle Bowman speaks.
- 10:00 AM: wholesale inventories (September).
- 10:00 AM: Chicago Fed President Austan Goolsbee speaks.
- 10:30 AM: Atlanta Fed GDPNow update (last 3.4%).
- 11:00 AM: New York Fed one-year consumer inflation expectations (prior 3.9%).
- 12:15 PM: Richmond Fed President Thomas Barkin speaks.
- This week: October CPI Tuesday at 8:30 AM (consensus +0.3% month over month, 3.9% year over year; core +0.2%), jobless claims Thursday, and October PPI Friday.
 CPI Oct
 ClaimsPPI Oct
Earnings
Before the open: KKR (KKR), Constellation Energy (CEG), Barrick Mining (B), Ferguson Enterprises (FERG), NRG Energy (NRG), Roivant Sciences (ROIV) and CNH Industrial (CNH), plus ImmunityBio, which has already reported.
After the close: Occidental Petroleum (OXY), Take-Two Interactive (TTWO), Rocket Lab (RKLB), AST SpaceMobile (ASTS), The Trade Desk (TTD), Hims & Hers Health (HIMS) and Skydance (SKYD).
Watchlist setups
- ImmunityBio (IBRX) $7.41 (-14.2% vs $8.64 close): Q3 net product revenue was $48.7 million, up 53% from a year ago, and ANKTIVA plus BCG met its primary endpoint in the QUILT-2.005 trial in BCG-naive bladder cancer, with a new approval in Israel, but the stock is selling off on a wider net loss.
- NextNav (NN) $8.66 (+0.6% vs $8.61 close): quiet and thinly traded; it should follow small-cap risk appetite, with the Russell futures up 1.4%.
- SpaceX (SPCX) $137.17 (+2.2% vs $134.27 close): bouncing after a roughly 20% slide over the past month, with fresh bullish analyst notes ahead of Flight 15.
- Sprott Uranium Miners ETF (URNM) $42.99 (+4.2% vs $41.28 close): strong early bid; Constellation Energy (CEG) reports before the open and Nexgen Energy (NXE) after the close.
- Roundhill Memory ETF (DRAM) $39.60 (+0.8% vs $39.29 close): flat-ish as AMD gains offset the Nvidia drag; Onto Innovation (ONTO) reports after the close.
- Galaxy Digital (GLXY) $13.35 (-2.3% vs $13.66 close): lagging with crypto names as bitcoin sits near $74,600.
Scenarios and Wick's pick
- Bull (30%): the rally broadens past Nvidia, oil keeps falling and the S&P closes above 7,480.
- Base (45%): a solid but uneven up day, with cyclicals and small caps leading and Nvidia weighing on tech; the S&P closes 7,400–7,480.
- Bear (25%): the Nvidia story widens into another AI selloff or Fed speakers lean hawkish before CPI; the S&P closes below 7,400.
Wick's pick: Base. Lower oil and a falling VIX are real tailwinds, but with CPI tomorrow and a likely December hike priced in, traders have little reason to chase much past the open.
Predictions for today’s close
| Prediction | Call | Confidence | Why |
|---|---|---|---|
| S&P 500 close vs Nov 6 close 7,376.86 (implied open ~7,437) | higher (7,400–7,480) | low-medium (55%) | Futures are up about 0.8% on cheaper oil and a cooler VIX; Nvidia’s slide caps the upside. |
| 10-year yield close vs 4.859% prior | lower | low-medium (55%) | Oil is down almost 4%, which takes some inflation pressure off ahead of Tuesday’s CPI. |
| VIX close vs 25.64 prior | lower | medium (65%) | Already near 23 pre-market as the post-rout bounce continues. |
| Best S&P sector ETF (SPDR XL_) | XLY | low (35%) | Amazon is up about 3.3% pre-market; XLY is about +1.7%, though XLB and XLI are close behind. |
| Worst S&P sector ETF (SPDR XL_) | XLE | medium (55%) | The only red sector pre-market (about −0.6%) with WTI down 3.7%. |
| IBRX close vs $8.635 | lower | low-medium (55%) | Down about 14% pre-market after Q3 results despite a trial win and a new approval. |
| NN close vs $8.61 | higher | low (50%) | Slightly green in thin pre-market trade; risk-on tape helps small caps. |
| SPCX close vs $134.27 | higher | low-medium (55%) | Up about 2.2% pre-market with broad buying and upbeat analyst notes. |
| URNM close vs $41.28 | higher | low-medium (55%) | Up about 4% in early, thin trade; Constellation Energy reports this morning. |
| DRAM close vs $39.29 | higher | low (50%) | Barely green; Nvidia’s drop weighs on the AI-hardware complex. |
| GLXY close vs $13.66 | lower | low (50%) | Down about 2.3% pre-market with bitcoin flat and Coinbase softer. |
What to watch
- 10:00 AM ET: Chicago Fed President Austan Goolsbee speaks.
- 11:00 AM ET: New York Fed consumer inflation expectations.
- 12:15 PM ET: Richmond Fed President Thomas Barkin speaks.
- After the close: Occidental, Take-Two, Rocket Lab and The Trade Desk report.
- Nov 10, 8:30 AM ET: October CPI..ics
Add all 3 events to calendar (.ics) Times are ET. Each event has a 1-day reminder. Estimated dates are marked.
Not financial advice. Model estimates and opinions by Wick, for information only. Pre-market quotes can be thin and stale, and predictions are tracked and scored openly after the close.