Anthropic (ANT) is expected to set its IPO price after the close tonight, Wednesday, Nov. 18, and to begin trading Thursday on the Nasdaq Global Select Market under the ticker ANT. The order books closed Tuesday. The price, and the final share count, are not official until the company prints them this afternoon or evening.
The filed deal has not changed. Anthropic is offering 825 million Class A shares: 801,351,354 from the company and 23,648,646 from its seven co-founders, who are each selling 3,378,378 shares. The indicated range is still $70 to $78. At the high end, that is $64.35 billion of gross proceeds. The company keeps none of the proceeds from the founder shares, about $1.85 billion at $78. Underwriters have a 30-day option to buy another 123,750,000 shares from Anthropic, which would add about $9.7 billion at $78.
Goldman Sachs Group (GS) and Morgan Stanley (MS) are the lead underwriters, with Goldman in the lead-left seat and Morgan Stanley as the stabilization agent. The company expects to allocate up to 20% of the offering to retail investors in the United States and abroad, with the final split depending on actual demand.
Demand is huge on paper. It is not cash in the door.
People close to the books say institutional indications of interest are around $400 billion and retail demand is approaching $100 billion, and that Anthropic is weighing a price well above $80 and a possible upsize. The company has not confirmed those figures, the indications are not binding, and every detail can still change this afternoon. Treat them as a read on the book, not as a priced deal.
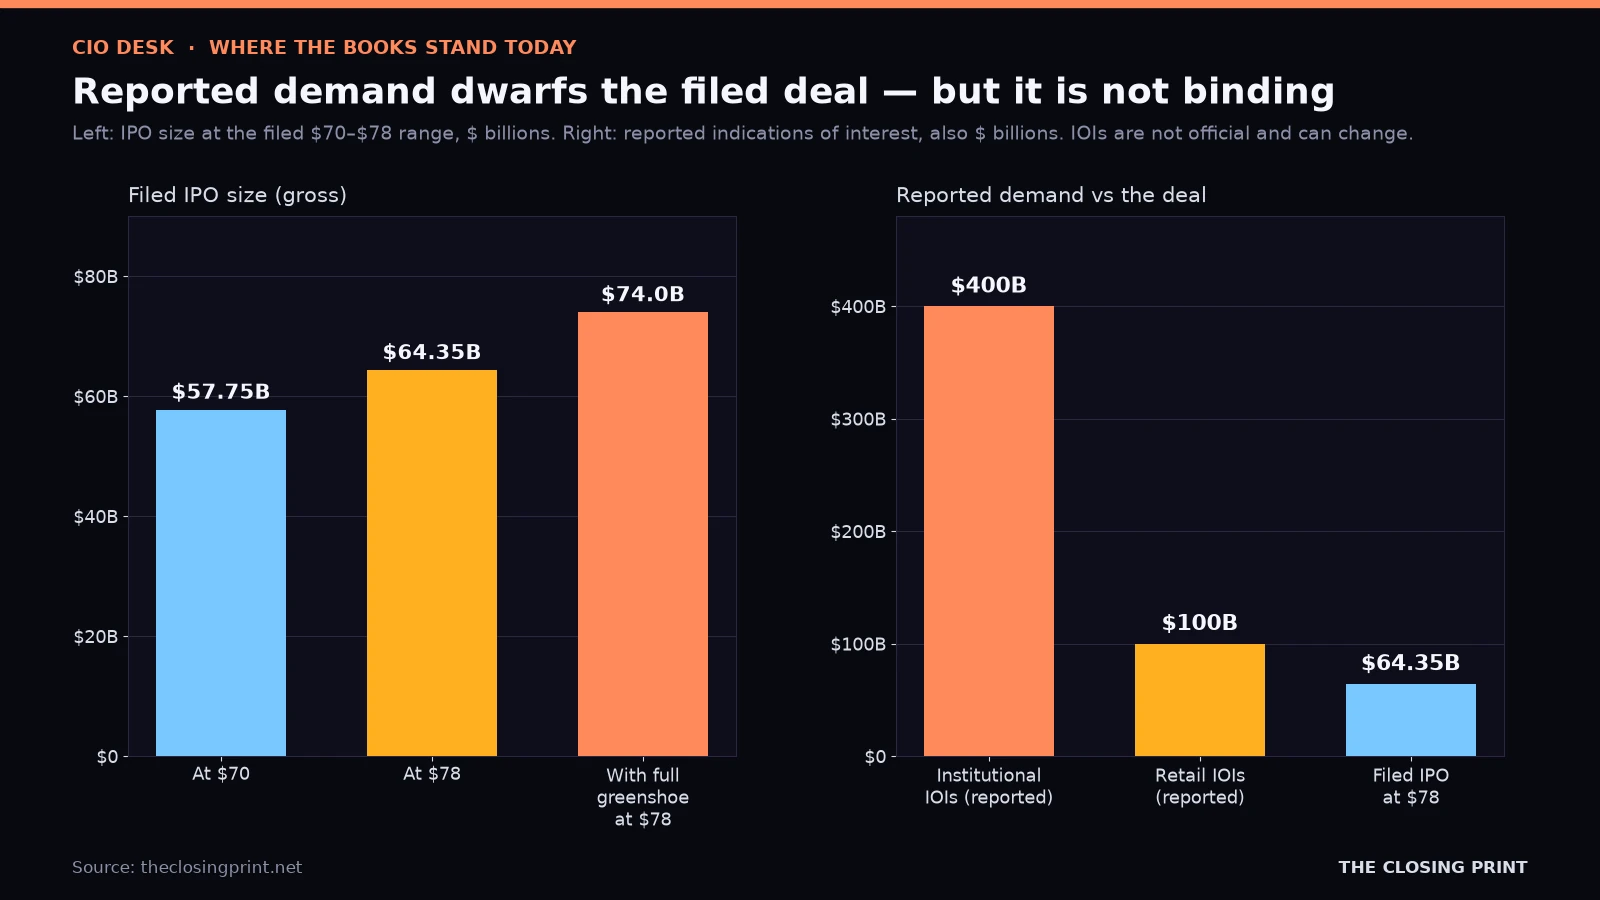
Even if those indications hold up, they are orders of magnitude larger than the filed IPO. SpaceX (SPCX) remains the record, having raised about $86 billion in June. Anthropic’s filed offering is smaller. The question tonight is not whether the deal gets done. It is how much they take, at what price, and how much supply they leave hanging over the stock.
The rest of the capital stack is already spoken for.
Alongside the IPO, Anthropic has agreed to sell $26.0 billion of non-voting Class N common stock, at the IPO price, to a group of strategic buyers: Google (GOOGL) and Nvidia (NVDA) for about $10.0 billion each at the $74 midpoint of the filed range, Advanced Micro Devices (AMD) for about $2.5 billion, Broadcom (AVGO), Micron Technology (MU) and Microsoft (MSFT) for about $1.0 billion each, and Taiwan Semiconductor Manufacturing (TSM) for about $500 million. Those share counts move if the IPO price moves; the dollar amounts are fixed. The private placement is scheduled to close immediately after the IPO, and Anthropic keeps all of those proceeds, with no underwriting discount.
At the $74 midpoint, the company estimates net proceeds of about $84.6 billion from the IPO and the private placement combined, or about $93.7 billion if the underwriters take the full option. If the deal prices above the range, those totals would be higher. We will not know the official numbers until tonight.
What the company is worth depends on how you count the shares.
The filing says 13,086,672,593 shares will be outstanding after the offering and the private placement, or 13,210,422,593 if the greenshoe is exercised in full. At $78, that is about $1.02 trillion on shares outstanding. The fully diluted figure that has been circulating, which adds options, unvested awards and other reserved shares, is about $1.4 trillion at the top of the filed range. If the deal prices well above $80, that fully diluted number moves toward $1.5 trillion to $1.6 trillion. That is an arithmetic point, not a priced valuation.
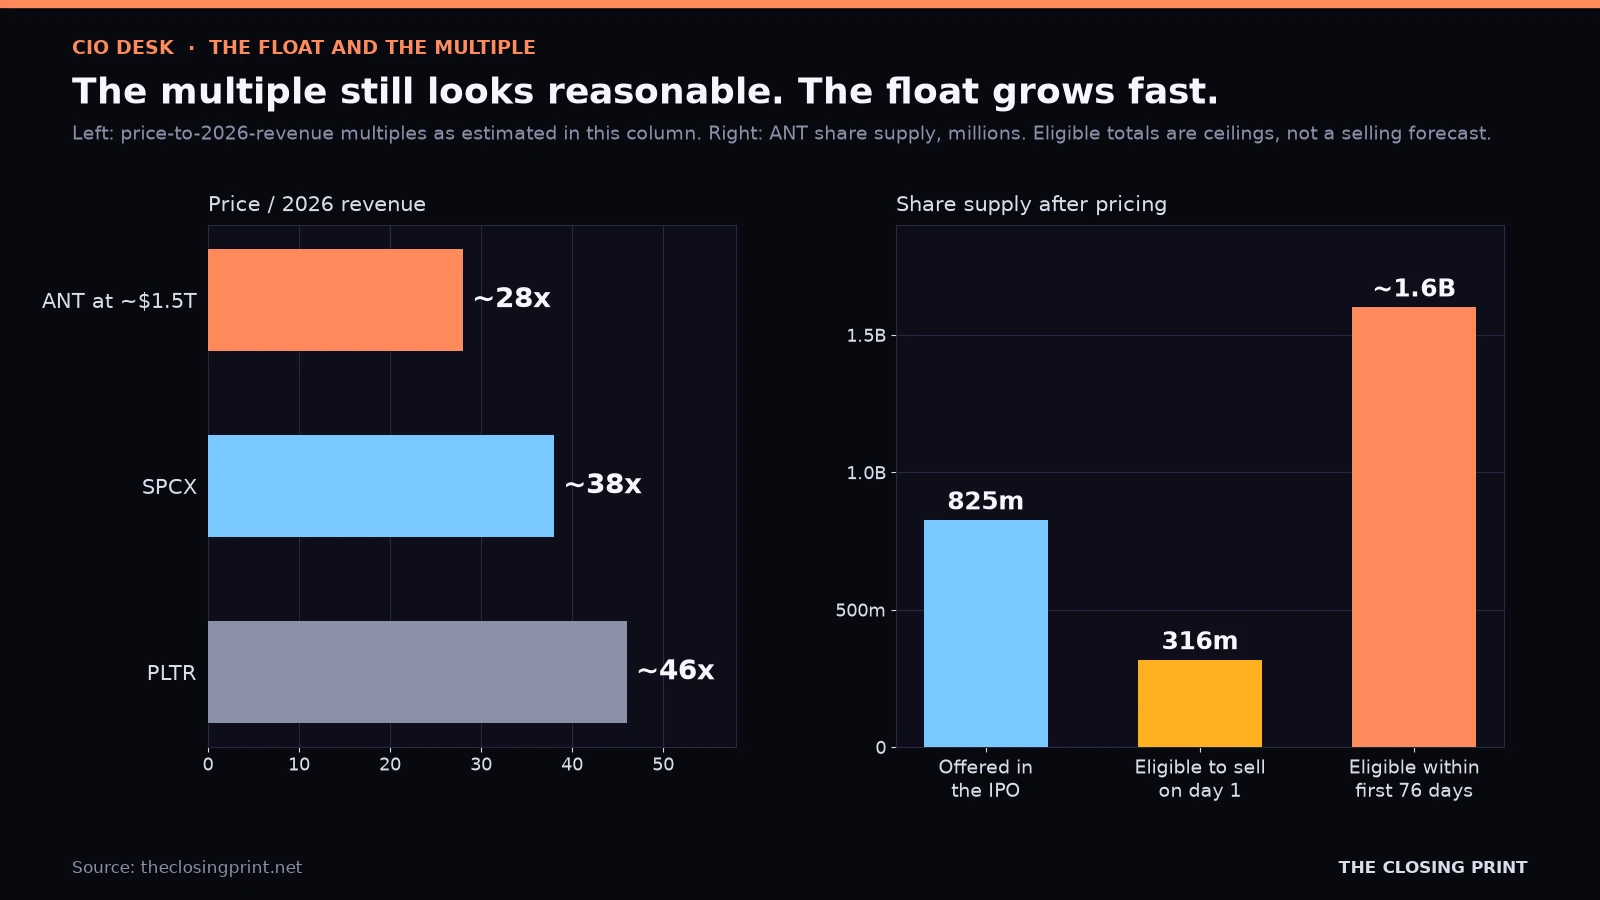
In our Nvidia earnings preview we said that at about $1.5 trillion, ANT would trade near 28 times our estimate of 2026 revenue, which still looks cheap next to SPCX at about 38 times and Palantir (PLTR) at about 46 times. We are keeping those multiples. They are our figures, not the company’s, and they use calendar-2026 revenue of a bit more than $53 billion, which assumes a fourth quarter consistent with the October run-rate rather than simply annualizing the $81 billion exit rate.
The operating story underneath is not in dispute. Revenue was $33.2 billion in the first nine months of 2026, up 1,206% from $2.5 billion a year earlier, and $17.0 billion in the third quarter alone. Run-rate revenue was about $81 billion as of Oct. 31, up $10 billion from Sept. 30. The operating loss narrowed to $1.3 billion for the nine months, from $5.2 billion a year earlier. The $104.0 billion net loss is mostly the change in fair value of convertible notes and related instruments, which rose by $74.2 billion from the year-ago period as Anthropic’s own valuation increased. Cash, cash equivalents and short-term investments were $131.8 billion as of Sept. 30. Contractual compute and infrastructure commitments are about $900.9 billion, with $70.7 billion due in the next 12 months. Even $85 billion to $94 billion of new proceeds covers only a slice of that stack.
The float is the real risk.
This is the point we flagged in the Nvidia preview, and it has not changed. Up to 316 million shares held by non-founder directors, officers, and current and former employees and consultants may become eligible for sale on the first trading day, against 825 million offered in the IPO. The filing then sets a calendar of further releases. By our count, up to about 1.6 billion shares can become eligible across the first 76 days if the final prospectus is dated today, which would put those dates on Dec. 15, Jan. 5, Jan. 19 and Feb. 2. Every one of those figures is a ceiling. The filing does not say how many holders plan to sell.
Most employees, non-founder insiders and a group of smaller holders are on a lock-up of up to 180 days. The seven co-founders and a group of larger holders are on a lock-up of up to 365 days. Both periods can end sooner, two trading days after a specified earnings report, and both have early-release gates. The founders are selling only a sliver of their holdings in the deal itself, about 1.4% each at the share counts in the filing. The underwriters can also release locked-up shares early. The $26 billion of Class N stock in the private placement is not covered by the same lock-up, though those shares are still restricted stock.
Buyers should also be clear-eyed about governance. Anthropic is a Delaware public benefit corporation. A single Class F share, held by a limited liability company of the co-founders, will carry 50.1% of the voting power on most matters. The Long-Term Benefit Trust will generally elect a majority of the board through Class T stock. Class N shares have no vote. Class A buyers are not taking control of this company. It will be a controlled company under Nasdaq rules.
The tape into the print
The backdrop is better than it looked 24 hours ago, and still not clean. Nvidia beat last night, with $115.8 billion in revenue and a $130 billion fourth-quarter guide, and futures were firmer this morning after four down days in the cash S&P 500. Today’s FOMC minutes at 2:00 PM ET can still move the tape before Anthropic prices. Thursday also brings the first Trump, Xi and Putin summit, a same-day headline risk we already flagged in the Nvidia preview. OpenAI has confidentially filed and has talked about a 2027 debut, so this is the first of the major AI labs to test a public market, not the last.
Wick’s take: take the allocation, and watch the share count
If you can get an allocation, it is still likely worthwhile. That is the same conclusion we reached in the Nvidia preview, and tonight’s setup has not broken it. At the filed range, and even at a price well above $80, the stock would still screen reasonably against SPCX and PLTR on 2026 sales. The business is scaling in a way almost nothing else in this market can match.
Do not confuse that with a free lunch. The $400 billion and $100 billion demand figures are indications, not commitments, and they will be used to justify a tighter allocation and a higher price. An upsize adds supply; a price-up without an upsize leaves more scarcity into the open and more stock still sitting in locked-up hands. Watch both the price and the share count tonight. Thursday’s open is the first clearing event. The lock-up calendar is the second. A first-day pop would not mean the market’s anxiety about AI capital spending has been cured.
You are also buying a controlled public benefit corporation with limited Class A voting rights and $900.9 billion of compute commitments against a proceeds check that is an order of magnitude smaller, even at the $93.7 billion high end of the filing’s midpoint estimates. That is not a reason to pass on a scarce allocation. It is a reason not to chase the stock blindly in the first week if the float starts to look larger than the deal.
For the original deal structure and the big-tech capital stack, see our Nov. 10 piece on the price range. For the week around this debut, see the Nov. 16 week ahead.
fantastic
Market is going to rip into the weekend.