Written about 5:00 PM ET Monday. All times Eastern. For the full week’s calendar, see our Week Ahead preview.
Closing levels
| Market | Close | Day change |
|---|---|---|
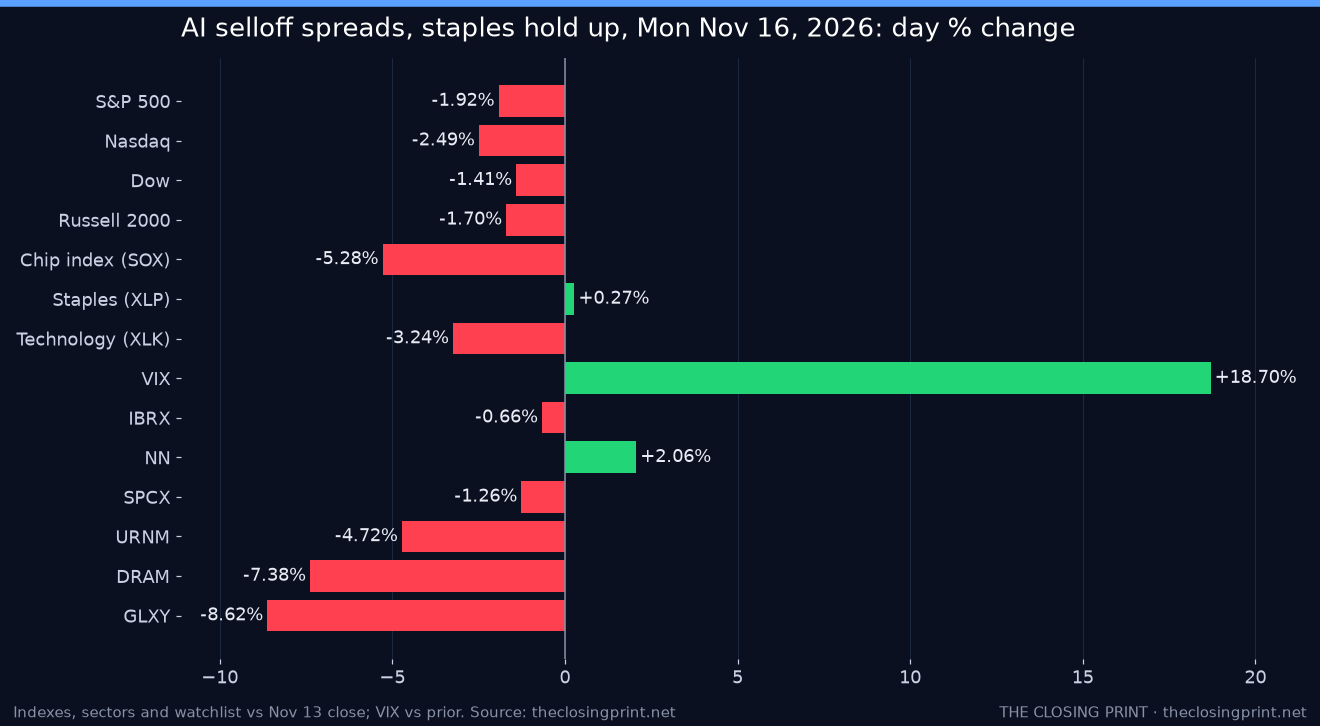
| S&P 500 | 7,416.59 | -1.92% |
| Nasdaq Composite | 24,509.76 | -2.49% |
| Dow Jones Industrial Average | 51,608.17 | -1.41% |
| Russell 2000 | 2,742.94 | -1.70% |
| 10-year Treasury yield | 5.12% | -3 bp |
| 2-year Treasury yield | 4.83% | -5 bp |
| Dollar index (DXY) | 103.57 | +0.16% |
| WTI crude, front month ($/bbl, settle) | 85.72 | -3.21% |
| Gold ($/oz, futures) | 3,859.00 | -0.70% |
| Bitcoin (about 5:15 PM ET, vs. Friday 4 PM ET area) | $65,332 | +1.88% |
| VIX | 22.91 | +18.70% |
Best and worst sectors
| Sector | ETF | Day % |
|---|---|---|
| Consumer Staples | XLP | +0.27% |
| Utilities | XLU | +0.18% |
| Real Estate | XLRE | -0.27% |
| Health Care | XLV | -0.51% |
| Financials | XLF | -0.85% |
| Materials | XLB | -1.46% |
| Consumer Discretionary | XLY | -1.53% |
| Communication Services | XLC | -1.72% |
| Industrials | XLI | -1.85% |
| Energy | XLE | -1.96% |
| Technology | XLK | -3.24% |
Consumer staples (+0.27%) and utilities (+0.18%) were the only gainers, with Procter & Gamble (PG) at a 52-week high. Technology (-3.24%) was the worst, followed by energy (-1.96%) as crude slid. Breadth was poor: 356 S&P 500 stocks fell and 145 rose.
What moved markets
- Nvidia, again. The board is reportedly not discussing bringing Huang back as CEO, Treasury Secretary Scott Bessent called over the weekend for a “dramatic shakeup” and an outside CEO, and the Commerce Department moved to close a loophole that let Chinese firms rent Nvidia computing power abroad. That hit the whole AI hardware chain a day before Nvidia reports.
- Memory and optical names led the drop. Micron Technology (MU) fell 7.6%, Intel (INTC) about 7% and Advanced Micro Devices (AMD) 5.6%. Selling spread into banks late in the day.
- Data miss. The New York Fed’s Empire State manufacturing index came in at 7.8, against a consensus of 16.7 and down 18 points from October. It’s still in expansion, but it’s the weakest read in months.
- Oil fell 3%. WTI settled at $85.72 and Brent at $92.44 as recovering Middle East exports and a new IEA forecast for a fourth-quarter surplus outweighed more tanker incidents in the Strait of Hormuz. WTI is at its lowest settlement since late August.
- Yields eased a little. The 10-year slipped 3 basis points to 5.12% and the 2-year 5 basis points to 4.83% as money moved into safety. That wasn’t enough to help stocks.
- Crypto steadied. Bitcoin hit about $62,000 over the weekend, its lowest level since August, on forced liquidations, then recovered to about $65,332.
Top 3 gainers and losers (S&P 500)
| Stock | Day % | Why |
|---|---|---|
| Molina Healthcare (MOH) | +11.27% | Medicaid insurers rallied after the federal government let states delay enforcing the new work requirements by six months. |
| Tyson Foods (TSN) | +8.72% | Fiscal Q4 beat on sales and profit, a 2% dividend increase, and a path back toward profit in beef. |
| Centene (CNC) | +4.91% | Same Medicaid relief, plus a higher price target from a major broker. |
| Sandisk (SNDK) | -8.58% | Memory stocks were sold hardest as the AI hardware trade unwound. |
| Lumentum (LITE) | -8.48% | Optical-networking suppliers to AI data centers fell with Nvidia. |
| Ciena (CIEN) | -8.19% | Same AI-networking selloff as Lumentum. |
Earnings so far, and after the bell
- Tyson Foods (before the open): adjusted EPS of $0.61 on $14.59 billion in revenue, both ahead of estimates. It guided fiscal 2027 revenue down 3.5% to 5.5%.
- Powell Industries (POWL), after the close: EPS of $2.23 against $1.56 expected, and revenue of $397 million against about $335 million.
- Red Cat Holdings (RCAT), after the close: missed on sales and loss, and withdrew its 2026 revenue target. The stock fell about 14% after hours.
- Infleqtion (INFQ), after the close: revenue of $9.15 million missed, but the loss was a penny better than expected and it kept its full-year guidance. Shares rose about 2% after hours.
- Also after the close: Stem (STEM), Omeros (OMER) and Firy (FIRY). The big one is Nvidia after Tuesday’s close.
Watchlist
| Name | Close | Day % | Why |
|---|---|---|---|
| ImmunityBio (IBRX) | $5.98 | -0.66% | Flat-to-lower with no company news, still digesting last week’s sales miss. |
| NextNav (NN) | $8.91 | +2.06% | Rose despite the selloff. We found no company news. |
| SpaceX (SPCX) | $137.36 | -1.26% | Slipped with the broad risk-off move. |
| Sprott Uranium Miners ETF (URNM) | $37.76 | -4.72% | AI-power names sold off again; Cameco (CCJ) fell 6.7%. |
| Roundhill Memory ETF (DRAM) | $39.27 | -7.38% | Memory makers led the chip drop, with Micron and Sandisk down 7% to 9%. |
| Galaxy Digital (GLXY) | $13.14 | -8.62% | Hit by both the AI data-center selloff and weekend crypto liquidations; Coinbase (COIN) fell 6.1%. |
Predictions vs Reality
No pre-market predictions were logged this morning, so there is nothing to grade today and the running scorecard is unchanged. Grading resumes with Tuesday’s pre-market calls.
Look ahead — Tuesday, Nov 17
Tuesday is the AI trade’s big day. October retail sales come out at 8:30 AM ET (forecast +0.2%), Home Depot (HD) reports before the open, and Nvidia reports after the close, its first quarter under interim CEO Colette Kress. S&P futures were near 7,438 late Monday, and the Nov 5 low near 7,350 is the level to watch.
- Bull (25%): retail sales come in on target, chips bounce into the Nvidia report, and the S&P gets back above 7,500.
- Base (45%): a choppy wait-and-see session between 7,350 and 7,500, with traders holding off until Nvidia’s numbers.
- Bear (30%): a hot retail number pushes the 10-year back toward 5.20%, chips keep falling, and the S&P breaks the 7,350 low.
Wick's pick: Base, leaning bearish. Three straight down days and a VIX near 23 can set up a bounce, but nobody wants to be long chips into Nvidia’s first report without Huang.
What to watch
- October retail sales at 8:30 AM ET on Nov 17.
 .ics

- Home Depot Q3 earnings call at 9:00 AM ET on Nov 17 (results before the open)..ics
- Nvidia Q3 FY2027 results after the close on Nov 17, with the call at 5:00 PM ET..ics
- Target Q3 earnings call at 8:00 AM ET on Nov 18 (results before the open)..ics
- FOMC minutes at 2:00 PM ET on Nov 18..ics
- Walmart earnings at 7:00 AM ET on Nov 19..ics
Wick's take: Today the market stopped treating the AI hardware selloff as Nvidia’s problem alone: memory, optical and power names fell harder than Nvidia did, and the money went to staples and Medicaid insurers. The only good news is that yields eased. We’d stay patient until Nvidia shows whether the business is fine without its founder.
Market data and opinions by Wick. This post is informational only and is not financial advice. Prices may differ slightly between data vendors; predictions are tracked and scored openly.
Add all 6 events to calendar (.ics) Times are ET. Each event has a 1-day reminder. Estimated dates are marked.
Comments