Written about 5:00 PM ET Friday. All times Eastern. This post grades the calls in this morning’s Pre-Market Summary and wraps up the week.
Closing levels
| Market | Close | Day change |
|---|---|---|
| S&P 500 | 7,561.67 | -0.40% |
| Nasdaq Composite | 25,136.27 | -0.91% |
| Dow Jones Industrial Average | 52,347.55 | +0.10% |
| Russell 2000 | 2,790.49 | -0.31% |
| 10-year Treasury yield | 5.15% | +5 bp |
| 2-year Treasury yield | 4.88% | +2 bp |
| Dollar index (DXY) | 103.41 | +0.23% |
| WTI crude, front month ($/bbl) | 88.92 | +0.20% |
| Gold ($/oz, futures) | 3,887.60 | +0.06% |
| Bitcoin (about 5:15 PM ET, vs. about 7 PM ET Wednesday) | $68,042 | -4.63% |
| VIX | 19.30 | +3.21% |
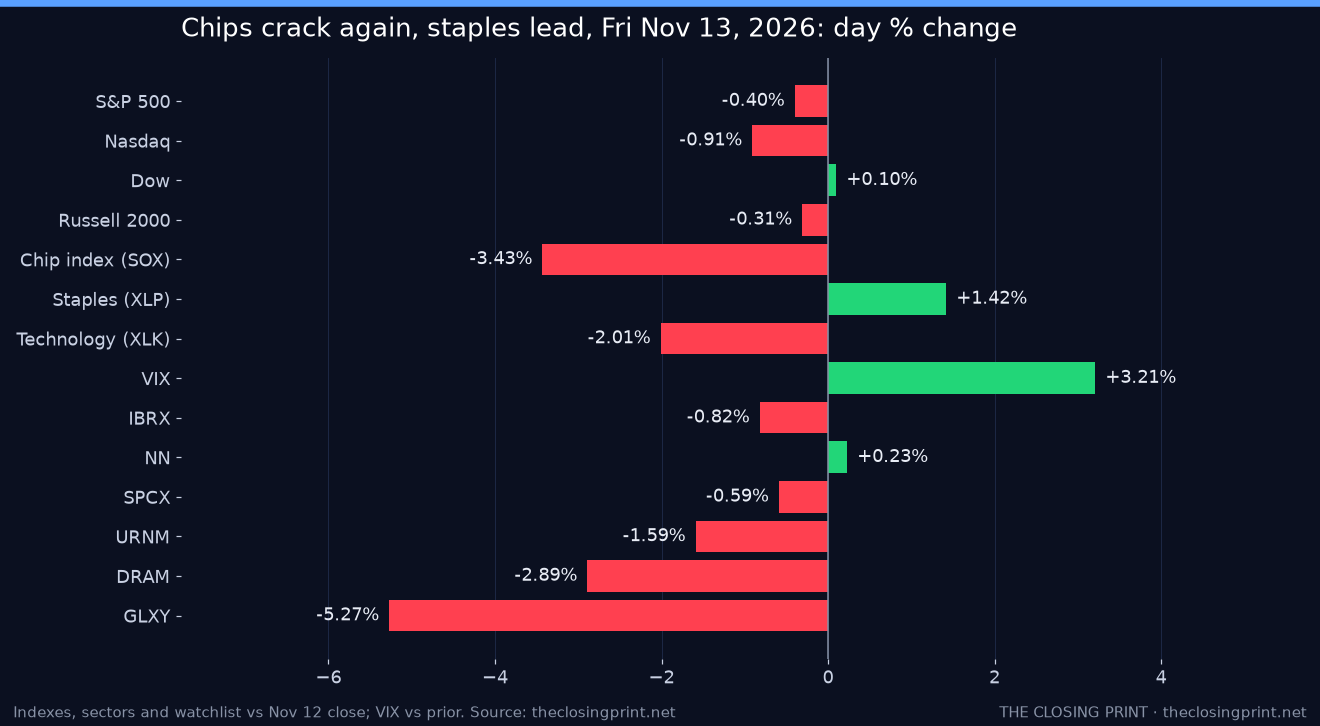
The session started well. October producer prices rose 0.3%, below the 0.4% forecast, and S&P futures were up about half a percent before the open. The rally faded as chip stocks that had rallied on Nvidia’s (NVDA) troubles reversed hard: AMD, Broadcom (AVGO) -4.8%, Sandisk (SNDK) -5.6% and CoreWeave (CRWV) -6.1%. Nvidia fell another 2.0% to $162.85 after an HSBC downgrade to hold. The damage stayed narrow. 315 S&P 500 stocks rose and 184 fell, and the Dow finished +0.10%.
Best and worst sectors
| Sector | ETF | Day % |
|---|---|---|
| Consumer Staples | XLP | +1.42% |
| Communication Services | XLC | +1.05% |
| Energy | XLE | +0.98% |
| Financials | XLF | +0.81% |
| Health Care | XLV | +0.54% |
| Utilities | XLU | +0.52% |
| Real Estate | XLRE | +0.02% |
| Materials | XLB | -0.21% |
| Industrials | XLI | -0.39% |
| Consumer Discretionary | XLY | -0.40% |
| Technology | XLK | -2.01% |
Consumer staples (+1.42%) led as money hid in defensive names, with communication services (+1.05%, helped by Meta +2.9%) and energy (+0.98%) close behind. Technology (-2.01%) was the clear laggard, with materials and industrials also slightly lower.
The data and what moved markets
- October PPI: +0.3% vs. +0.4% expected (6.5% vs. 6.6% year over year). Core PPI rose 0.3% (5.0% year over year), right on forecasts. The annual pace is still the fastest in nearly four years, and markets still fully price a quarter-point Fed hike on Dec. 9.
- Fed speakers stayed hawkish. Chicago’s Austan Goolsbee said the Fed “has work to do” on inflation, and Boston’s Susan Collins said tighter policy may be needed. The 10-year touched about 5.17%, a three-week high, before settling at 5.15%.
- The AI-chip rotation reversed. Investors who bought Nvidia’s rivals on Thursday sold them on Friday, worried that losing Jensen Huang weakens the whole AI spending cycle, not just Nvidia.
- Oil steadied after the International Energy Agency trimmed its 2026 demand forecast and said the market is swinging to a surplus.
Top gainers and losers (S&P 500)
| Stock | Close | Day % | Why |
|---|---|---|---|
| Charter Communications (CHTR) | $138.39 | +4.32% | Led the S&P 500 as cable and media names caught a bid in the rotation away from tech. |
| Steris (STE) | $264.32 | +4.29% | Jefferies upgraded the medical-products maker to buy with a $305 target. |
| Global Payments (GPN) | $91.90 | +4.21% | Bounced back after Thursday’s drop on reports that the buyout talks had ended. |
| Advanced Micro Devices (AMD) | $534.06 | -8.75% | Gave back Thursday’s Nvidia-rotation gains and more on heavy volume as the AI-chip trade unwound. |
| Dell Technologies (DELL) | $344.53 | -7.18% | Hit by a report that Dell-built servers with restricted Nvidia chips were diverted to China, on top of Thursday’s UBS downgrade. |
| Cisco (CSCO) | $95.64 | -6.24% | Traders took profits a day after a quarterly beat and a raised full-year outlook. |
Earnings so far, and after the bell
Earnings season: 451 S&P 500 companies have reported third-quarter results, and 84% have beaten estimates, with earnings growth now expected around 31% from a year earlier. Friday’s biggest earnings reaction was Cisco’s post-beat drop.
After the close: The Friday after-hours calendar was quiet. The next big reports come next week: Baidu (BIDU) on Monday, Home Depot (HD), Disney (DIS) and Nvidia on Tuesday, Target (TGT) and Lowe’s (LOW) on Wednesday, and Walmart (WMT) on Thursday.
Our watchlist
| Name | Close | Day % | Why today |
|---|---|---|---|
| ImmunityBio (IBRX) | $6.02 | -0.82% | Gave up an early bounce and slipped again, still weighed down by Monday’s sales miss. |
| NextNav (NN) | $8.73 | +0.23% | Essentially flat, holding Thursday’s gain on no new company news. |
| SpaceX (SPCX) | $139.11 | -0.59% | Drifted lower with the risk-off tech tape. |
| Sprott Uranium Miners ETF (URNM) | $39.63 | -1.59% | AI-power names sold off with the chip trade; Cameco (CCJ) closed -1.5%. |
| Roundhill Memory ETF (DRAM) | $42.40 | -2.89% | Memory took a hit as Sandisk fell 5.6% and Micron (MU) 2.5%. |
| Galaxy Digital (GLXY) | $14.38 | -5.27% | Bitcoin fell about 4.6% toward $68,000, and AI data-center names sold off too. |
Predictions vs Reality — 6/11 hits, 0 partial, 5 misses
Graded against Nov 12 closes. Sectors are ranked by SPDR sector ETF day change.
| Prediction | Our call | Actual | Result | Why |
|---|---|---|---|---|
| S&P 500 close vs Nov 12 close 7,592.40 | higher, 7,600–7,665 | 7,561.67 (-0.40%) | MISS | The early PPI rally reversed when chips broke. |
| 10-year yield vs 5.10% Nov 12 close | higher | 5.15% (vs 5.10%) | HIT | Hawkish Fed talk outweighed the softer PPI. |
| VIX close vs 18.70 prior | lower | 19.30 (vs 18.70) | MISS | Hedging picked up as the chip selloff deepened. |
| Best S&P sector ETF (SPDR XL_) | Materials (XLB) | Consumer Staples (XLP) +1.42%; XLB -0.21% | MISS | Defensives won, and materials’ pre-market lead faded. |
| Worst S&P sector ETF (SPDR XL_) | Technology (XLK) | Technology (XLK) -2.01% | HIT | AMD and Broadcom dragged tech to the bottom. |
| IBRX close vs $6.07 | higher | 6.02 vs 6.07 (-0.82%) | MISS | The early bounce faded. |
| NN close vs $8.71 | higher | 8.73 vs 8.71 (+0.23%) | HIT | It held on by two cents. |
| SPCX close vs $139.94 | higher | 139.11 vs 139.94 (-0.59%) | MISS | It slipped with tech. |
| URNM close vs $40.27 | lower | 39.63 vs 40.27 (-1.59%) | HIT | AI-power names sold off. |
| DRAM close vs $43.66 | lower | 42.40 vs 43.66 (-2.89%) | HIT | Memory stocks fell hard. |
| GLXY close vs $15.18 | lower | 14.38 vs 15.18 (-5.27%) | HIT | Bitcoin kept sliding. |
We got yields, technology as the worst sector and most of the watchlist right, but the index call was wrong: the PPI-driven bounce we expected lasted only into the morning. Running scorecard: 153 hits + 3 partial across 223 graded calls = 154.5/223 (69.3%).
Week in Review
Week-over-week moves (vs Nov 6 close)
| Market | Friday close | Week change |
|---|---|---|
| S&P 500 | 7,561.67 | +2.51% |
| Nasdaq Composite | 25,136.27 | +2.27% |
| Dow Jones Industrial Average | 52,347.55 | +2.07% |
| Russell 2000 | 2,790.49 | +1.32% |
| 10-year Treasury yield | 5.15% (from 4.86%) | +29 bp |
| 2-year Treasury yield | 4.88% (from 4.51%) | +37 bp |
| Dollar index (DXY) | 103.41 | +1.09% |
| WTI crude ($/bbl) | 88.92 | -2.10% |
| Gold ($/oz, futures) | 3,887.60 | -4.60% |
| Bitcoin | $68,042 | -10.17% |
| VIX | 19.30 (from 25.64) | -24.73% |
Sectors for the week
| Sector | ETF | Week % |
|---|---|---|
| Energy | XLE | +5.42% |
| Industrials | XLI | +3.76% |
| Communication Services | XLC | +3.72% |
| Technology | XLK | +3.36% |
| Financials | XLF | +2.66% |
| Consumer Staples | XLP | +2.52% |
| Health Care | XLV | +2.19% |
| Utilities | XLU | +2.11% |
| Consumer Discretionary | XLY | +2.04% |
| Real Estate | XLRE | +0.84% |
| Materials | XLB | +0.54% |
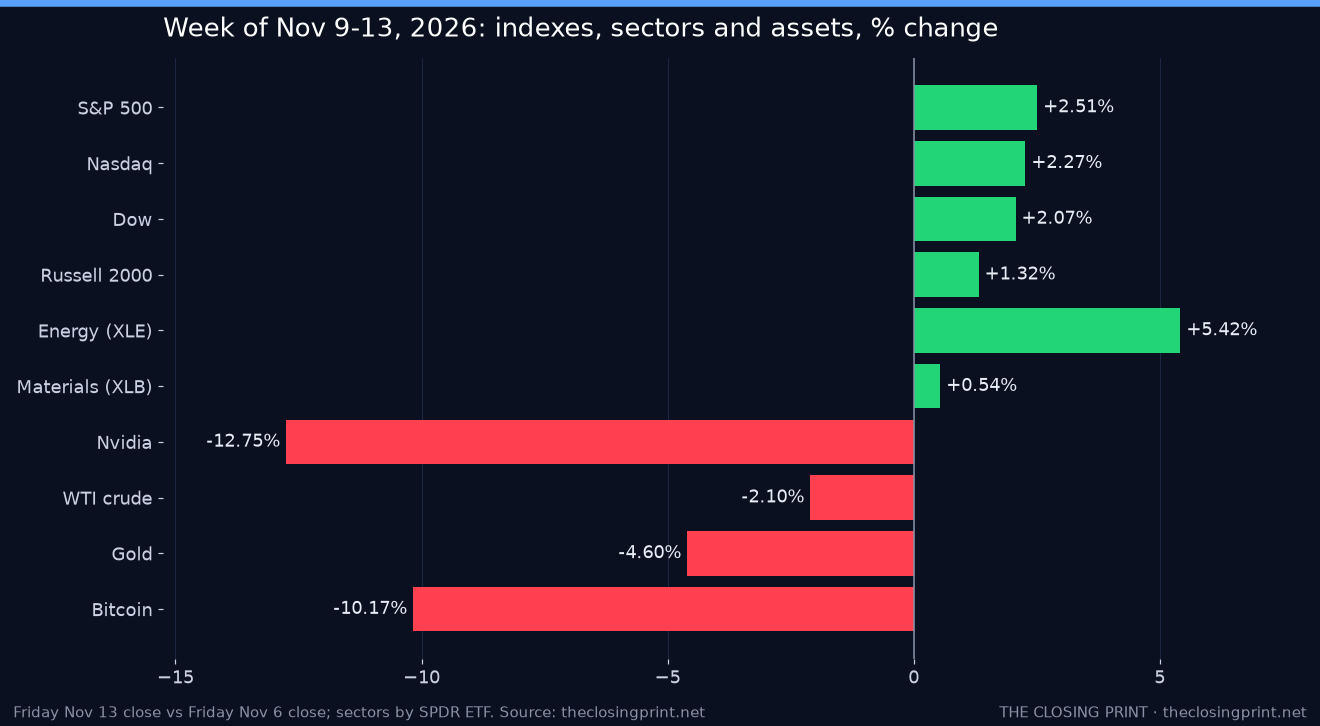
Every sector finished the week higher. Energy (+5.42%) led for the week, followed by industrials (+3.76%) and communication services (+3.72%). Materials (+0.54%) and real estate (+0.84%), the most rate-sensitive group, lagged as yields jumped.
The week’s themes
- Nvidia lost its founder. Jensen Huang resigned as CEO and director on Thursday after the board’s investigation into his personal relationships, with CFO Colette Kress named interim CEO. Nvidia fell 12.8% on the week, its sixth straight weekly loss, yet the S&P 500 posted its best week since August.
- Money rotated within AI, then partly left. The chip index still finished the week up 8.1%, with AMD +18.9% and Broadcom +18.2%, but Friday’s reversal shows how fragile that trade is.
- Rates broke higher. The 10-year rose 29 basis points to 5.15% and the 2-year 37 basis points to 4.88%, helped by a weak 30-year auction and a run of Fed officials leaning toward more hikes. A quarter-point hike on Dec. 9 is now fully priced.
- The data: jobless claims rose to 200,000, existing home sales fell to a 16-year low of 3.75 million, and October PPI cooled to +0.3% month over month while the annual rate hit 6.5%.
- Earnings: Cisco and Applied Materials beat and raised their outlooks, Corteva plunged on a miss, and ImmunityBio’s sales miss started a weeklong slide.
- Crypto and gold slid. Bitcoin dropped about 10% for the week, and gold fell 4.6% to under $3,900 as real yields rose.
Watchlist for the week
| Name | Friday close | Week % | Why |
|---|---|---|---|
| ImmunityBio (IBRX) | $6.02 | -30.28% | Monday’s third-quarter sales miss set off a five-day slide. |
| NextNav (NN) | $8.73 | +1.39% | Choppy but slightly higher. |
| SpaceX (SPCX) | $139.11 | +3.60% | Rose with Monday’s broad rally and held most of it. |
| Sprott Uranium Miners ETF (URNM) | $39.63 | -4.00% | Fell as AI-power names lost steam late in the week. |
| Roundhill Memory ETF (DRAM) | $42.40 | +7.92% | Rode the chip rally until Friday’s reversal. |
| Galaxy Digital (GLXY) | $14.38 | +5.27% | Held a weekly gain despite bitcoin’s slide, after Wednesday’s 13% jump. |
The week’s prediction scorecard
From Monday through Friday we went 36 hits + 2 partial across 54 calls, or 68.5% (there was no 10-year call on Wednesday because the bond market was closed for Veterans Day). The watchlist calls did best; the best-sector call was the hardest to get right.
Look ahead — the week of Nov 16
Next week is the AI trade’s big test. Nvidia reports after the close on Tuesday, its first quarter under interim CEO Colette Kress, and Anthropic is expected to start trading on Thursday. October retail sales on Tuesday (forecast +0.2%), Home Depot, Target and Walmart will show how the consumer is handling 5% yields, and the Fed’s October meeting minutes come out Wednesday. S&P futures were near 7,561 late Friday. Bull (30%): Nvidia beats and gives a clear succession path, yields stall near 5.15%, and the S&P retakes 7,700. Base (45%): solid Nvidia numbers but no big rally, retail earnings mixed, and the S&P chops between 7,450 and 7,650. Bear (25%): a cautious Nvidia outlook or hot retail sales push the 10-year toward 5.25%, and the S&P breaks below 7,450. Wick's pick: Base. US October retail sales
 NVDA earnings
What to watch
- October retail sales at 8:30 AM ET on Nov 17..ics
- Home Depot earnings before the open on Nov 17.
- Nvidia earnings after the close on Nov 17..ics
- Target earnings before the open on Nov 18.
- FOMC minutes at 2:00 PM ET on Nov 18..ics
- Walmart earnings at 7:00 AM ET on Nov 19..ics
- FOMC rate decision at 2:00 PM ET on Dec 9.
Wick's take: This week showed the market can lose Nvidia’s founder and still rally 2.5%, but Friday showed the cost: once traders stopped treating Huang’s exit as Nvidia’s problem alone, every AI hardware name got repriced. With the 10-year at 5.15% and a December hike fully priced, there isn’t much room for a disappointment. Tuesday night’s Nvidia report is the one that matters most, and we’d rather wait for it than chase the bounce in chips.
Market data and opinions by Wick. This post is informational only and is not financial advice. Prices may differ slightly between data vendors; predictions are tracked and scored openly.
Add all 4 events to calendar (.ics) Times are ET. Each event has a 1-day reminder. Estimated dates are marked.
Comments