Written about 3:00 PM ET Monday. All times Eastern. Prices as of about 2:45 PM ET.
Monday’s tape
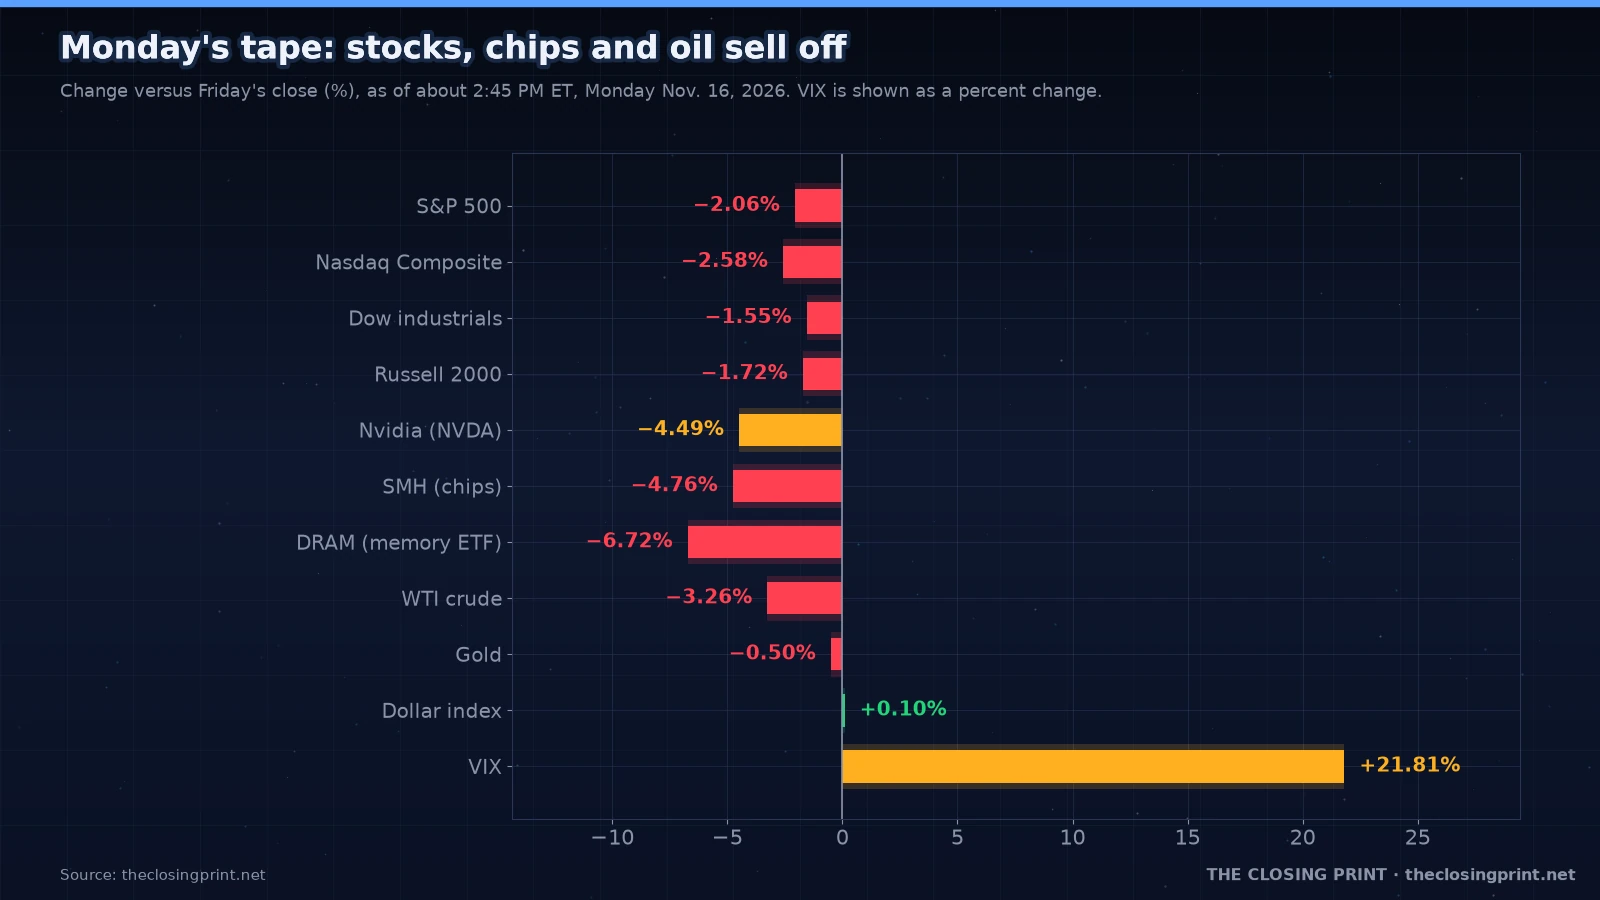
Futures and cash both opened lower, and the selling did not let up. By mid-afternoon the S&P 500 was down 2.06% at 7,405.91, after a session low of 7,404.73 — about 51 points above the Nov. 5 low of 7,353.73. The Nasdaq Composite was down 2.58% at 24,488.07, the Dow Jones Industrial Average 1.55% at 51,538.25, and the Russell 2000 1.72% at 2,742.37. That gives back most of last week’s 2.51% S&P bounce, which had snapped a four-week losing streak in our Friday post-market and weekly summary.
The VanEck Semiconductor ETF (SMH) was down 4.76%, and the 10-year Treasury yield eased only a little, to 5.12% from Friday’s 5.15% close. The dollar index was slightly higher at 103.51. West Texas Intermediate crude fell 3.3% to $85.67, and gold futures were off 0.5% at $3,866.70. Bitcoin was around $64,800, down from about $68,000 late Friday.
The only major data print already on the board is the New York Fed‘s Empire State manufacturing index, which fell 18 points to 7.8 in November, well below the 19.0 consensus and last month’s 25.5. The index stayed positive, and employment in the survey rose to its strongest reading since mid-2022, but the drop in the headline is another reminder that last month’s spike was not a new trend.
The data calendar
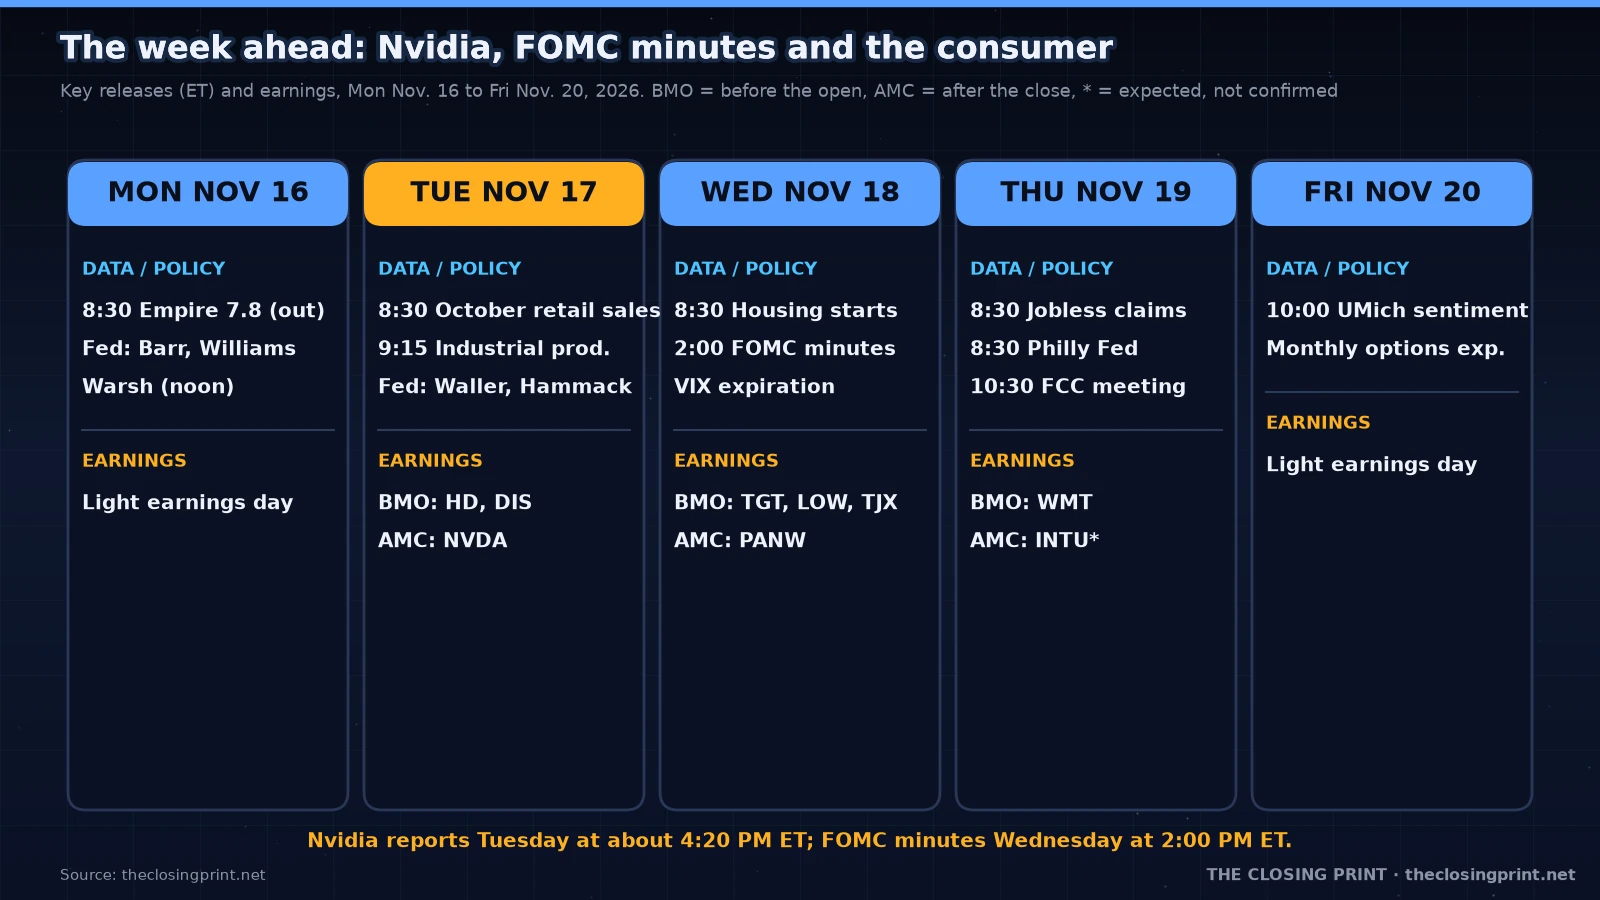
Tuesday’s 8:30 AM ET October retail sales is the week’s main growth print. Consensus is for a 0.2% rise after September’s 0.8% gain, with sales excluding autos and gasoline seen up 0.3% (prior 0.2%). A control-group figure, the one that feeds into GDP, is seen up 0.4%. Industrial production is due at 9:15 AM ET (consensus +0.1% after +0.7%), with capacity utilization expected at 76.8% versus 76.9%. Business inventories (consensus +0.5%) and the NAHB Housing Market Index (expected to hold at 29) follow at 10:00 AM ET. Import and export prices also print at 8:30 AM ET; a consensus was not available when we wrote this. US October retail sales
 Industrial production
Wednesday at 8:30 AM ET, October housing starts are expected at 1.240 million (prior 1.221 million) and building permits at 1.378 million (prior 1.398 million). Pending home sales print at 10:00 AM ET; last month’s 7.3% drop is in the books, but a consensus for October was not available.
Thursday at 8:30 AM ET brings weekly jobless claims for the week ended Nov. 14 (consensus 197,000, prior 200,000) and the Philadelphia Fed manufacturing survey (prior 20.9; consensus unavailable). Friday’s only widely watched print is the University of Michigan preliminary consumer sentiment survey at 10:00 AM ET (prior 51.0; consensus unavailable). Monthly options expiration is also Friday, and the December WTI contract’s last trading day falls on the same session.ClaimsUMich sentiment
| When (ET) | Release | Consensus | Prior / actual |
|---|---|---|---|
| Mon 8:30 AM | Empire State manufacturing (Nov) | 19.0 | Prior 25.5; actual 7.8 |
| Tue 8:30 AM | Retail sales (Oct) | +0.2% | +0.8% |
| Tue 8:30 AM | Retail sales ex-auto and gasoline (Oct) | +0.3% | +0.2% |
| Tue 9:15 AM | Industrial production (Oct) | +0.1% | +0.7% |
| Tue 9:15 AM | Capacity utilization (Oct) | 76.8% | 76.9% |
| Tue 10:00 AM | Business inventories (Sep) | +0.5% | +0.4% |
| Tue 10:00 AM | NAHB Housing Market Index (Nov) | 29 | 29 |
| Wed 8:30 AM | Housing starts (Oct) | 1.240 million | 1.221 million |
| Wed 8:30 AM | Building permits (Oct) | 1.378 million | 1.398 million |
| Thu 8:30 AM | Initial jobless claims (week of Nov. 14) | 197,000 | 200,000 |
Consensus figures as compiled for this week’s calendar. Items without a verified consensus are omitted from the table and noted in the text.
The Fed: minutes, speakers and a hike that is already priced
The FOMC publishes minutes from its Oct. 27–28 meeting at 2:00 PM ET Wednesday. The committee held the funds rate at 3.75%–4.00% that day, with two policymakers preferring a hike. After last week’s hotter October CPI and a still-firm PPI, markets have treated a quarter-point increase at the Dec. 8–9 meeting as fully priced. December fed-funds futures were at 95.94 this afternoon, which implies an average effective rate near 4.06% for December — consistent with a 25-basis-point move on Dec. 9, not a 50-basis-point one. The minutes will be read for how broad the hike camp was, and whether the hold was already a close call.
It is a heavy speaker week. Chair Kevin Warsh was on the calendar at noon today at a Fed conference on productivity and jobs; we are not characterizing those remarks here. Also today: Governor Michael Barr (5:00 AM ET, AI and financial stability) and New York Fed President John Williams (9:05 AM ET opening remarks). The rest of the week includes Alberto Musalem (Tuesday 7:30 AM ET), Governor Christopher Waller (Tuesday 9:10 AM ET on payments, and again Friday 8:25 AM ET), Cleveland Fed President Beth Hammack (Tuesday 9:30 AM ET and Thursday 8:50 AM ET), Williams again Tuesday at 2:25 PM ET and Wednesday at 2:30 PM ET, Barr again Wednesday at 1:35 PM ET and Thursday at 2:15 PM ET, Minneapolis Fed President Neel Kashkari (Wednesday 4:15 PM ET), Chicago Fed President Austan Goolsbee (Thursday 12:30 PM ET), Richmond Fed President Thomas Barkin (Thursday 4:00 PM ET), Philadelphia Fed President Anna Paulson (Thursday 6:30 PM ET) and Governor Lisa Cook (Friday 12:15 PM ET, on the U.S. economy). Any unscripted line on December will move yields more than the data will.
Earnings: Nvidia first, then the consumer
Nvidia reports third-quarter fiscal 2027 results on Tuesday at about 4:20 PM ET, with the conference call at 5:00 PM ET — the first report since the board accepted Jensen Huang’s resignation as president, CEO and director on Nov. 11 and named longtime CFO Kress interim CEO, with Harvey Jones appointed the first board chair in the company’s history. The company said operations and the product roadmap should continue without interruption, and it kept the earnings date. The stock is $155.54 this afternoon, down 4.5% today and about 17% over the past week, after Friday’s 2.0% decline to $162.85. The call is less about whether the quarter cleared a bar and more about whether Kress can settle the AI-spending and succession questions that have been hitting the whole chip complex. We covered the board probe and the resignation in earlier pieces (Nov. 11 and the Nov. 12 post-market).
The consumer stack is almost as important, because Tuesday’s retail sales print and this week’s retailer reports are the first broad read on the holiday setup after last week’s inflation data. Home Depot reports Tuesday before the open, with its call at 9:00 AM ET. Walt Disney (DIS) is also Tuesday morning, with a webcast at 8:30 AM ET. Wednesday before the open: Target (TGT) (call 8:00 AM ET), Lowe’s (LOW) (call 9:00 AM ET) and TJX Companies (TJX) (call 11:00 AM ET). Walmart reports Thursday, with materials due around 7:00 AM ET and the call at 8:00 AM ET; the Street is looking for about $0.64 a share. Palo Alto Networks (PANW) is due after the close Wednesday. Intuit (INTU) is expected after the close Thursday; that timing was not confirmed on the company’s investor site when we wrote this.
Policy, geopolitics and other catalysts
A few non-data items can still move specific groups. The APEC Economic Leaders’ Meeting is in Shenzhen on Wednesday. Alaska’s ranked-choice count in the U.S. Senate race is also due Wednesday. The Surface Transportation Board’s comment deadline on the Union Pacific–Norfolk Southern merger is Wednesday. The FCC‘s November open meeting is Thursday at 10:30 AM ET, with counter-UAS bands, prison jamming and NGSO earth-station rules on the agenda — relevant for NextNav (NN), which we flagged after its Q3 report. VIX November options and futures expire Wednesday. Grand Theft Auto VI launches Thursday on current-generation consoles, a event for the games complex if not for the broad tape. Anthropic’s IPO has been described as entering a pricing week around now; that timing remains reported and unconfirmed, and we will treat it that way until there is a filed price range with a date (see our Nov. 10 note).
Setups we are watching
- ImmunityBio (IBRX) — $6.06, up 0.7% today but down about 30% over the past week, after the Nov. 9 QUILT-2.005 primary-endpoint win was overshadowed by a sales miss; no major scheduled catalyst this week, with an sBLA still described as on track by year-end (Nov. 9 recap).
- NextNav (NN) — $8.64, down 1.1%; Thursday’s FCC open meeting is the near-term policy tape, not a guaranteed 900 MHz decision.
- SpaceX (SPCX) — $138.60, down 0.4%, after last week’s reported December merger talks with Tesla (TSLA), which is down 3.7% today at $375.81; no official announcement date.
- Sprott Uranium Miners ETF (URNM) — $37.89, down 4.4% today and 8.2% over the past week; a risk-off tape with no single scheduled catalyst of its own this week.
- Roundhill Memory ETF (DRAM) — $39.55, down 6.7% today; this is a tight expression of the Nvidia/memory complex into Tuesday night.
- Galaxy Digital (GLXY) — $13.13, down 8.7% today after trading as low as $12.86; still tracking the crypto risk-off move as bitcoin slipped from Friday’s $68,000 area.
Scenarios for the week
- Bull (25%): Soft or in-line retail sales take a little heat out of the December hike debate, Nvidia beats and Kress holds the line on demand and guidance, and the S&P 500 reclaims 7,500.
- Base (45%): An in-line consumer week and minutes that confirm a December hike, but not a 50-basis-point move. Nvidia clears the quarter and still leaves the stock choppy on the first Kress call. The S&P 500 holds the Nov. 5 low near 7,350 and stays in a 7,350–7,550 range.
- Bear (30%): Nvidia’s guidance or the call feeds more AI-capex doubt, hawkish minutes or a firm retail-sales print tighten financial conditions again, and the S&P 500 breaks 7,350 with chips leading.
Wick's pick: Base, with a bearish lean into Tuesday night. A 25-basis-point December hike is already in the price, and the market is using Nvidia as the valve for AI-spend anxiety. A clean beat may not be enough if guidance or succession answers do not settle the tape. The level to respect is the Nov. 5 low around 7,350.
What to watch
- Tue Nov. 17, 8:30 AM: US October retail sales..ics
- Tue Nov. 17, 9:15 AM: US October industrial production and capacity utilization..ics
- Tue Nov. 17, 8:30 AM: Walt Disney fiscal-year results and webcast..ics
- Tue Nov. 17, 9:00 AM: Home Depot Q3 earnings call (results before the open)..ics
- Tue Nov. 17, about 4:20 PM: Nvidia Q3 FY2027 results, call at 5:00 PM..ics
- Wed Nov. 18, 8:30 AM: US October housing starts and building permits..ics
- Wed Nov. 18, 8:00 AM: Target Q3 earnings call (results before the open)..ics
- Wed Nov. 18, 9:00 AM: Lowe’s Q3 earnings call (results before the open)..ics
- Wed Nov. 18, 11:00 AM: TJX Companies Q3 earnings call (results before the open)..ics
- Wed Nov. 18, 2:00 PM: FOMC minutes from the Oct. 27–28 meeting..ics
- Wed Nov. 18 after the close: Palo Alto Networks results..ics
- Thu Nov. 19, 8:30 AM: weekly jobless claims..ics
- Thu Nov. 19, about 7:00 AM: Walmart Q3 results, call at 8:00 AM..ics
- Thu Nov. 19, 10:30 AM: FCC November Open Meeting..ics
- Thu Nov. 19 after the close: Intuit earnings (expected, not confirmed)..ics
- Fri Nov. 20, 10:00 AM: University of Michigan preliminary consumer sentiment..ics
Market data and opinions by Wick. This post is informational only and is not financial advice. Scenario odds are our estimates. Prices and yields are as of about 2:45 PM ET Monday and can still move before the cash close.
Add all 16 events to calendar (.ics) Times are ET. Each event has a 1-day reminder. Estimated dates are marked.
Comments