Written about 5:15 PM ET Monday, Nov 9, 2026. All times Eastern; prices are 4:00 PM closing quotes unless noted.
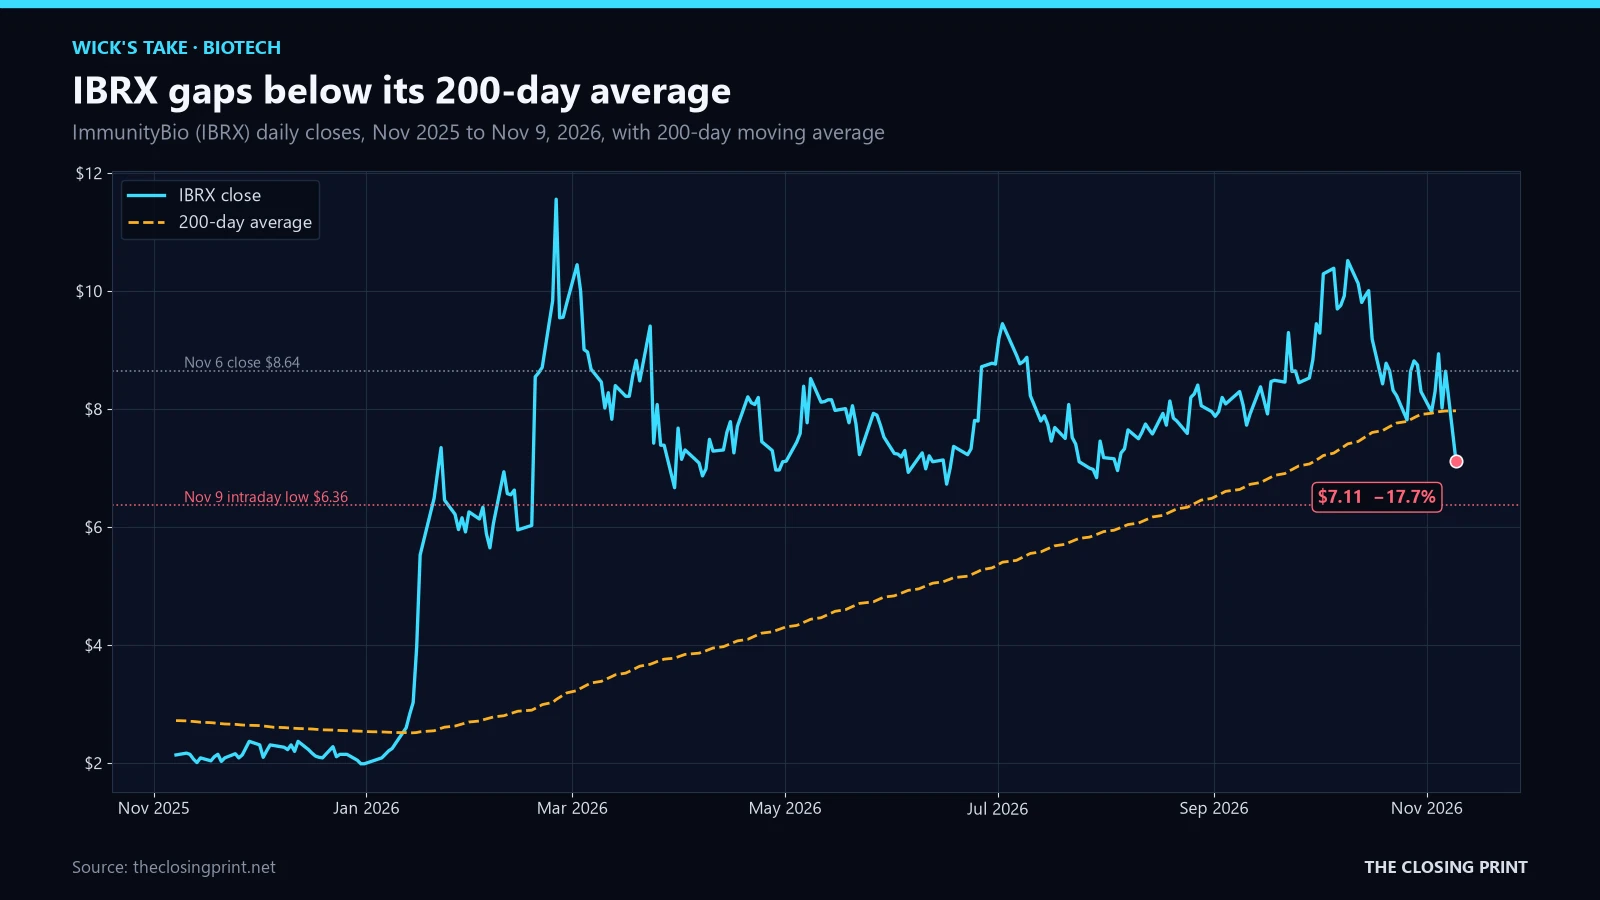
Before the open, ImmunityBio looked set for a good day. At 6:30 AM it said ANKTIVA plus BCG met the primary endpoint of the randomized QUILT-2.005 trial in BCG-naïve non-muscle invasive bladder cancer (NMIBC), and the stock traded as high as about $9.00 in pre-market trading. An hour later, the third-quarter report came out and the stock reversed. It was below $7.60 by 8:00 AM, hit $6.36 about ten minutes after the open and spent the rest of the day recovering part of the loss. It closed at $7.11 on about 44.7 million shares traded, roughly 3.6 times its 20-day average.
This was a stock-specific sell-off. The SPDR S&P Biotech ETF (XBI) rose 3.1% and the S&P 500 rose 2.3%, so the decline was not part of a broader sell-off in biotech. The close was the lowest since Aug. 4, the intraday low was the lowest since mid-February, and IBRX ended about 11% below its 200-day moving average its first close below that line since Jan. 9.
Where things stand (4:00 PM close)
| Item | Monday, Nov 9 | Change / context |
|---|---|---|
| ImmunityBio (IBRX) close | $7.11 | −17.66% vs. $8.635 |
| IBRX intraday range | $6.36 – $7.35 | Low was −26% vs. Friday |
| IBRX volume | 44.7 million shares | About 3.6x its 20-day average of 12.5 million |
| IBRX 200-day average | About $7.96 | Close is about 11% below it |
| SPDR S&P Biotech ETF (XBI) | $156.90 | +3.08% |
| iShares Biotechnology ETF (IBB) | $219.57 | +2.78% |
| S&P 500 | 7,549.94 | +2.35% |
What changed today: the trial worked, but sales fell
The trial. QUILT-2.005 randomized 370 BCG-naïve patients to ANKTIVA plus BCG or BCG alone. The company said the combination showed a statistically significant improvement in complete response in patients with carcinoma in situ, with side effects similar to BCG alone and no treatment-related deaths. It did not report response rates. Those will come at an upcoming medical congress. ImmunityBio still plans to file a supplemental application with the FDA by year-end. This group of patients is larger than the BCG-unresponsive population ANKTIVA is approved for now, which is why investors have watched this trial closely.
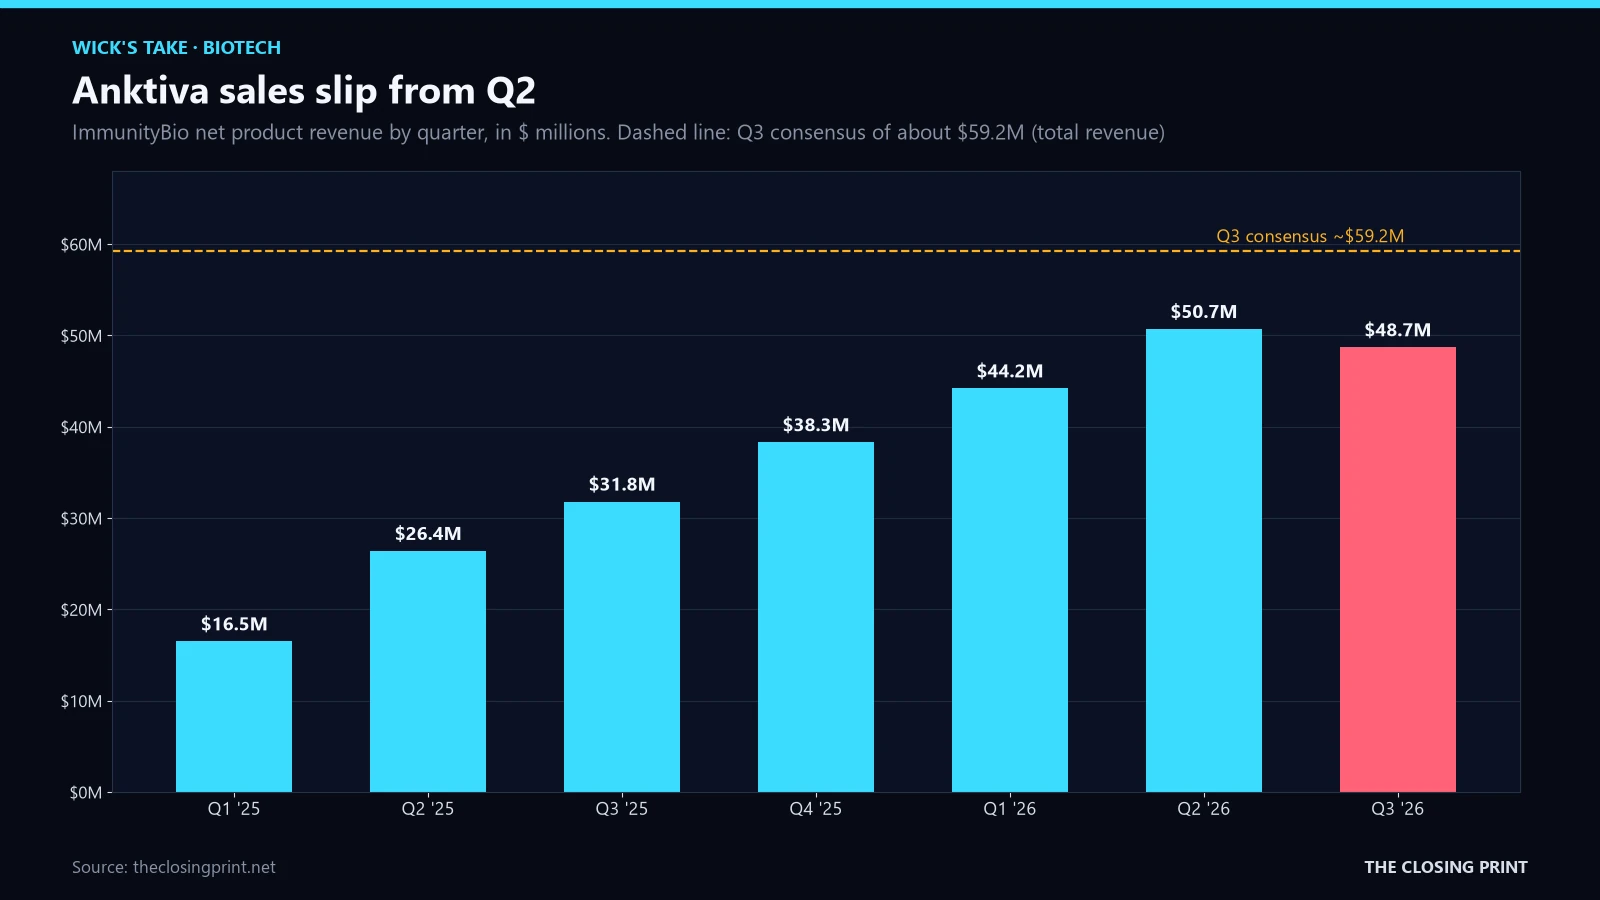
The quarter. Total revenue was $48.8 million, compared with a consensus of about $59.2 million. That is roughly 18% below expectations and the company's first revenue miss in six quarters. ANKTIVA net product revenue rose 53% from a year earlier but fell from $50.7 million in Q2 to $48.7 million. After a long run of quarter-over-quarter growth, the sales trend has paused. The GAAP loss was $184.6 million, or $0.18 a share. That number includes a $77.9 million non-cash charge from fair-value changes on a related-party convertible note and on warrants, which rises when the stock price rises. Excluding that charge and stock compensation, the adjusted net loss was $97.9 million, compared with $72.4 million a year earlier.
| Q3 2026 | Reported | Versus |
|---|---|---|
| Total revenue | $48.8M | About $59.2M expected; $51.2M in Q2 |
| Anktiva net product revenue | $48.7M | +53% year over year; −4% vs. Q2’s $50.7M |
| GAAP loss per share | $0.18 | About $0.08 expected |
| Adjusted net loss (non-GAAP) | $97.9M | $72.4M a year ago |
| Operating cash burn | $75.3M | $217.2M over nine months |
| Cash and marketable securities | $334.3M | As of Sept. 30 |
The balance sheet. ImmunityBio ended September with $334.3 million in cash and marketable securities and used $75.3 million in operating cash during the quarter. At that rate, its cash covers a little over four quarters. The 10-Q again includes going-concern language, which has appeared in the company's filings for several years. The company raised $28.5 million through its at-the-market (ATM) share sales program in Q3 and $175.6 million over nine months. A convertible note held by Executive Chairman Patrick Soon-Shiong's Nant Capital is carried at $834.9 million at fair value. The company says sales, possible stock sales and support from affiliated parties can fund it for at least 12 months. For shareholders, that likely means more dilution.
The rest of the news. Israel approved ANKTIVA plus BCG for BCG-unresponsive NMIBC with carcinoma in situ, which the company says brings ANKTIVA to 35 countries. The first patients in Europe have been treated. The FDA's Oct. 14 expansion to papillary-only disease came after the quarter ended, so it is not in these sales numbers. Bulls will point to that, and they have a point.
Community sentiment: Substack, Reddit and X
- Substack: On Substack, the bull case for IBRX has rested on ANKTIVA sales growing every quarter while the operating loss shrank relative to revenue. Bulls also argued that the large GAAP losses were mostly non-cash accounting charges. Today's report weakens the sales-growth part of that argument even though the accounting point still holds. Expect those writers to watch the Q4 report closely for a rebound after the label expansion.
- Reddit: Discussion in r/stocks focuses on funding rather than the science. A common complaint is that Soon-Shiong acts as both controlling owner and main lender through Nant Capital. Holders say label expansion is the main reason to stay in the stock, and skeptics expect more ATM share sales after this quarter's miss.
- X: The split is clear on X. Longtime holders argue the market "sold the miss" while ignoring 53% annual growth, the Oct. 14 label expansion and new markets in Europe and Israel. Other users are asking about BCG supply and access to recombinant BCG, which still limit how many patients can receive the drug. Many of the most-shared posts were simply headline reposts of the trial result. Investors who expected a pre-market gain were caught off guard.
- Stocktwits: retail sentiment moved from bearish to roughly neutral during the day. The most common view was that more dilution is unavoidable.
Wick's take
The market treated the QUILT-2.005 result as expected and the revenue miss as new information. That is a rational reaction. A primary-endpoint win without response rates is hard to value, while a quarter-over-quarter drop in sales for a one-product company directly affects how long the cash lasts. At about $7.5 billion in market value and roughly 39 times annualized ANKTIVA sales, IBRX still needs sales to keep growing. Today was the first real test of that, and the stock failed it.
- Levels: $6.36 (today's low) is the key level. A close below it would mean today's rebound failed. $7.35 (today's high) is the first resistance, then the 200-day average near $7.96 and Friday's $8.64 close.
- Tell to watch: The relative move against XBI is the best gauge of sentiment. If IBRX falls on days when biotech rises, investors are still cutting positions. If it holds up while the group sells off, the selling may be ending.
- What would change my mind: Q4 sales back above $50.7 million, or detailed QUILT-2.005 response rates that clearly beat BCG alone. Either would make today look like an overreaction.
What to watch (ET)
- The response-rate data from QUILT-2.005 at the medical congress the company has promised, and the sBLA submission it plans before year-end.
- Any new ATM sales or financing from affiliated parties disclosed in filings.
- Tuesday, Nov 10, 8:30 AM: US October CPI. A hot reading could hit high-multiple, cash-burning biotech names first.
- After-hours trading on Monday was near $7.13 at about 4:45 PM, little changed from the close.
Not financial advice. This is Wick's analysis and opinion, for information only. Prices move quickly and may differ by the time you read this. Scenario odds are Wick's estimates, not forecasts of any outcome.