Written about 9:00 AM ET Tuesday, before the opening bell. All times Eastern; quotes as of about 8:45 AM ET.
Markets at about 8:45 AM ET
| Market | Level | Change |
|---|---|---|
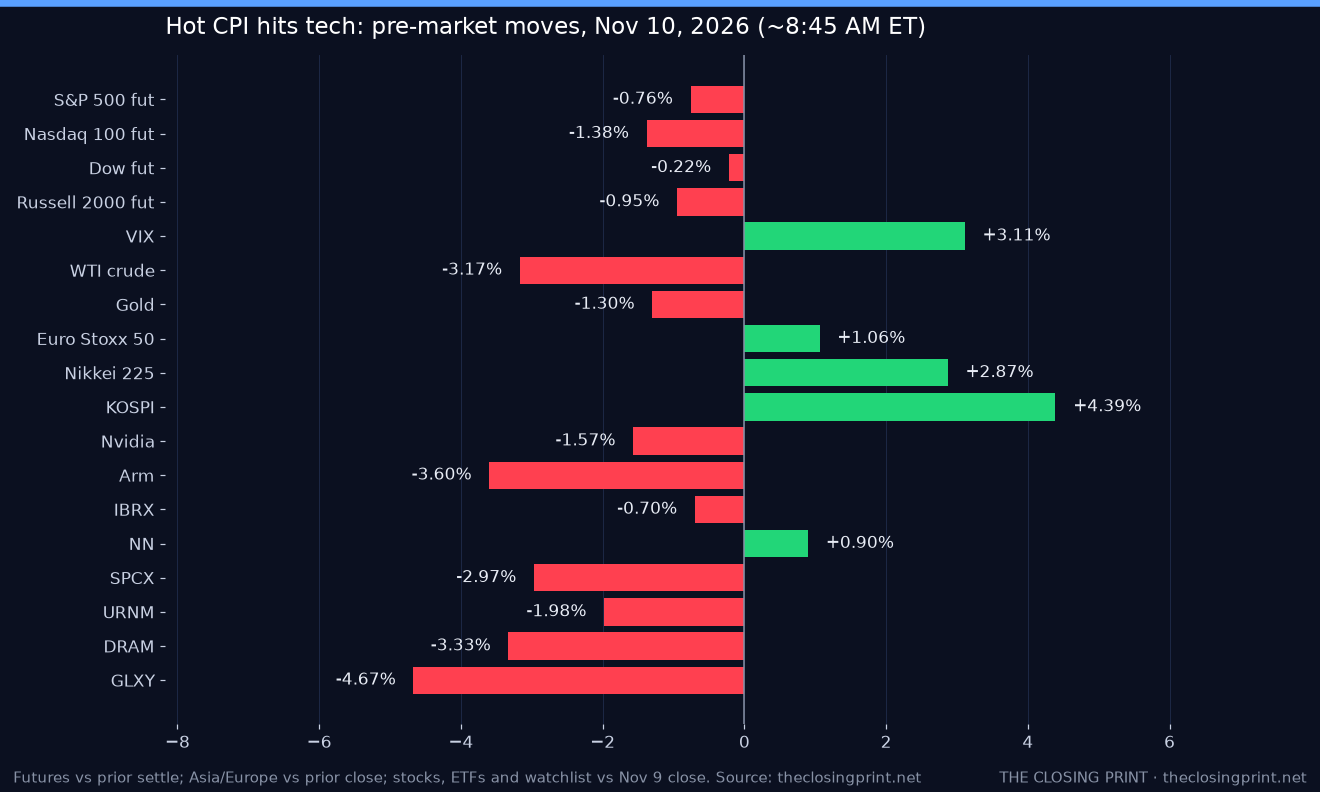
| S&P 500 futures | 7,517.00 | -0.76% |
| Nasdaq 100 futures | 27,628.00 | -1.38% |
| Dow futures | 52,380.00 | -0.22% |
| Russell 2000 futures | 2,821.70 | -0.95% |
| 10-year Treasury yield | 4.929% | +6.5 bp |
| 2-year Treasury yield | about 4.70% (4.56% Nov 9 close) | about +14 bp |
| US Dollar Index (DXY) | 102.00 | +0.35% |
| WTI crude ($/bbl) | $84.10 | -3.17% |
| Brent crude ($/bbl) | $89.24 | -3.60% |
| Gold ($/oz) | $4,061 | -1.30% |
| Bitcoin | $73,882 | -1.78% |
| VIX | 20.54 | +3.11% |
| Nikkei 225 (close) | 60,459.58 | +2.87% |
| Hang Seng (close) | 24,557.04 | +0.44% |
| KOSPI (close) | 5,239.13 | +4.39% |
| Shanghai Composite (close) | 3,663.72 | +0.08% |
| Euro Stoxx 50 | 6,357.11 | +1.06% |
| DAX | 26,578 | +1.18% |
| FTSE 100 | 10,829 | +0.43% |
| CAC 40 | 8,327 | +1.14% |
Futures vs prior settle; the 2-year level is approximate.
What’s moving before the bell
CPI comes in hot. Consumer prices rose 0.4% in October against forecasts for 0.3%, and core prices rose 0.3% against 0.2%. Energy rose 0.7%, food 0.5%, shelter 0.3% and transportation services 0.8%, while used cars fell 1.2%. There is no official year-over-year rate this month because October 2025 data were never collected during the shutdown. The next CPI is Dec. 10.
The Fed may move faster. Before the report, Waller said a December hike is likely and that a 50 bp move should be considered if inflation came in hot, because “hiking only 25 basis points would put our credibility at risk.” Rate futures had already priced most of a quarter-point hike. The 10-year is about 4.93% and the 2-year about 4.70%; the dollar is firmer (DXY 102.00) and gold is down 1.3%.
Tech gives back Monday’s rally. Chips lead the decline: Arm Holdings (ARM) is down about 3.6%, Qualcomm (QCOM) 2.6%, Advanced Micro Devices (AMD) 2.3% and Nvidia (NVDA) 1.6% as its board probe of CEO Jensen Huang continues. Tesla (TSLA) is down 1.8%. Apple (AAPL) is slightly higher.
Oil keeps falling and Anthropic sets an IPO range. WTI is $84.10 (-3.2%) and Brent $89.24 after President Trump said the Iran war is “militarily effectively over,” putting Brent near three-month lows. Anthropic set a price range for its IPO, with reports of a target valuation around $1.4 trillion.
Overseas: Asia rallied hard before the US data: the KOSPI jumped 4.4% and the Nikkei 2.9% to a record 60,460, while Hong Kong added 0.4%. Europe is higher too, with the DAX up about 1.2% and the CAC 1.1%.
Economic calendar and Fed (ET)
- 8:30 AM: October CPI (out: +0.4% headline, +0.3% core).
 .ics

- 8:40 AM: Fed Governor Michelle Bowman speaks.
- 10:00 AM: wholesale inventories (consensus +0.6%) and Chicago Fed President Austan Goolsbee speaks.
- 11:00 AM: New York Fed one-year consumer inflation expectations (consensus 3.8%, prior 3.9%).
- 11:30 AM: Atlanta Fed GDPNow update (last 3.4%).
- 12:15 PM: Richmond Fed President Thomas Barkin speaks.
- 1:00 PM: 3-year note auction.
- Later this week: jobless claims Thursday and October PPI Friday.ClaimsPPI Oct
Earnings
Before the open: TransDigm Group (TDG), Sea Limited (SE), Vodafone (VOD), Venture Global (VG), On Holding (ONON), Legend Biotech (LEGN) and Wix.com (WIX). D-Wave Quantum (QBTS) also reports today.
After the close: CoreWeave (CRWV), Petrobras (PBR), Alcon (ALC), Rigetti Computing (RGTI), Firefly Aerospace (FLY), StubHub (STUB), Sonos (SONO) and NextNav.
Watchlist setups
- ImmunityBio (IBRX) $7.06 (-0.7% vs $7.11 close): holding near Monday’s lows after the Q3 sales miss and going-concern language; it needs a quiet tape to stabilize.
- NextNav (NN) $9.00 (+0.9% vs $8.92 close): the one green name on the list in thin trade; Q3 results are due after the close, so expect a quiet session and a move tonight.
- SpaceX (SPCX) $137.86 (-3.0% vs $142.07 close): giving back part of Monday’s bounce as high-multiple growth stocks sell off on higher yields.
- Sprott Uranium Miners ETF (URNM) $43.03 (-2.0% vs $43.90 close): slipping with the broader energy complex as oil falls again.
- Roundhill Memory ETF (DRAM) $40.39 (-3.3% vs $41.78 close): fading with chips after Monday’s big rebound; CoreWeave’s results tonight are the next AI-spending read.
- Galaxy Digital (GLXY) $13.83 (-4.7% vs $14.51 close): the weakest name on the list as bitcoin slips after the CPI print, following a Monday price-target cut from Morgan Stanley.
Scenarios and Wick's pick
- Bull (20%): buyers treat a core miss of one tenth as noise, yields stall and the S&P closes above 7,520.
- Base (50%): a hike-priced tape with tech lagging and defensives holding up; the S&P closes 7,440–7,520.
- Bear (30%): the market starts pricing a half-point December hike, the 2-year keeps climbing and the S&P closes below 7,440.
Wick's pick: Base. A December hike was already mostly priced, so the hot print mostly raises the risk of a bigger move; that should keep pressure on tech without turning into a rout after Monday’s strong day.
Predictions for today’s close
| Prediction | Call | Confidence | Why |
|---|---|---|---|
| S&P 500 close vs Nov 9 close 7,549.94 (implied open ~7,493) | lower (7,440–7,520) | medium (60%) | Futures are down about 0.8% after a hot CPI and Waller’s talk of a half-point hike. |
| 10-year yield close vs 4.864% prior | higher | medium (65%) | Up about 6 bp already, with the 2-year jumping more as hike odds rise. |
| VIX close vs 19.92 prior | higher | low-medium (55%) | Edging up toward 20.5; Monday’s relief rally leaves room for a pullback. |
| Best S&P sector ETF (SPDR XL_) | XLV | low (35%) | Defensives lead pre-market: XLV, XLP and XLC are each up about 0.4%. |
| Worst S&P sector ETF (SPDR XL_) | XLK | medium (50%) | Tech is weakest pre-market (about −1.5%) as rate-sensitive chip stocks give back Monday’s gains. |
| IBRX close vs $7.11 | lower | low (50%) | Slightly red after Monday’s earnings plunge, with dilution worries hanging over it. |
| NN close vs $8.92 | lower | low (50%) | Slightly green in thin trade, but small caps are soft and it reports after the close. |
| SPCX close vs $142.07 | lower | low-medium (55%) | Down about 3% pre-market as growth names slide. |
| URNM close vs $43.90 | lower | low-medium (55%) | Down about 2% pre-market with energy and cyclicals soft. |
| DRAM close vs $41.78 | lower | low-medium (55%) | Down about 3.3% pre-market as memory and chip stocks fade after Monday’s 6.9% chip rally. |
| GLXY close vs $14.51 | lower | medium (60%) | Down about 4.7% pre-market with bitcoin off about 1.8% after the CPI print. |
What to watch
- 10:00 AM ET: Chicago Fed President Austan Goolsbee speaks.
- 11:00 AM ET: New York Fed consumer inflation expectations.
- 12:15 PM ET: Richmond Fed President Thomas Barkin speaks.
- After the close: CoreWeave, Rigetti and NextNav report.
- Nov 13, 8:30 AM ET: October PPI..ics
- Dec 9, 2:00 PM ET: FOMC decision.
Add all 3 events to calendar (.ics) Times are ET. Each event has a 1-day reminder. Estimated dates are marked.
Not financial advice. Model estimates and opinions by Wick, for information only. Pre-market quotes can be thin and stale, and predictions are tracked and scored openly after the close.