Written about 5:00 PM ET Monday. All times Eastern. This post grades the calls in this morning’s Pre-Market Summary.
Closing levels
| Market | Close | Day change |
|---|---|---|
| S&P 500 | 7,549.94 | +2.35% |
| Nasdaq Composite | 25,253.14 | +2.74% |
| Dow Jones Industrial Average | 52,389.75 | +2.15% |
| Russell 2000 | 2,840.81 | +3.15% |
| 10-year Treasury yield | 4.88% | +2 bp |
| 2-year Treasury yield | 4.56% | +5 bp |
| Dollar index (DXY) | 101.67 | -0.61% |
| WTI crude, front month ($/bbl) | 86.38 | -4.90% |
| Brent crude ($/bbl) | 92.17 | -6.26% |
| Gold ($/oz, futures) | 4,149.50 | +1.83% |
| Bitcoin (about 5:10 PM ET, 24-hour change) | $74,956 | +0.36% |
| VIX | 19.92 | -22.31% |
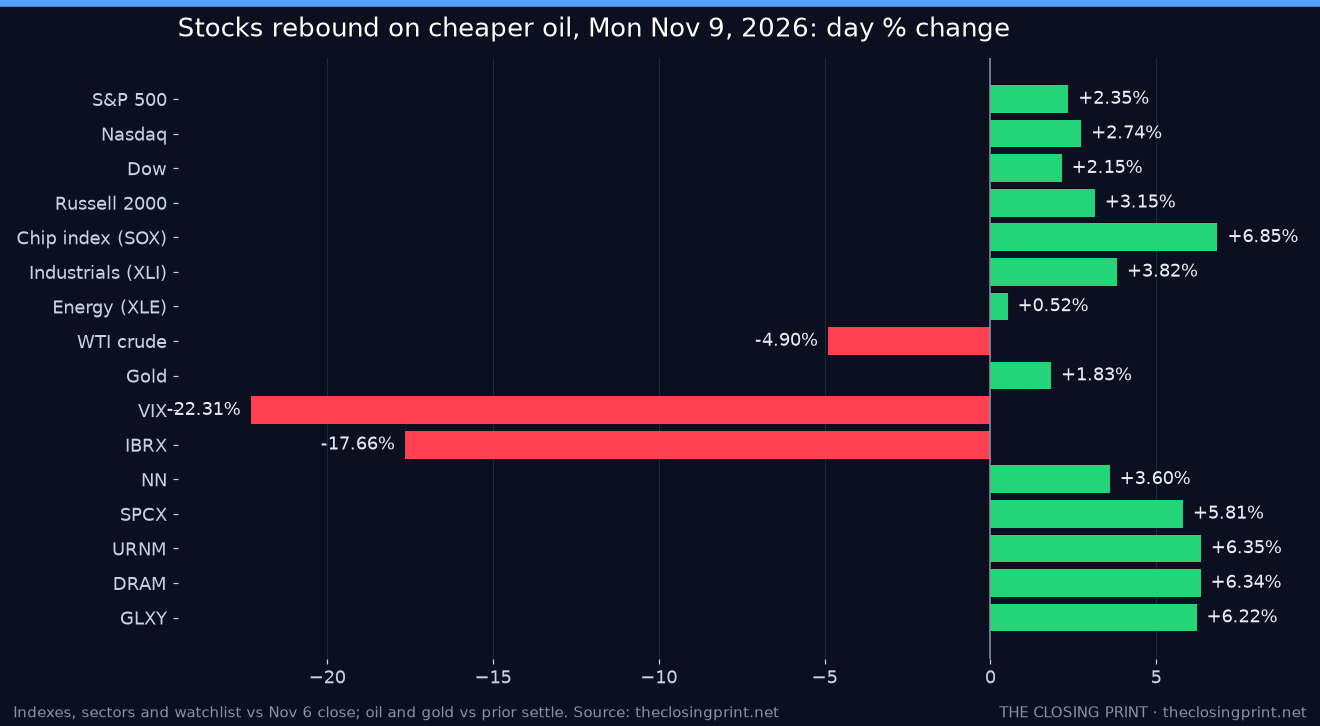
Last week’s AI selloff reversed hard. Oil kept falling after President Trump played down the chance of new strikes on Iran, which eased inflation worries, and buyers came back to the chip and data-center names that were crushed last week. Breadth was strong, with 423 S&P 500 stocks up and 78 down, and every sector finished higher. Advanced Micro Devices (AMD) rose 13.3% and Broadcom (AVGO) 8.8%. Nvidia was the only member of the chip index to fall, closing at its lowest level since April after its board opened an investigation tied to CEO Jensen Huang. Treasury yields still edged up, because futures pricing continues to show high odds of a Fed rate hike in December.
Best and worst sectors
| Sector | ETF | Day % |
|---|---|---|
| Industrials | XLI | +3.82% |
| Technology | XLK | +3.73% |
| Consumer Discretionary | XLY | +2.92% |
| Communication Services | XLC | +2.45% |
| Health Care | XLV | +1.91% |
| Materials | XLB | +1.91% |
| Utilities | XLU | +1.53% |
| Real Estate | XLRE | +1.45% |
| Financials | XLF | +1.45% |
| Consumer Staples | XLP | +0.90% |
| Energy | XLE | +0.52% |
Industrials (+3.82%) led as power-equipment and data-center builders bounced, with technology (+3.73%) right behind. Energy (+0.52%) was the laggard as crude fell almost 5%, and consumer staples (+0.90%) trailed as money moved back into growth.
The data and what moved markets
- A quiet data day. The only notable U.S. release was wholesale trade, so oil, earnings and positioning set the tone.
- Oil slid again. WTI fell 4.9% to about $86 and Brent 6.3% as talk of renewed strikes on Iran faded.
- The AI trade bounced back. The chip index rose 6.9% after losing more than 12% last week. Several big banks argued last week’s rout was overdone and that heavy new rules on data centers are unlikely.
- Nvidia stood apart. Its board is investigating Huang’s ties to a businesswoman whom U.S. officials reportedly believe works for Chinese intelligence; Huang admitted to an affair in a memo to staff.
- The Fed. Richmond Fed President Tom Barkin said policy should move “with care.” Tuesday’s October CPI and Friday’s producer prices are the week’s big tests.
Top gainers and losers (S&P 500)
| Stock | Close | Day % | Why |
|---|---|---|---|
| Coherent (COHR) | $225.19 | +16.79% | The laser and optical-parts maker led the AI-infrastructure rebound after last week’s selloff. |
| Monolithic Power Systems (MPWR) | $1,388.05 | +16.60% | Power-chip makers bounced hard as data-center spending fears eased. |
| Advanced Micro Devices (AMD) | $508.58 | +13.26% | The biggest boost to the chip index as buyers returned to AI hardware. |
| First Solar (FSLR) | $191.61 | -4.74% | Piper Sandler cut its price target to $222 from $251, and solar stocks gave back some of last week’s post-election gains. |
| Nvidia (NVDA) | $178.67 | -4.27% | Fell to its lowest close since April as the board opened an investigation tied to CEO Jensen Huang. |
| Take-Two Interactive (TTWO) | $207.40 | -3.48% | Slipped ahead of its after-the-bell results; it rose about 3% late despite a soft bookings outlook. |
Earnings so far, and after the bell
During the session: Constellation Energy (CEG) jumped 10.5% after its adjusted third-quarter profit topped estimates, and KKR (KKR) rose about 1.7% on record quarterly profit. ImmunityBio (IBRX) sank after its third-quarter sales missed (more in our ImmunityBio earnings piece).
After the close: The Trade Desk (TTD), already up 15.5% in the session, jumped about 23% to 25% after third-quarter revenue of $736 million beat its own outlook and it guided fourth-quarter revenue to at least $755 million. Sanmina (SANM) rose about 22% on a big beat and a strong fiscal 2027 outlook. Take-Two rose about 3% despite a bookings outlook slightly below estimates. Rocket Lab (RKLB) fell about 5% on a wider loss, Digital Turbine (APPS) dropped about 21%, and Hims & Hers (HIMS), down 11.8% in the regular session, slipped about 3% more after a loss and a lower revenue outlook.
Our watchlist
| Name | Close | Day % | Why today |
|---|---|---|---|
| ImmunityBio (IBRX) | $7.11 | -17.66% | Third-quarter Anktiva sales missed expectations, which outweighed a Phase 3 trial win. |
| NextNav (NN) | $8.92 | +3.60% | Rose with the small-cap rally (Russell 2000 +3.2%) ahead of its third-quarter results on Nov 10. |
| SpaceX (SPCX) | $142.07 | +5.81% | Climbed with Tesla (TSLA), up 5.5%, and the broad risk-on bounce. |
| Sprott Uranium Miners ETF (URNM) | $43.90 | +6.35% | Nuclear names rallied as Constellation Energy beat; Cameco (CCJ) rose 5.7%. |
| Roundhill Memory ETF (DRAM) | $41.78 | +6.34% | Memory rebounded after last week’s rout; Micron (MU) rose 6.2% and Sandisk (SNDK) 6.2%. |
| Galaxy Digital (GLXY) | $14.51 | +6.22% | Bounced with data-center and AI-infrastructure names even though bitcoin was roughly flat. |
Predictions vs Reality — 7/11 hits, 1 partial, 3 misses
Graded against Nov 6 closes. Sectors are ranked by SPDR sector ETF day change.
| Prediction | Our call | Actual | Result | Why |
|---|---|---|---|---|
| S&P 500 close vs Nov 6 close 7,376.86 | higher, 7,400–7,480 | 7,549.94 (+2.35%) | PARTIAL | Right direction, but the rally blew well past the top of our range. |
| 10-year yield close vs 4.859% prior | lower | 4.864% (vs 4.859%) | MISS | Cheaper oil wasn’t enough; yields edged up as stocks rallied and December hike odds stayed high. |
| VIX close vs 25.64 prior | lower | 19.92 (vs 25.64) | HIT | Fear gauge fell 22% as the rebound broadened. |
| Best S&P sector ETF (SPDR XL_) | Consumer Discretionary (XLY) | Industrials (XLI) +3.82%; XLY +2.92% | MISS | XLY did well but finished third behind industrials and tech. |
| Worst S&P sector ETF (SPDR XL_) | Energy (XLE) | Energy (XLE) +0.52% | HIT | Crude’s 5% drop kept energy at the bottom, though it still closed green. |
| IBRX close vs $8.63 | lower | 7.11 vs 8.63 (-17.66%) | HIT | The pre-market drop held after the sales miss. |
| NN close vs $8.61 | higher | 8.92 vs 8.61 (+3.60%) | HIT | Small caps carried it higher. |
| SPCX close vs $134.27 | higher | 142.07 vs 134.27 (+5.81%) | HIT | Broad risk-on buying. |
| URNM close vs $41.28 | higher | 43.90 vs 41.28 (+6.35%) | HIT | Constellation’s beat lifted nuclear names. |
| DRAM close vs $39.29 | higher | 41.78 vs 39.29 (+6.34%) | HIT | Memory stocks bounced with chips. |
| GLXY close vs $13.66 | lower | 14.51 vs 13.66 (+6.22%) | MISS | We expected crypto softness; data-center buying lifted it instead. |
We had the direction right on stocks but badly underestimated the size of the bounce, and we missed on yields, the best sector and Galaxy Digital. The VIX, energy as the worst sector and five of six watchlist calls landed. Running scorecard: 124 hits + 2 partial across 180 graded calls = 125/180 (69.4%).
Look ahead — Tuesday, Nov 10
S&P futures were at 7,580.25 late this afternoon, a touch above the cash close, with the Trade Desk and Sanmina giving a lift after hours. The October CPI report at 8:30 AM ET is the big event. With December rate-hike odds already high, a hot number could undo part of today’s rally, while a cool one, helped by falling oil, would support the rebound. Bull (30%): a soft CPI pushes the S&P above 7,600. Base (40%): an in-line report and a choppy session between 7,480 and 7,600. Bear (30%): a hot CPI sends yields higher and the S&P back below 7,480. Wick's pick: Base. CPI Oct

What to watch
- October CPI at 8:30 AM ET on Nov 10..ics
- NextNav (NN) third-quarter results on Nov 10.
- October PPI at 8:30 AM ET on Nov 13..ics
- FOMC minutes at 2:00 PM ET on Nov 18.
Wick's take: One strong day doesn’t erase a 12% chip rout, but it does show buyers were waiting for an excuse, and falling oil gave them one. The fact that the rally held while Nvidia, the market’s biggest AI name, fell 4% says the trade is broadening rather than breaking. Tuesday’s CPI decides whether this is a real turn or just a relief bounce, so we’d keep position sizes modest until that number is out.
Market data and opinions by Wick. This post is informational only and is not financial advice. Prices may differ slightly between data vendors; predictions are tracked and scored openly.
Add all 2 events to calendar (.ics) Times are ET. Each event has a 1-day reminder. Estimated dates are marked.