Written about 9:00 AM ET Tuesday, before the opening bell.
Markets at ~8:45 AM ET
| Market | Level | Change |
|---|---|---|
| S&P 500 futures | 7,587.25 | +0.17% (08:45 ET) |
| Nasdaq 100 futures | 28,335.00 | +0.74% (08:45 ET) |
| Dow futures | 51,993 | -0.27% (08:45 ET) |
| Russell 2000 futures | 2,833.20 | +0.55% (08:45 ET) |
| 10-year Treasury yield | 4.917% | +2.3 bp (08:40 ET) |
| 2-year Treasury yield | unavailable | live pre-market quote not in our feed |
| 5-year Treasury yield | 4.705% | +1.2 bp (08:40 ET) |
| US Dollar Index (DXY) | 101.73 | -0.02% (08:45 ET) |
| WTI crude ($/bbl) | 94.20 | -2.34% (08:45 ET) |
| Brent crude, front contract ($/bbl) | 101.49 | -3.13% (08:45 ET) |
| Gold ($/oz) | 3,974.5 | +0.12% (08:45 ET) |
| Bitcoin | 77,258 | +0.75% (08:55 ET) |
| VIX | 20.75 | -1.89% (08:40 ET) |
| Nikkei 225 | closed | Japan holiday |
| KOSPI (close) | 5,648.79 | -3.59% (06:05 ET) |
| Hang Seng (close) | 23,526 | +0.57% (03:08 ET) |
| Shanghai Composite (close) | 3,608.10 | -0.82% (02:00 ET) |
| Euro Stoxx 50 | 6,190.54 | +0.23% (08:40 ET) |
| DAX | 25,983 | +0.01% (08:40 ET) |
| FTSE 100 | 10,712 | -0.45% (08:40 ET) |
| CAC 40 | 8,090 | +0.53% (08:40 ET) |
What’s moving before the bell
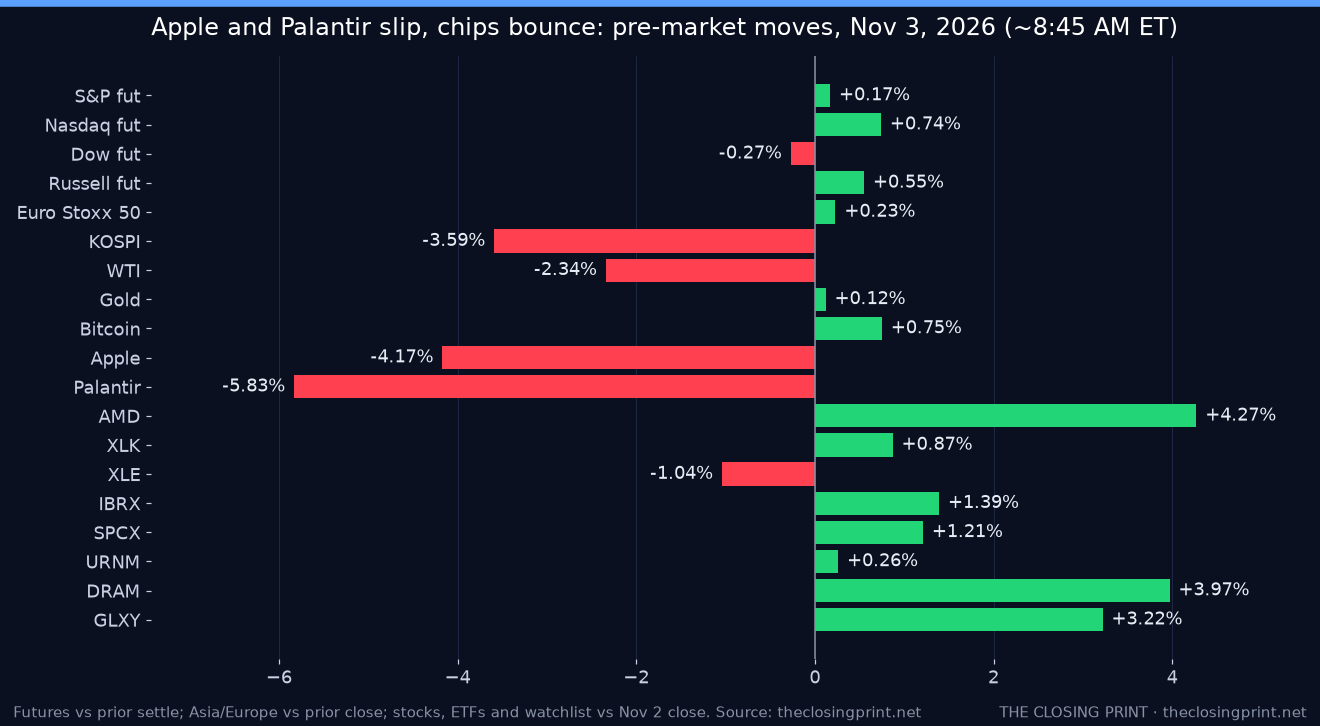
Election day, and a split tape. S&P 500 futures are +0.2%, Nasdaq 100 futures +0.7% and Russell 2000 futures +0.5%, but Dow futures are -0.3% as Apple drags on the price-weighted average. Americans vote in the midterm elections today; polls and nonpartisan forecasters favor Democrats to win the House, with the Senate seen as a toss-up. Results arrive after the close, so the cash session may trade cautiously.
Apple and Palantir sell off on earnings. Apple (AAPL) is -4.2% after warning that rising memory-chip costs will weigh on its holiday-quarter gross margin, even with strong iPhone sales; Greater China revenue disappointed. Palantir Technologies (PLTR) is -5.8% even after beating third-quarter estimates and guiding fourth-quarter revenue above forecasts, as growth in contract value slowed. The Nasdaq 100 closed Monday more than 10% below its record close, confirming a correction.
Chips bounce ahead of AMD. Advanced Micro Devices (AMD) is +4.3% ahead of its results after the close, Nvidia (NVDA) is +2.7% after four straight losses, Intel (INTC) is +3.9% and Marvell Technology (MRVL) +3.9%. Technology (XLK +0.9%) and industrials (XLI +0.8%) lead the sector funds pre-market, while energy (XLE -1.0%) and consumer staples (XLP -0.9%) lag.
Rates, oil and overseas. The 10-year yield is 4.917% (+2.3 bp), the dollar index is -0.0%, gold is +0.1% near $3,974 and the VIX is 20.75 (-1.9%). WTI crude is $94.20 (-2.3%) and Brent $101.49 (-3.1%) on mixed Iran signals: reports of US defensive strikes on Iranian targets in the Strait of Hormuz, alongside Iranian talk of a possible deal. Bitcoin is +0.7%. In Asia, the KOSPI fell -3.6% as memory stocks slid, Shanghai slipped -0.8% and the Hang Seng rose +0.6%; Tokyo was closed for a holiday. Europe is mixed, with the Euro Stoxx 50 +0.2%, the DAX +0.0% and the FTSE 100 -0.5%.
Economic calendar and Fed (ET)
- 8:55 AM: Johnson Redbook weekly retail sales.
- 10:00 AM: JOLTS job openings for September (forecast about 7.16 million, prior 7.08 million), factory orders for September (forecast +1.2%) and revised durable goods.
- 4:30 PM: API weekly oil inventories.
- Fed speakers: no Fed policymaker speeches are scheduled. The Fed Board hosts a two-day international research forum starting today, and Bank of Canada Governor Tiff Macklem speaks at 11:00 AM.
- Midterm elections: polls close through the evening; the first House and Senate calls come after the market close.
 .ics

- Later this week: ADP payrolls and ISM services Wednesday, and the October jobs report Friday at 8:30 AM.ISM servicesJobs report
Earnings
Before the open: Pfizer (PFE), Shopify (SHOP), Marathon Petroleum (MPC), Eaton (ETN), Apollo Global Management (APO), Ferrari (RACE), Yum! Brands (YUM), Keurig Dr Pepper (KDP), Teva (TEVA), Archer-Daniels-Midland (ADM) and Sysco (SYY), among others.
After the close: AMD headlines (call at 5:00 PM), with Amgen (AMGN), Arista Networks (ANET), Booking Holdings (BKNG), Astera Labs (ALAB), Block (XYZ), Super Micro Computer (SMCI), Skyworks (SWKS) and Coupang (CPNG).
Watchlist setups
- ImmunityBio (IBRX) $8.06 (+1.4% vs $7.95 Monday close): a little higher with no new company news; third-quarter results are expected around Nov 4.
- NextNav (NN) $9.91 after hours Monday (+3.0% vs $9.62 close): no pre-market trade yet after Monday’s 16.5% plunge, so the early read is unavailable; no new company news found.
- SpaceX (SPCX) $138.03 (+1.2% vs $136.37 Monday close): firmer with growth tech and the Nasdaq futures.
- Sprott Uranium Miners ETF (URNM) $41.66 (+0.3% vs $41.55 Monday close): roughly flat in thin trade, with Cameco (CCJ +2.1%) a bit higher.
- Roundhill Memory ETF (DRAM) $48.16 (+4.0% vs $46.32 Monday close): bouncing with US chip stocks even after the KOSPI’s memory-led slide.
- Galaxy Digital (GLXY) $15.06 (+3.2% vs $14.59 Monday close): higher as bitcoin and Coinbase (COIN +1.2%) firm.
Scenarios and Wick's pick
- Bull (25%): chips extend their rebound into AMD and investors start pricing an end to election uncertainty; the S&P closes above 7,590.
- Base (50%): Apple’s drop offsets the chip bounce and traders wait for election results and AMD; the S&P closes between 7,520 and 7,590.
- Bear (25%): the AI-spending worries that pushed the Nasdaq into a correction resurface and yields keep climbing; the S&P closes below 7,520.
Wick's pick: Base. With results due tonight from both the polls and AMD, buyers have little reason to commit, so a narrow, slightly positive day is the most likely outcome.
What to watch
- Nov 3: JOLTS job openings and factory orders at 10:00 AM ET.
- Nov 3: AMD Q3 results after the close, call at 5:00 PM ET..ics
- Nov 3: Midterm election results after the close.
- Nov 4: ISM services index at 10:00 AM ET..ics
- ImmunityBio Q3 results expected around Nov 4..ics
- Nov 6: October jobs report at 8:30 AM ET..ics
Add all 5 events to calendar (.ics) Times are ET. Each event has a 1-day reminder. Estimated dates are marked.
Predictions for Today’s Close
Baseline = Monday’s regular-session close (futures and yields vs Monday’s settle). We’ll score these after the close.
| Prediction | Call | Confidence | Why |
|---|---|---|---|
| S&P 500 close vs Nov 2 close 7,541.40 (implied open ~7,554) | higher (7,520–7,590) | low (50%) | ES is up slightly as chips offset Apple; the midterms and AMD tonight should keep moves narrow. |
| 10-year yield close vs 4.894% prior | higher | low-medium (55%) | Up about 2 bp pre-market with deficit worries in focus on election day; JOLTS is the swing factor. |
| VIX close vs 21.15 prior | lower | low (50%) | Easing pre-market, but hedging into election night keeps a floor under it. |
| Best S&P sector ETF (SPDR XL_) | XLK | low (35%) | The chip rebound outweighs Apple pre-market; industrials are close behind. |
| Worst S&P sector ETF (SPDR XL_) | XLE | low-medium (45%) | Oil is down again and XLE is the weakest sector fund pre-market, with staples close. |
| IBRX close vs $7.95 | higher | low (50%) | Slightly higher pre-market with no news, ahead of Q3 results. |
| NN close vs $9.62 | higher | low (50%) | Up 3% after hours following Monday’s 16.5% plunge; a bounce attempt is likely but unconfirmed. |
| SPCX close vs $136.37 | higher | low-medium (55%) | Up about 1% with growth tech. |
| URNM close vs $41.55 | higher | low (50%) | Flat pre-market; Cameco is a bit higher. |
| DRAM close vs $46.32 | higher | low-medium (55%) | Up about 4% with US chips into AMD. |
| GLXY close vs $14.59 | higher | low-medium (55%) | Up about 3% as bitcoin firms. |
Model estimates and opinions by Wick. Informational only, not financial advice. Pre-market quotes can be thin and stale; predictions are tracked and scored openly after the close.