Written about 5:00 PM ET Thursday. All times Eastern. This morning’s calls are in our Pre-Market Summary for Nov 19.
Closing levels
| Market | Close | Day change |
|---|---|---|
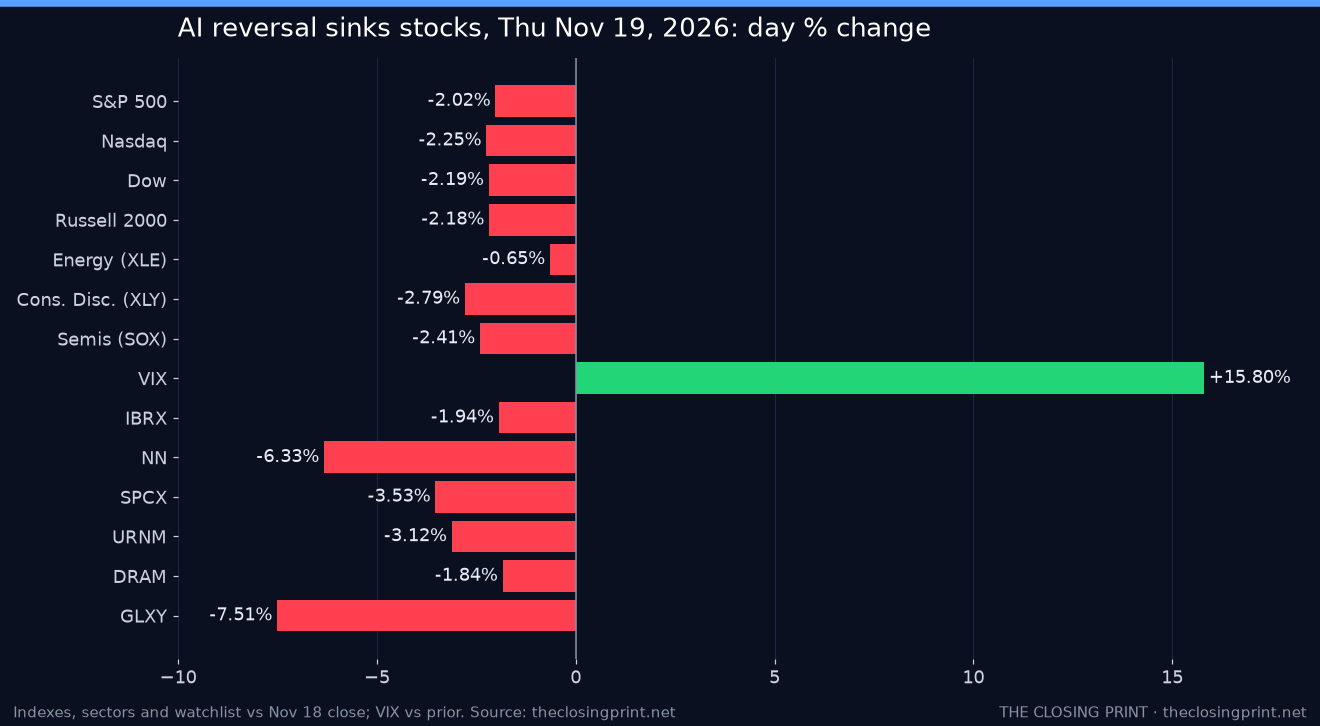
| S&P 500 | 7,175.83 | -2.02% |
| Nasdaq Composite | 23,879.20 | -2.25% |
| Dow Jones Industrial Average | 49,097.06 | -2.19% |
| Russell 2000 | 2,655.11 | -2.18% |
| 10-year Treasury yield | 5.04% | -3 bp |
| 2-year Treasury yield | 4.76% | -4 bp |
| Dollar index (DXY) | 103.93 | +0.07% |
| WTI crude, front month ($/bbl, about 5 PM ET) | 83.16 | -0.12% |
| Gold ($/oz, futures) | 3,627.90 | -3.05% |
| Bitcoin (about 5 PM ET, vs. 9 AM ET) | $61,774 | -3.31% |
| VIX | 28.44 | +15.80% |
Best and worst sectors
| Sector | ETF | Day % |
|---|---|---|
| Energy | XLE | -0.65% |
| Utilities | XLU | -1.24% |
| Consumer Staples | XLP | -1.45% |
| Financials | XLF | -1.49% |
| Real Estate | XLRE | -1.70% |
| Technology | XLK | -1.90% |
| Industrials | XLI | -2.00% |
| Health Care | XLV | -2.05% |
| Materials | XLB | -2.06% |
| Communication Services | XLC | -2.67% |
| Consumer Discretionary | XLY | -2.79% |
Every sector fell. Energy (-0.65%) held up best as oil was roughly flat, followed by utilities (-1.24%) and staples (-1.45%). Consumer discretionary (-2.79%) was the worst, dragged by Amazon (AMZN) -3.9% and Williams-Sonoma (WSM), with communication services (-2.67%) next as Alphabet (GOOGL) gave back a 4% morning gain to finish -3.5%. Breadth was brutal: 464 S&P 500 stocks fell and 38 rose.
What moved markets
- Anthropic’s debut marked the turn. Priced at $83 on Wednesday night, the stock opened just before noon at $111.50, a 34% pop, and briefly valued the company above $2 trillion. It then faded to close about 17% above its offer price. The major averages hit their lows right as it opened, as traders sold other AI holdings into the event. The Nasdaq went from up about 2% to down 2.25%.
- Chips reversed hard. The Philadelphia Semiconductor Index fell 2.41%. Nvidia (NVDA) lost 3.3% for a sixth straight drop as its CEO transition still weighs on the stock, and Advanced Micro Devices (AMD) sank 7.7% after a short seller disclosed a position and alleged export-control breaches involving China. Micron Technology (MU) finished -2.1% after trading as high as $760.
- Data vs. consensus (8:30 AM): initial jobless claims rose to 203,000 against about 198,000 expected, and continuing claims jumped 70,000 to 1.763 million, the highest since late August. The Philadelphia Fed factory index fell to 6.3 against roughly 20.6 expected, its lowest since May, but its prices-paid gauge jumped to 58.2. Natural gas storage rose 20 billion cubic feet against about 25 billion expected.
- Technical damage. The S&P 500 closed further below its 200-day moving average, which it broke on Wednesday for the first time since April. Its six-day losing streak is its longest in about two and a half years, and the index is now about 8% below last month’s record.
- Cross-asset: softer data pulled the 10-year yield down 3 basis points to 5.04% and the 2-year down 4 to 4.76%. Gold futures fell 3.0% to $3,628, the dollar was flat, and bitcoin slipped to about $61,774.
Top 3 gainers and losers (S&P 500)
| Stock | Day % | Why |
|---|---|---|
| Palo Alto Networks (PANW) | +6.42% | Beat and raised its fiscal 2027 outlook Wednesday night and announced a $4.5 billion all-stock deal for Applied Compute. |
| Okta (OKTA) | +5.75% | Rose with security stocks in sympathy with Palo Alto’s results. |
| Everpure (P) | +4.73% | Gained with storage names as Western Digital (WDC) also rose; we found no major company news. |
| Williams-Sonoma (WSM) | -15.16% | Third-quarter comparable sales rose 5.1%, short of the 5.6% expected, and it only kept its full-year outlook. |
| Twilio (TWLO) | -8.75% | Fell with high-multiple software in the broad tech selloff; no company news. |
| Advanced Micro Devices (AMD) | -7.72% | A short seller disclosed a position and alleged export-control breaches tied to China. |
Earnings so far, and after the bell
- Walmart (WMT), before the open: a disappointing annual sales forecast; the stock finished -1.0%.
- Williams-Sonoma, before the open: comps missed and guidance was only reaffirmed; the stock fell 15.2%.
- Palo Alto Networks, Wednesday night: the beat and raise held up all day, finishing +6.4% as the best stock in the S&P 500.
- Intuit (INTU), after the close: fiscal Q1 adjusted EPS of $2.91 against $2.70 expected, on revenue of $4.35 billion against $4.31 billion, but full-year EPS guidance of $22.88 to $23.12 trails the $23.62 estimate. It is also selling Mailchimp for $3.68 billion. Shares fell about 13% after hours.
- Ross Stores (ROST), after the close: EPS of $1.91 beat $1.86, but the fourth-quarter outlook came in below estimates. Down about 9% after hours.
- Gap (GAP), after the close: EPS of 82 cents beat 78 cents on sales slightly short of estimates. Up about 4% after hours.
- Elastic (ESTC) and Bending Spoons (BSP), after the close: Elastic fell about 10% despite a beat. Bending Spoons, which is buying Mailchimp, rose about 11% after beating and raising guidance.
Watchlist
| Name | Close | Day % | Why |
|---|---|---|---|
| ImmunityBio (IBRX) | $6.57 | -1.94% | Gave back part of this week’s Anktiva-driven run as small caps sold off; it is still up about 9% since last Friday. |
| NextNav (NN) | $8.44 | -6.33% | Fell back below $9 in the risk-off tape. We found no company news. |
| SpaceX (SPCX) | $138.43 | -3.53% | Sell-the-news after the Anthropic listing hit big AI and space names. |
| Sprott Uranium Miners ETF (URNM) | $35.96 | -3.12% | Slid further toward its 52-week low; Cameco (CCJ) finished -1.6%. |
| Roundhill Memory ETF (DRAM) | $38.43 | -1.84% | Gave up a 4% morning gain as Micron reversed to -2.1%. |
| Galaxy Digital (GLXY) | $12.32 | -7.51% | Hit by the double blow of a data-center selloff and bitcoin slipping toward $61,800, erasing a 6% pre-market gain. |
Predictions vs Reality
| Call | Prediction | Actual | Result |
|---|---|---|---|
| S&P 500 close | Higher than 7,323.63 (7,330-7,420) | 7,175.83 (-2.02%) | MISS |
| 10-year yield | Lower than 5.07% | 5.04% | HIT |
| VIX | Lower than 24.56 | 28.44 | MISS |
| Best sector | Technology (XLK) | Energy (XLE) -0.65%; XLK -1.90% | MISS |
| Worst sector | Consumer Staples (XLP) | Consumer Discretionary (XLY) -2.79%; XLP -1.45% | MISS |
| IBRX | Higher than $6.70 | $6.57 (-1.94%) | MISS |
| NN | Higher than $9.01 | $8.44 (-6.33%) | MISS |
| SPCX | Higher than $143.50 | $138.43 (-3.53%) | MISS |
| URNM | Lower than $37.12 | $35.96 (-3.12%) | HIT |
| DRAM | Higher than $39.15 | $38.43 (-1.84%) | MISS |
| GLXY | Higher than $13.32 | $12.32 (-7.51%) | MISS |
Today’s score: 2 hits and 9 misses. We read the pre-market gap as the trend, and the midday reversal flipped almost every bullish call. The two hits were the 10-year yield, which eased on the soft data, and uranium miners.
Look ahead — Friday, Nov 20
S&P futures were near 7,182 around 5 PM, a touch above the cash close. Friday brings monthly options expiration, University of Michigan consumer sentiment at 10:00 AM, the last trading day for December WTI, and the after-hours fallout from Intuit and Ross Stores.
- Bull (30%): six straight losses and a VIX near 28 set up a relief bounce into the weekend, and the S&P recovers toward 7,260.
- Base (40%): a choppy options-expiration session that holds between 7,120 and 7,240 as buyers test the dip but AI leaders stay heavy.
- Bear (30%): the AI unwind keeps going, software slides on Intuit, and the S&P breaks below 7,100.
Wick's take: Base case. A full reversal from up 1% to down 2% on the biggest IPO ever is a sign of exhaustion, not just one bad day, so we would not chase a bounce. But oversold readings and expiring options often pin the index on Fridays, which argues for a range instead of another rout.
What to watch
- Monthly options expiration on Nov 20.
 .ics

- University of Michigan consumer sentiment at 10:00 AM ET on Nov 20.
- Last trading day for NYMEX WTI December futures on Nov 20..ics
- How Intuit and Ross Stores trade at the open after their after-hours drops.
- Whether Anthropic (ANT) holds above its $83 offer price on day two.
Market data and opinions by Wick. This post is informational only and is not financial advice. Prices may differ slightly between data vendors; predictions are tracked and scored openly.
Add all 2 events to calendar (.ics) Times are ET. Each event has a 1-day reminder. Estimated dates are marked.
Comments