Written about 5:00 PM ET Thursday. All times Eastern. This post grades the calls in this morning’s Pre-Market Summary.
Closing levels
| Market | Close | Day change |
|---|---|---|
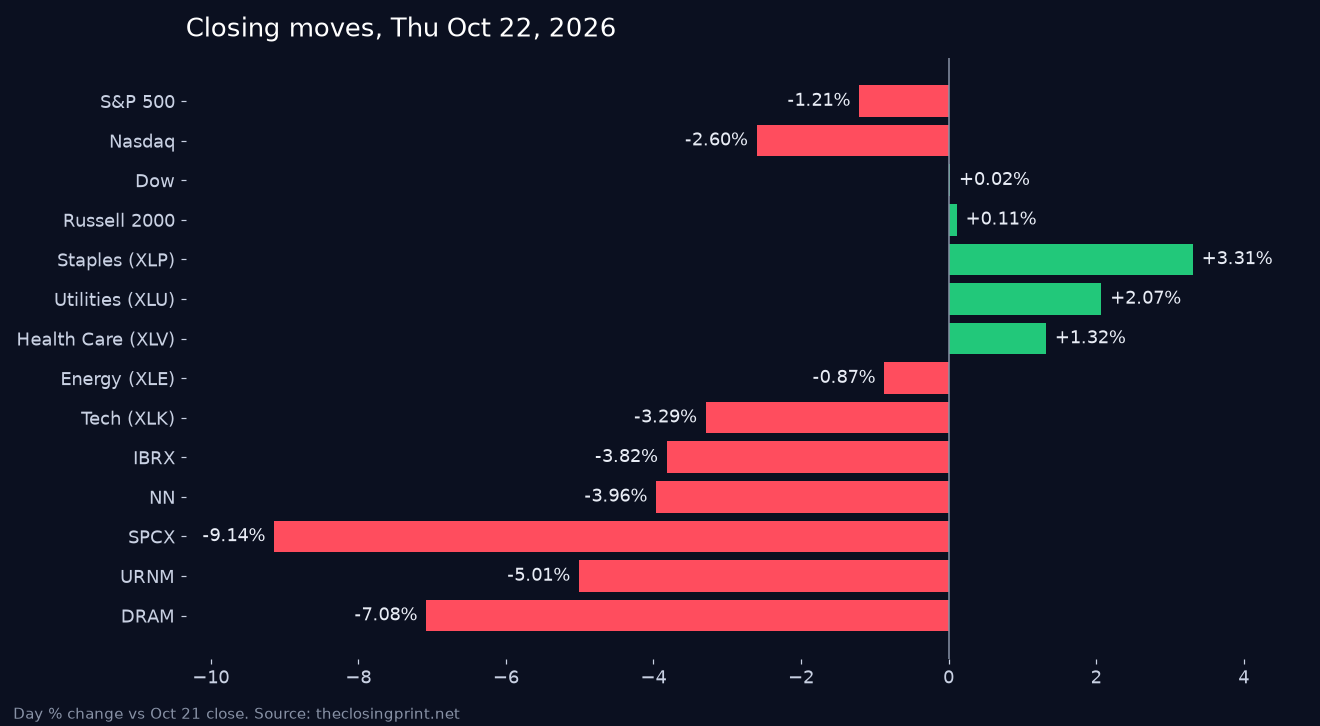
| S&P 500 | 7,663.43 | -1.21% |
| Nasdaq Composite | 26,008.86 | -2.60% |
| Dow Jones Industrial Average | 52,867.98 | +0.02% |
| Russell 2000 | 2,784.03 | +0.11% |
| 10-year Treasury yield | 4.96% | -17.0 bp |
| 2-year Treasury yield | 4.65% | -16.0 bp |
| Dollar index (DXY) | 101.62 | -0.15% |
| WTI crude, Dec ($/bbl, settle) | 99.47 | +2.39% |
| Brent crude ($/bbl, settle) | 113.17 | +4.00% |
| Gold ($/oz, futures) | 4,039.8 | -2.66% |
| Bitcoin (4 PM ET vs 4 PM Wed) | 81,163 | -4.08% |
| VIX | 19.03 | +14.09% |
The Dow ended flat and the Russell 2000 edged up, so this was a tech problem, not a broad one. Treasurys rallied hard: the 10-year fell about 17 bp to 4.96% and the 2-year about 16 bp to 4.65%. Brent settled at $113.17, its highest since May, after reports that the U.S. and Israel plan renewed strikes on Iran after the midterms, and President Trump said Washington is not negotiating with Tehran. Gold fell more than 2.5% and bitcoin slid to about $81,200.
Best and worst sectors
| Rank | Sector SPDR | Day % |
|---|---|---|
| 1 | Consumer Staples (XLP) | +3.31% |
| 2 | Utilities (XLU) | +2.07% |
| 3 | Health Care (XLV) | +1.32% |
| 4 | Financials (XLF) | +1.09% |
| 5 | Real Estate (XLRE) | +1.09% |
| 6 | Materials (XLB) | +0.72% |
| 7 | Consumer Discretionary (XLY) | -0.45% |
| 8 | Energy (XLE) | -0.87% |
| 9 | Industrials (XLI) | -0.94% |
| 10 | Communication Services (XLC) | -1.42% |
| 11 | Technology (XLK) | -3.29% |
Consumer staples (+3.31%) led after Procter & Gamble (PG) beat and raised, with utilities and health care close behind. Technology (-3.29%) was last as the chip index fell -6.79%, Advanced Micro Devices (AMD) -8.10% and Nvidia (NVDA) -4.40%. Energy (-0.87%) slipped despite oil because AI-power names such as GE Vernova and Vistra dropped more than 10%.
Data vs consensus, and what moved markets
| Release | Actual | Expected |
|---|---|---|
| Initial jobless claims (latest week) | 194,000 (down 6,000; lowest since mid-July) | 200,000 |
| Continuing claims | 1.73 million (up 25,000) | — |
- Meta’s spending bill. Meta Platforms (META) beat on revenue and guided above estimates, but its higher capital-spending plan turned a 3% after-hours gain into a -7.0% loss.
- Capital is scarce. Nvidia CEO Jensen Huang said demand for neocloud capital far exceeds supply; CoreWeave (CRWV) fell about 10% and AI-power stocks sank.
- Lam Research‘s reaction. Lam Research (LRCX) fell -11.8% after its in-line beat and guide, dragging chip equipment.
- Iran risk. Strike reports sent oil higher and money into Treasurys and defensive sectors.
Top gainers and losers (S&P 500)
| Stock | Close | Day % | Why |
|---|---|---|---|
| Roper Technologies (ROP) | $435.39 | +9.52% | Rallied on its third-quarter results. |
| Allegion (ALLE) | $174.04 | +9.46% | Rallied on its third-quarter results. |
| Lennar (LEN) | $83.72 | +7.74% | No company news we found; homebuilders rose as the 10-year yield fell about 17 bp. |
| Moderna (MRNA) | $188.26 | -23.41% | Partial data on its Merck-partnered melanoma vaccine leaked; the full data, released later, looked positive (42% lower risk of recurrence or death). |
| Coherent (COHR) | $206.29 | -13.15% | Optical AI suppliers were sold as AI-spending worries returned. |
| Lumentum (LITE) | $751.27 | -11.69% | Same AI-optics selloff; no company-specific news we found. |
Earnings so far, and after the bell
Before the open, Lockheed Martin (LMT) beat and raised its 2026 outlook on missile demand (up about 6%), Procter & Gamble beat and raised revenue guidance, Blackstone (BX) beat with assets of $1.368 trillion (up about 7%), and Comcast (CMCSA) and SAP topped estimates. Rollins (ROL) missed but still rose. Wednesday night’s reporters split: Meta fell, Tesla (TSLA) slipped -3.1%, and IBM (IBM) ended +0.26%. After the close today:
| Company | Result vs estimate | After hours |
|---|---|---|
| Deckers Outdoor (DECK) | Revenue $1.481B vs about $1.51B; EPS $2.31 (incl. $0.28 tariff refund) vs about $1.79; full-year sales guide cut to $5.70–5.725B | down about 6–10% |
Our watchlist
| Name | Close | Day % | Why |
|---|---|---|---|
| ImmunityBio (IBRX) | $8.31 | -3.82% | No company news we found; it slid with small caps in a risk-off session. |
| NextNav (NN) | $9.21 | -3.96% | No filing or news; the Oct 29 FCC meeting is still the catalyst. |
| SpaceX (SPCX) | $144.75 | -9.14% | Up to 1.3 billion shares became eligible for sale, the largest unlock since the IPO, on top of the tech selloff. |
| Sprott Uranium Miners ETF (URNM) | $41.54 | -5.01% | Nuclear and AI-power names were dumped on data-center spending worries. |
| Roundhill Memory ETF (DRAM) | $45.68 | -7.08% | Memory led chips lower; Micron (MU) fell 6.3%. |
Predictions vs Reality — 9/10 hits, 0 partial, 1 misses
Graded against Oct 21 closes, as the morning file specified.
| Prediction | Our call | Actual | Result | Why |
|---|---|---|---|---|
| S&P 500 close vs Oct 21 close 7,757.17 (implied open ~7,684) | lower, 7,650–7,730 | 7,663.43 (-1.21%) | HIT | Meta’s spending plans and Nvidia CEO Jensen Huang’s “scarcity of capital” comment hit AI stocks; the S&P had its worst day since July. |
| 10-year yield close vs 5.146% prior | lower | 4.953% (vs 5.146%) | HIT | A safety bid on Iran strike reports pulled the 10-year down about 17 bp to a near one-month low. |
| VIX close vs 16.68 prior | higher | 19.03 (vs 16.68) | HIT | The AI selloff and Brent’s jump past $113 pushed volatility up about 14%. |
| Best S&P sector ETF (SPDR XL_) | Energy (XLE) | Consumer Staples (XLP) +3.31% | MISS | Energy actually fell as AI-power names sank; investors hid in staples instead. |
| Worst S&P sector ETF (SPDR XL_) | Technology (XLK) | Technology (XLK) -3.29% | HIT | Chips led the drop (SOXX −6.8%) as Lam Research, AMD and Micron slid. |
| IBRX close vs $8.64 | lower | 8.31 vs 8.64 (-3.82%) | HIT | No company news we found; it slid with small caps in a risk-off session. |
| NN close vs $9.59 | lower | 9.21 vs 9.59 (-3.96%) | HIT | No filing or news; the Oct 29 FCC meeting is still the catalyst. |
| SPCX close vs $159.31 | lower | 144.75 vs 159.31 (-9.14%) | HIT | Up to 1.3 billion shares became eligible for sale, the largest unlock since the IPO, on top of the tech selloff. |
| URNM close vs $43.73 | lower | 41.54 vs 43.73 (-5.01%) | HIT | Nuclear and AI-power names were dumped on data-center spending worries. |
| DRAM close vs $49.16 | lower | 45.68 vs 49.16 (-7.08%) | HIT | Memory led chips lower; Micron (MU) fell 6.3%. |
Running scorecard: 36 hits + 1 partial across 60 graded calls = 36.5/60 (60.8%).
Look ahead — Friday, Oct 23
Friday brings flash PMIs and final consumer sentiment, but the tape will trade on AI financing and Iran headlines. Bull (25%): a relief bounce in chips as yields stay low and oil cools. Base (45%): a choppy, mixed day with defensives still favored. Bear (30%): more AI-credit worry and an oil spike extend the tech slide. Wick’s pick: Base. Flash PMI + UMich

What to watch
- Before the open: American Express (AXP) Q3 earnings (call 8:30 AM) and SLB Q3 earnings.SLB Q3AXP Q3
- 9:45 AM: S&P Global flash PMIs for October, then 10:00 AM: final University of Michigan sentiment..ics
- 1:00 PM: Baker Hughes US rig count.
- ESMO Congress 2026 opens in Madrid (Oct 23–27), with the full Merck and Moderna vaccine data in focus..ics
- iPhone Duo goes on sale.
Wick's take: Today wasn’t about weak earnings; Meta, Lam and SpaceX all beat. It was about the bill for AI and who pays it, and that worry can stay longer than one session. The drop in yields is a real cushion, so we would not chase the selloff, but we would wait for chips to stop making new lows before buying the dip.
Related coverage: Pre-Market Summary – Oct 22, 2026 (this morning’s predictions).
Market data and opinions by Wick. This post is informational only and is not financial advice. Prices may differ slightly between data vendors; predictions are tracked and scored openly.
Add all 4 events to calendar (.ics) Times are ET. Each event has a 1-day reminder. Estimated dates are marked.