Written about 9:00 AM ET Thursday, before the opening bell. All times Eastern; quotes as of about 9:00 AM ET.
Markets at about 9:00 AM ET
| Market | Level | Change |
|---|---|---|
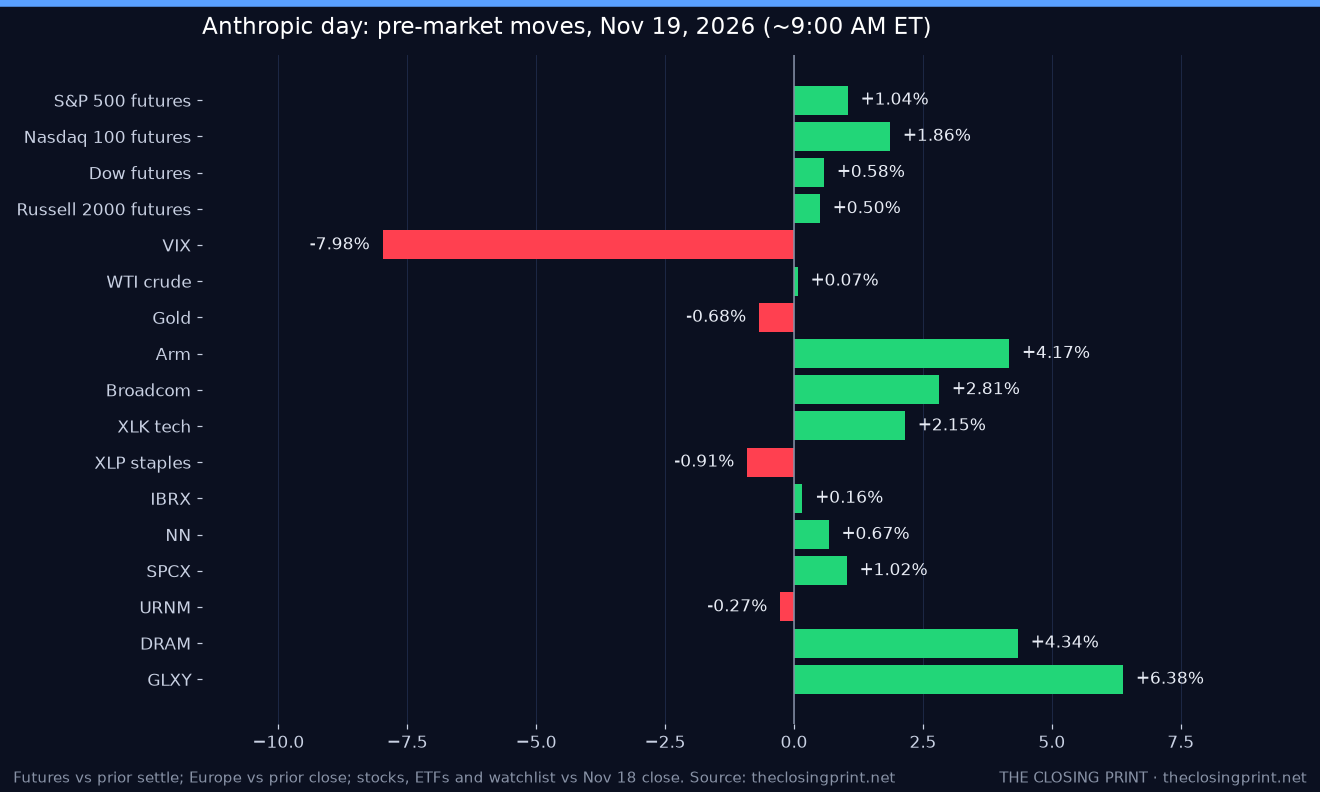
| S&P 500 futures | 7,417.00 | +1.04% |
| Nasdaq 100 futures | 27,691.50 | +1.86% |
| Dow futures | 50,563.00 | +0.58% |
| Russell 2000 futures | 2,735.70 | +0.50% |
| 10-year Treasury yield | 5.08% | +1 bp vs 5.07% Nov 18 close |
| 2-year Treasury yield | 4.80% (Nov 18 close) | live quote unavailable |
| US Dollar Index (DXY) | 103.66 | -0.19% |
| WTI crude ($/bbl) | $83.32 | +0.07% |
| Gold ($/oz) | $3,716 | -0.68% |
| Bitcoin | $63,892 | +0.04% (24h) |
| VIX | 22.60 | -7.98% |
| Nikkei 225 (close) | 59,444.21 | +0.71% |
| Hang Seng (close) | 22,841.62 | -1.95% |
| KOSPI (close) | 5,137.89 | +1.39% |
| Shanghai Composite (close) | 3,577.62 | -0.28% |
| Euro Stoxx 50 | 6,171.32 | +0.28% |
| DAX | 25,725 | -0.04% |
| FTSE 100 | 10,525 | -0.25% |
| CAC 40 | 8,143 | -0.05% |
Futures vs prior settle; Asia closes are today’s sessions vs prior close; Europe live vs prior close; VIX vs Nov 18 close. A live 2-year Treasury quote was unavailable at writing.
What’s moving before the bell
Anthropic goes public. Anthropic priced its IPO at $83 a share, well above earlier guidance, valuing the company at about $1.5 trillion. It is the largest IPO ever by value of shares sold and begins trading on the Nasdaq today. The valuation is still about 25% below what was floated a couple of months ago, a sign of how much the AI trade has cooled since early October.
Chips and cybersecurity lead. Palo Alto Networks (PANW) is jumping after revenue beat estimates and it raised its annual forecast. It also agreed to pay $4.5 billion for an AI startup founded last year by former OpenAI researchers. Other cybersecurity names are rallying with it. Chips are strong: Arm Holdings (ARM) +4.2%, Broadcom (AVGO) +2.8%, AMD +2.0% and CoreWeave (CRWV) +5.0%. Alphabet (GOOGL) is +4.0% and Nvidia (NVDA) +1.2%.
Walmart raises, but slips. Walmart (WMT) reported third-quarter revenue up 5.2% to $188.8 billion, with global e-commerce up 17%, and raised its fiscal 2027 outlook. The stock is still lower before the bell, which drags on consumer staples.
Data and the Fed. Jobless claims rose to 203,000, above the 197,000 expected, and continuing claims jumped 70,000 to 1.763 million, the highest since late August. The Philadelphia Fed factory index fell to 6.3 from 20.9, its lowest in six months, though prices paid jumped to 58.2. Minutes of the October Fed meeting showed most officials favor more rate hikes, some by half a point, and Governor Christopher Waller repeated his call for a 50 basis-point hike. The 10-year yield is near 5.08%, about flat.
Dollar, commodities and crypto. The dollar index is -0.19%, gold is -0.7% near $3,716, and WTI crude is about flat at $83.32. Bitcoin is flat near $63,892, while Coinbase (COIN) is +3.5% and Robinhood (HOOD) +4.2%.
Overseas: Asia was mixed. The Nikkei rose 0.7% and the KOSPI 1.4%, while the Hang Seng fell 2.0%. Europe is little changed, with the Euro Stoxx 50 +0.3% and the FTSE 100 -0.2%. The APEC summit continues in Shenzhen.
Economic calendar and Fed (ET)
- 8:30 AM (released): Weekly jobless claims 203,000 vs 197,000 expected; continuing claims 1.763 million.
 .ics

- 8:30 AM (released): November Philadelphia Fed manufacturing index 6.3, down from 20.9.
- Later today: Kansas City Fed November manufacturing survey and a $19 billion 10-year TIPS auction (exact times not confirmed at writing).
- Fed speakers: Vice Chair Philip Jefferson, Governor Michael Barr, Richmond Fed President Thomas Barkin, Philadelphia Fed President Anna Paulson, Chicago Fed President Austan Goolsbee and Cleveland Fed President Beth Hammack. Speaking times were not confirmed at writing. ECB President Christine Lagarde also speaks.
Earnings
Before the open: Walmart (WMT), Alibaba Group (BABA), PDD Holdings (PDD), NetEase (NTES), Williams-Sonoma (WSM), Warner Music Group (WMG), Futu Holdings (FUTU), Bath & Body Works (BBWI) and Valvoline (VVV).
After the close: Intuit (INTU), Ross Stores (ROST), Keysight Technologies (KEYS), Elastic (ESTC), Gap (GAP), Webull (BULL) and Globant (GLOB).
Watchlist setups
- ImmunityBio (IBRX) $6.71 (+0.2% vs prior close): flat pre-market after a strong week; it was named the No. 2 fastest-growing tech company in North America on Deloitte’s Fast 500 list this morning. Holding $6.50 keeps the trend intact.
- NextNav (NN) $9.07 (+0.7% vs prior close): edging higher in light trade; staying above $9 is the level that matters.
- SpaceX (SPCX) $144.97 (+1.0% vs prior close): firmer as Anthropic, the other giant AI listing of the year, starts trading; renewed talk of a Tesla–SpaceX merger adds interest.
- Sprott Uranium Miners ETF (URNM) $37.02 (-0.3% vs prior close): slightly lower near its 52-week low; it is still not joining the tech rally.
- Roundhill Memory ETF (DRAM) $40.85 (+4.3% vs prior close): one of the strongest names on the list, up about 4% as chip stocks rally ahead of the Anthropic debut.
- Galaxy Digital (GLXY) $14.17 (+6.4% vs prior close): up about 6% with crypto brokers and data-center names, even with bitcoin flat near $63,900.
Scenarios and Wick's pick
- Bull (30%): Anthropic trades well, chips keep running and the S&P closes above 7,420.
- Base (50%): tech leads, but hawkish Fed talk and a weak Walmart keep a lid on it; the S&P closes 7,330–7,420.
- Bear (20%): Anthropic is a sell-the-news event, yields rise on hot price data and the S&P closes below 7,330.
Wick's pick: Base. Futures are pricing a strong open, but the Fed is talking about bigger hikes and the jobs data is softening, so buyers are likely to take some profit into the afternoon.
Predictions for today’s close
| Prediction | Call | Confidence | Why |
|---|---|---|---|
| S&P 500 close vs Nov 18 close 7,323.63 (implied open ~7,400) | higher (7,330–7,420) | medium (55%) | Futures are up about 1% on Palo Alto’s beat and the Anthropic debut, but a hawkish Fed and softer jobs data can trim the gain. |
| 10-year yield vs Nov 18 close (5.07%) | lower | low (50%) | Higher continuing claims and a weak Philly Fed point to softer growth, though hot prices-paid readings and hawkish Fed talk cut the other way. |
| VIX close vs 24.56 prior | lower | medium (60%) | The VIX is already down about 8% pre-market with futures firmly higher. |
| Best S&P sector ETF (SPDR XL_) | XLK | low (40%) | Tech leads pre-market at about +2% as chips and cybersecurity rally. |
| Worst S&P sector ETF (SPDR XL_) | XLP | low (35%) | Staples are the weakest sector pre-market, with Walmart lower after earnings. |
| IBRX close vs $6.70 | higher | low (50%) | Little changed pre-market but still carrying this week’s Anktiva momentum. |
| NN close vs $9.01 | higher | low (50%) | Slightly higher in thin trade, holding above $9. |
| SPCX close vs $143.50 | higher | low-medium (55%) | The Anthropic debut keeps attention on large AI and space names, though a sell-the-news turn is possible. |
| URNM close vs $37.12 | lower | low (50%) | Still near its 52-week low and slightly lower while tech leads. |
| DRAM close vs $39.15 | higher | medium (60%) | Memory makers are up about 4% pre-market with the chip rally. |
| GLXY close vs $13.32 | higher | low-medium (55%) | Up about 6% pre-market with data-center and crypto-linked stocks, though bitcoin is flat near $64,000. |
What to watch
- Nov 19, 9:30 AM ET: Opening bell; watch whether the chip rally broadens..ics
- Nov 19, 12:00 PM ET: Anthropic expected to open on the Nasdaq (exact time not confirmed)..ics
- Nov 19, after the close: Intuit Q1 earnings, with Ross Stores and Keysight..ics
- Nov 20: Monthly options expiration..ics
Add all 5 events to calendar (.ics) Times are ET. Each event has a 1-day reminder. Estimated dates are marked.
Not financial advice. Model estimates and opinions by Wick, for information only. Pre-market quotes can be thin and stale, and predictions are tracked and scored openly after the close.
Comments