Written about 5:00 PM ET Thursday. All times Eastern. This post grades the calls in this morning’s Pre-Market Summary.
Closing levels
| Market | Close | Day change |
|---|---|---|
| S&P 500 | 7,592.40 | -0.35% |
| Nasdaq Composite | 25,366.09 | -0.39% |
| Dow Jones Industrial Average | 52,297.09 | -0.36% |
| Russell 2000 | 2,799.06 | -1.66% |
| 10-year Treasury yield (change since Nov 10; bonds were closed Wednesday) | 5.10% | +12 bp |
| 2-year Treasury yield (change since Nov 10) | 4.86% | +13 bp |
| Dollar index (DXY) | 103.19 | +0.27% |
| WTI crude, front month ($/bbl) | 88.70 | +2.51% |
| Brent crude ($/bbl) | 95.77 | +3.24% |
| Gold ($/oz, futures) | 3,881.70 | -2.97% |
| Bitcoin (about 5:15 PM ET, vs. about 5 PM ET Wednesday) | $71,303 | -3.60% |
| VIX | 18.70 | +6.92% |
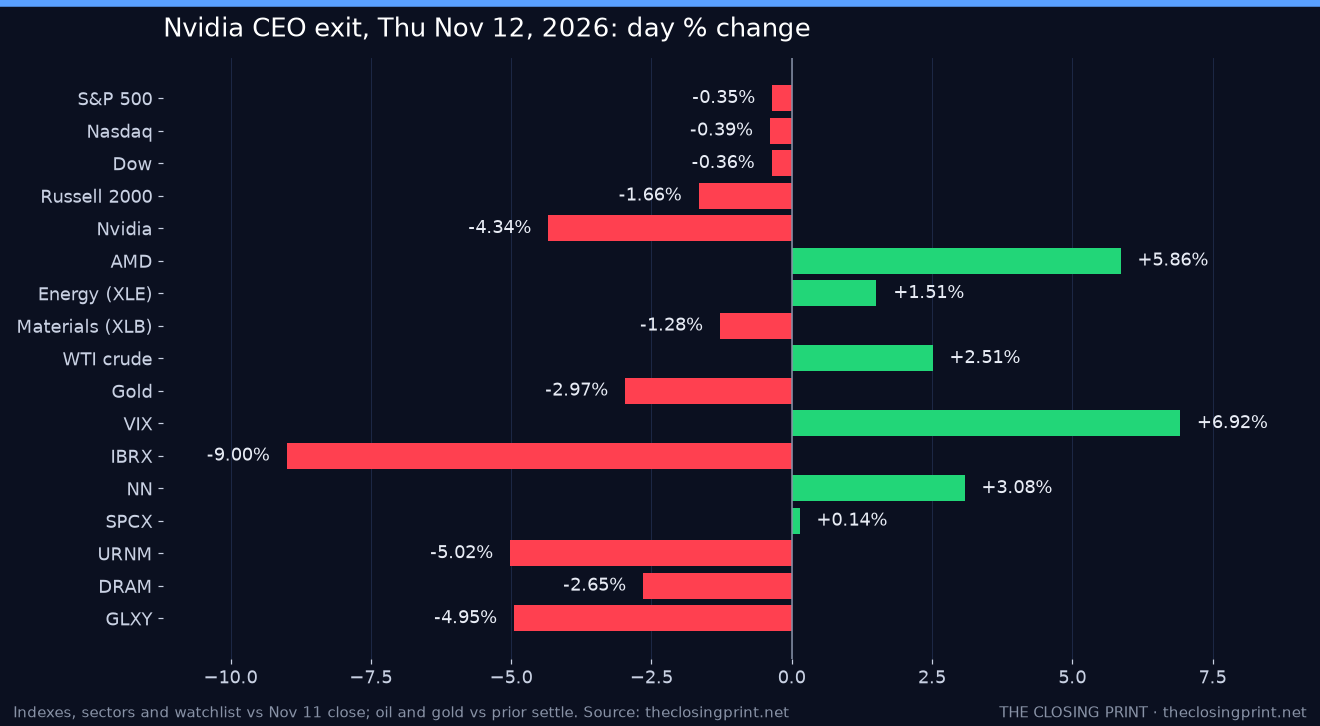
Nvidia announced that co-founder Jensen Huang resigned as CEO and director, with CFO Colette Kress stepping in as interim CEO and Harvey Jones named the board’s first chair. The selloff was violent at the open, but retail buyers piled in and the stock recovered most of the drop on volume of more than 730 million shares, roughly five times normal. Money rotated toward Nvidia’s rivals instead of leaving AI altogether: Advanced Micro Devices (AMD) and Broadcom (AVGO) were the S&P 500’s best performers. Under the surface the day was weaker than the index suggests, with only 124 S&P 500 stocks up and 378 down, and the Russell 2000 fell 1.7%. The VIX rose 7% to 18.70.
Best and worst sectors
| Sector | ETF | Day % |
|---|---|---|
| Energy | XLE | +1.51% |
| Utilities | XLU | -0.02% |
| Technology | XLK | -0.34% |
| Consumer Staples | XLP | -0.43% |
| Consumer Discretionary | XLY | -0.44% |
| Real Estate | XLRE | -0.52% |
| Health Care | XLV | -0.59% |
| Financials | XLF | -0.72% |
| Industrials | XLI | -0.89% |
| Communication Services | XLC | -0.96% |
| Materials | XLB | -1.28% |
Energy (+1.51%) was the only sector that gained meaningfully, its fourth straight up day, as crude rallied. Utilities (-0.02%) were flat, and technology (-0.34%) held up far better than feared because AMD and Broadcom offset Nvidia. Materials (-1.28%) finished last, dragged down by Corteva’s 24% plunge, with communication services and industrials close behind.
The data and what moved markets
- Jobless claims: 200,000 vs. 194,000 expected. Claims rose 9,000 from the prior week, a slightly softer labor market than forecast.
- October existing home sales: 3.75 million vs. about 3.85 million expected. Sales fell 5.5% from September to a 16-year low as mortgage rates track Treasury yields higher.
- A weak 30-year bond auction. The $25 billion sale cleared at 5.441% with a bid-to-cover ratio of 2.36, below the recent average of 2.45, and bonds stayed near their lows afterward.
- Hawkish Fed speakers. Cleveland’s Beth Hammack, Chicago’s Austan Goolsbee and San Francisco’s Mary Daly said they favor more rate hikes, which pushed the 10-year to a three-week high near 5.13% during the day.
- Oil up, gold down. WTI rose 2.5% after President Trump said the U.S. doesn’t need a deal with Iran, while gold fell about 3% and closed under $3,900.
Top gainers and losers (S&P 500)
| Stock | Close | Day % | Why |
|---|---|---|---|
| Advanced Micro Devices (AMD) | $585.30 | +5.86% | The biggest beneficiary of the rotation out of Nvidia, as buyers looked for other ways to own AI chips. |
| Broadcom (AVGO) | $364.36 | +5.54% | Its custom AI chips are the main alternative to Nvidia’s, so it caught the same rotation. |
| Arista Networks (ANET) | $206.63 | +5.06% | Data-center networking names rose with AMD and Broadcom as money stayed in AI but spread beyond Nvidia. |
| Corteva (CTVA) | $9.19 | -24.30% | Missed third-quarter estimates and cut its full-year outlook on a much weaker Brazil market; it is also being dropped from the MSCI USA Index. |
| Global Payments (GPN) | $88.19 | -12.01% | Reports said private-equity firms CD&R and GTCR dropped their talks to take the company private, erasing the buyout premium. |
| Super Micro Computer (SMCI) | $26.99 | -11.30% | The AI server maker depends heavily on Nvidia chips and sold off hard with it on the leadership shake-up. |
Earnings so far, and after the bell
During the session: Corteva’s miss was the biggest earnings reaction in the S&P 500. Among AI cloud names, Nebius (NBIS) tumbled about 17% after its quarterly results and outlook, and CoreWeave (CRWV) gave back about 7% of Wednesday’s surge.
After the close: Cisco (CSCO) rose about 3% in extended trading after beating on fiscal first-quarter profit ($1.40 a share vs. $1.32 expected) and revenue ($18.5 billion vs. $18.11 billion) and raising its full-year outlook on AI data-center switching demand. Applied Materials (AMAT) also beat ($4.16 vs. $4.06 a share, revenue $10.41 billion) and guided above forecasts, but the stock traded choppily after hours. Cerebras Systems (CBRS) jumped about 12% after a revenue beat and a sharply higher outlook.
Our watchlist
| Name | Close | Day % | Why today |
|---|---|---|---|
| ImmunityBio (IBRX) | $6.07 | -9.00% | Extended its post-earnings slide as investors are still weighing Monday’s revenue miss, the wider loss and funding needs. |
| NextNav (NN) | $8.71 | +3.08% | Bucked the weak tape and recovered Wednesday’s faded gain; we found no new company news. |
| SpaceX (SPCX) | $139.94 | +0.14% | Essentially flat, holding steady ahead of Friday’s planned Starship launch while chip stocks swung. |
| Sprott Uranium Miners ETF (URNM) | $40.27 | -5.02% | AI-power plays sold off with Nvidia’s leadership news; Cameco (CCJ) closed -3.4%. |
| Roundhill Memory ETF (DRAM) | $43.66 | -2.65% | Memory lagged the AMD and Broadcom bounce, with Micron (MU) -1.6% and Sandisk (SNDK) -4.1%. |
| Galaxy Digital (GLXY) | $15.18 | -4.95% | Hit from both sides: bitcoin fell about 3.6% and AI data-center names such as CoreWeave sold off. |
Predictions vs Reality — 9/11 hits, 0 partial, 2 misses
Graded against Nov 11 closes (the 10-year against its 4.998% reference). Sectors are ranked by SPDR sector ETF day change.
| Prediction | Our call | Actual | Result | Why |
|---|---|---|---|---|
| S&P 500 close vs Nov 11 close 7,619.38 | lower, 7,540–7,610 | 7,592.40 (-0.35%) | HIT | Lower and inside our range after a big intraday recovery. |
| 10-year yield vs about 5.00% | higher | 5.103% (vs 4.998%) | HIT | A weak 30-year auction and hawkish Fed talk pushed yields up. |
| VIX close vs 17.49 prior | higher | 18.70 (vs 17.49) | HIT | Hedging demand rose with the Nvidia shock. |
| Best S&P sector ETF (SPDR XL_) | Energy (XLE) | Energy (XLE) +1.51% | HIT | Oil’s rally kept energy on top. |
| Worst S&P sector ETF (SPDR XL_) | Technology (XLK) | Materials (XLB) -1.28%; XLK -0.34% | MISS | AMD and Broadcom rescued tech; Corteva sank materials. |
| IBRX close vs $6.67 | lower | 6.07 vs 6.67 (-9.00%) | HIT | The post-earnings slide continued. |
| NN close vs $8.45 | lower | 8.71 vs 8.45 (+3.08%) | MISS | It rallied against the tape. |
| SPCX close vs $139.75 | higher | 139.94 vs 139.75 (+0.14%) | HIT | It edged up by a hair. |
| URNM close vs $42.40 | lower | 40.27 vs 42.40 (-5.02%) | HIT | AI-power names sold off. |
| DRAM close vs $44.85 | lower | 43.66 vs 44.85 (-2.65%) | HIT | Memory stayed weak. |
| GLXY close vs $15.97 | lower | 15.18 vs 15.97 (-4.95%) | HIT | Bitcoin and AI data centers both fell. |
We had the shape of the day right: a lower S&P inside our range, higher yields, a higher VIX and energy on top. We missed on technology as the worst sector, because AMD and Broadcom offset Nvidia, and on NextNav, which rallied. Running scorecard: 147 hits + 3 partial across 212 graded calls = 148.5/212 (70.0%).
Look ahead — Friday, Nov 13
October producer prices at 8:30 AM ET are the big test, with forecasts calling for a 0.4% rise in headline PPI and 0.3% in the core measure after September’s hot readings. S&P futures were near 7,622 late this afternoon, and Cisco’s beat gives tech a modest tailwind into the open. Bull (30%): PPI comes in at or below forecasts, yields ease back under 5.05% and the S&P climbs back above 7,620. Base (45%): an in-line report and a choppy session between 7,550 and 7,630 as Nvidia keeps steadying. Bear (25%): a hot PPI pushes the 10-year toward 5.2% and the S&P breaks below 7,550. Wick's pick: Base.
What to watch
- October PPI at 8:30 AM ET on Nov 13.
 .ics

- Nvidia earnings on Nov 17..ics
- FOMC minutes at 2:00 PM ET on Nov 18..ics
- FOMC rate decision at 2:00 PM ET on Dec 9.
Wick's take: The market passed a real stress test today. Losing the face of its most important company knocked Nvidia down 14% at the open, and the S&P still finished down less than half a percent because the money moved to AMD and Broadcom rather than out of stocks. The bigger worry is the bond market: a sloppy 30-year auction and three Fed officials leaning toward more hikes put the 10-year back above 5.1%. We think rates, not Nvidia’s succession, decide the next leg, so tomorrow’s PPI matters more than any headline out of Santa Clara.
Market data and opinions by Wick. This post is informational only and is not financial advice. Prices may differ slightly between data vendors; predictions are tracked and scored openly.
Add all 3 events to calendar (.ics) Times are ET. Each event has a 1-day reminder. Estimated dates are marked.
Comments