Written about 6:30 PM ET Sunday, after the futures open. All times Eastern.
How the futures opened
| Market | Sunday, about 6:30 PM ET | Friday close (5 PM ET) | Change |
|---|---|---|---|
| S&P 500 futures (ES, Dec) | 7,411.25 | 7,402.00 | +0.12% |
| Nasdaq-100 futures (NQ, Dec) | 27,136.25 | 27,085.25 | +0.19% |
| Dow futures (YM, Dec) | 51,514 | 51,385 | +0.25% |
| Russell 2000 futures (RTY, Dec) | 2,767.00 | 2,760.50 | +0.24% |
| 10-year Treasury note futures (ZN, Dec) | 107-04 | 107-03½ | +0.01% (yield little changed) |
| WTI crude, Dec ($/bbl) | 90.25 | 90.83 | -0.64% |
| Brent crude, next contract ($/bbl) | 97.38 | 98.32 | -0.96% |
| Gold, Dec ($/oz) | 4,076.8 | 4,074.9 | +0.05% |
| Bitcoin | $75,150 | $75,950 | -1.05% |
| Dollar index (DXY) | 102.25 | 102.28 | -0.03% |
| Dollar vs yen (USD/JPY) | 158.36 | 158.43 | -0.04% |
| S&P/ASX 200 (Sydney, just opened) | 9,037 | 9,021 | +0.18% |
| Nikkei futures (CME, Dec, yen) | 58,435 | 58,235 | +0.34% |
| Nikkei 225, KOSPI, Hang Seng cash | not open yet when we wrote this | unavailable |
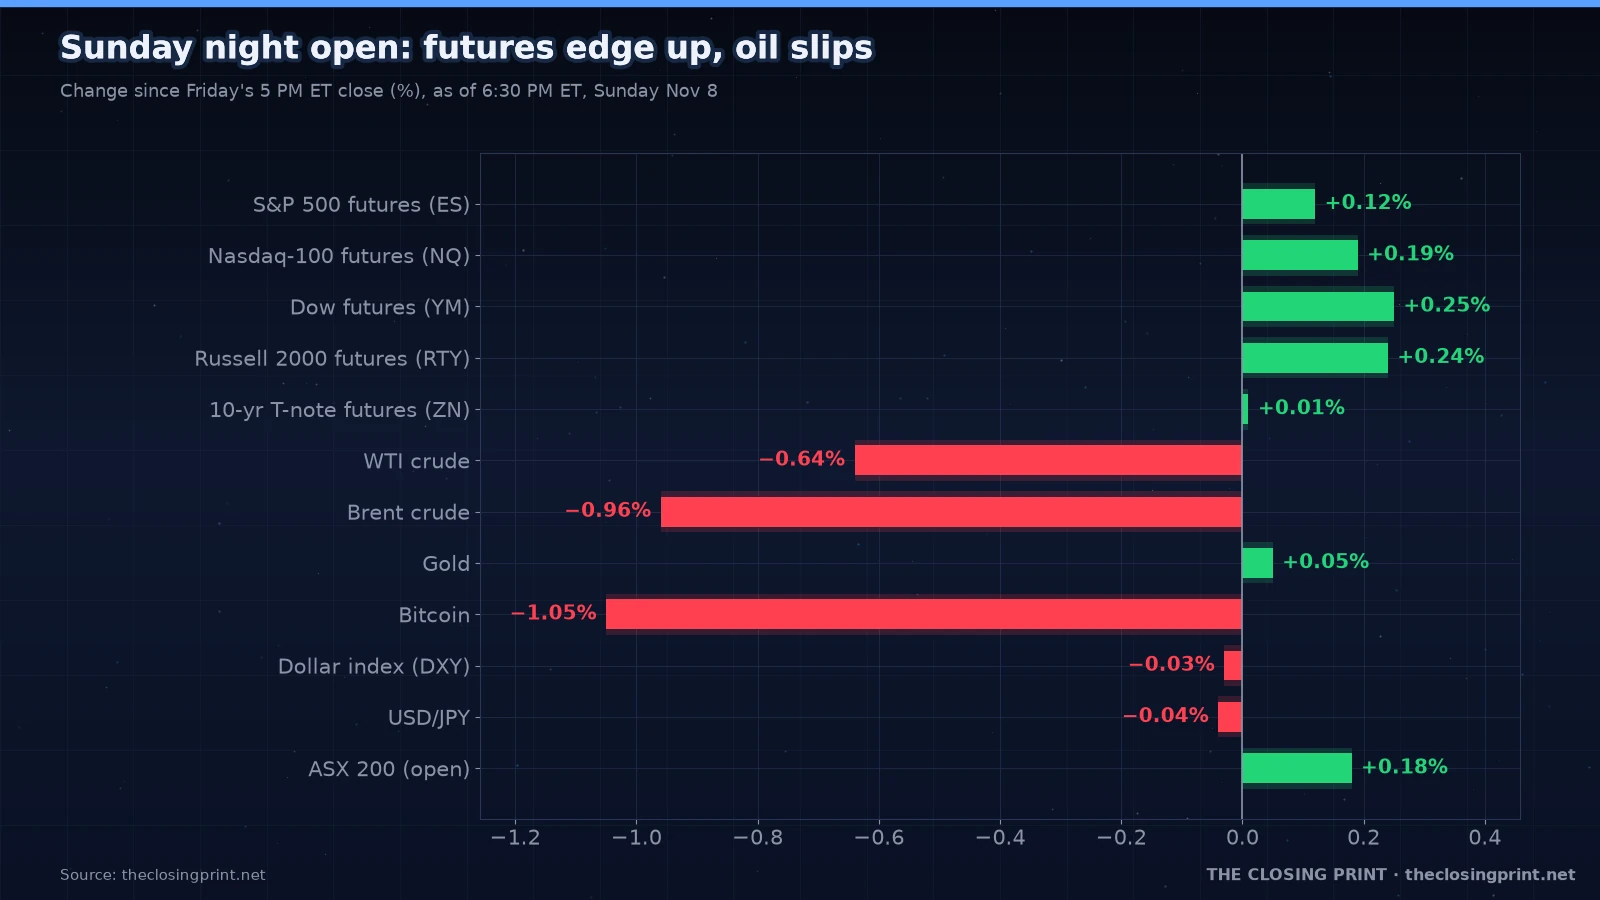
Last week was rough: the S&P 500 fell 2.7% and the Nasdaq 3.4%, with Thursday’s chip rout the worst day since April 2025 and Friday’s bounce only partial. Tonight’s open is calm. The Dow and Russell 2000 futures are up about a quarter of a percent, the S&P 500 about a tenth and the Nasdaq-100 about two tenths. Oil is drifting lower again after a 13% weekly drop in WTI: WTI is down about 0.6% to $90.25, and the next Brent contract is down about 1.0% to $97.38. Gold is flat near $4,077, and bitcoin is down about 1.1% to roughly $75,150. Treasury futures are flat, so the 10-year yield sits near Friday’s 4.86%. The dollar index is unchanged near 102.25, and the yen is steady at about 158.4 per dollar.
Asia: Sydney’s ASX 200 opened about 0.2% higher and New Zealand was flat. Tokyo, Seoul and Hong Kong hadn’t opened when we wrote this; CME Nikkei futures near 58,435 point to a Tokyo open somewhat above Friday’s 57,435 close, after memory stocks dragged Japan and Korea down hard last week. Our Friday post-market and weekly summary has the full U.S. close.
What drove the open
- Nvidia’s board opened a probe into its CEO. Nvidia (NVDA) said Sunday that its board is investigating co-founder and CEO Jensen Huang’s relationship with a businesswoman whom U.S. intelligence agencies describe as a Chinese spy. Off-hours trading in an Nvidia proxy was down about 2% over the past day, so it’s the main single-stock risk for Monday’s open, but index futures shrugged it off.
- Dip buying after the AI rout. Thursday brought the heaviest retail selling since the pandemic, and the Nasdaq-100 is oversold. Tonight’s small bid looks like traders testing a bounce, not a change in the story: worries about AI spending, data-center financing and the margins behind them haven’t gone away.
- Fallout from the midterms. Democrats’ sweep of Congress, plus wins for candidates and ballot measures that would restrict data-center building, still hangs over chips, power and electrical-equipment names.
- Rate-hike odds. After Friday’s stronger-than-expected jobs data, futures markets were pricing roughly 78% odds of a quarter-point Fed hike in December as of Sunday, which makes Tuesday’s CPI the week’s main event.
The next five days: data, the Fed and earnings
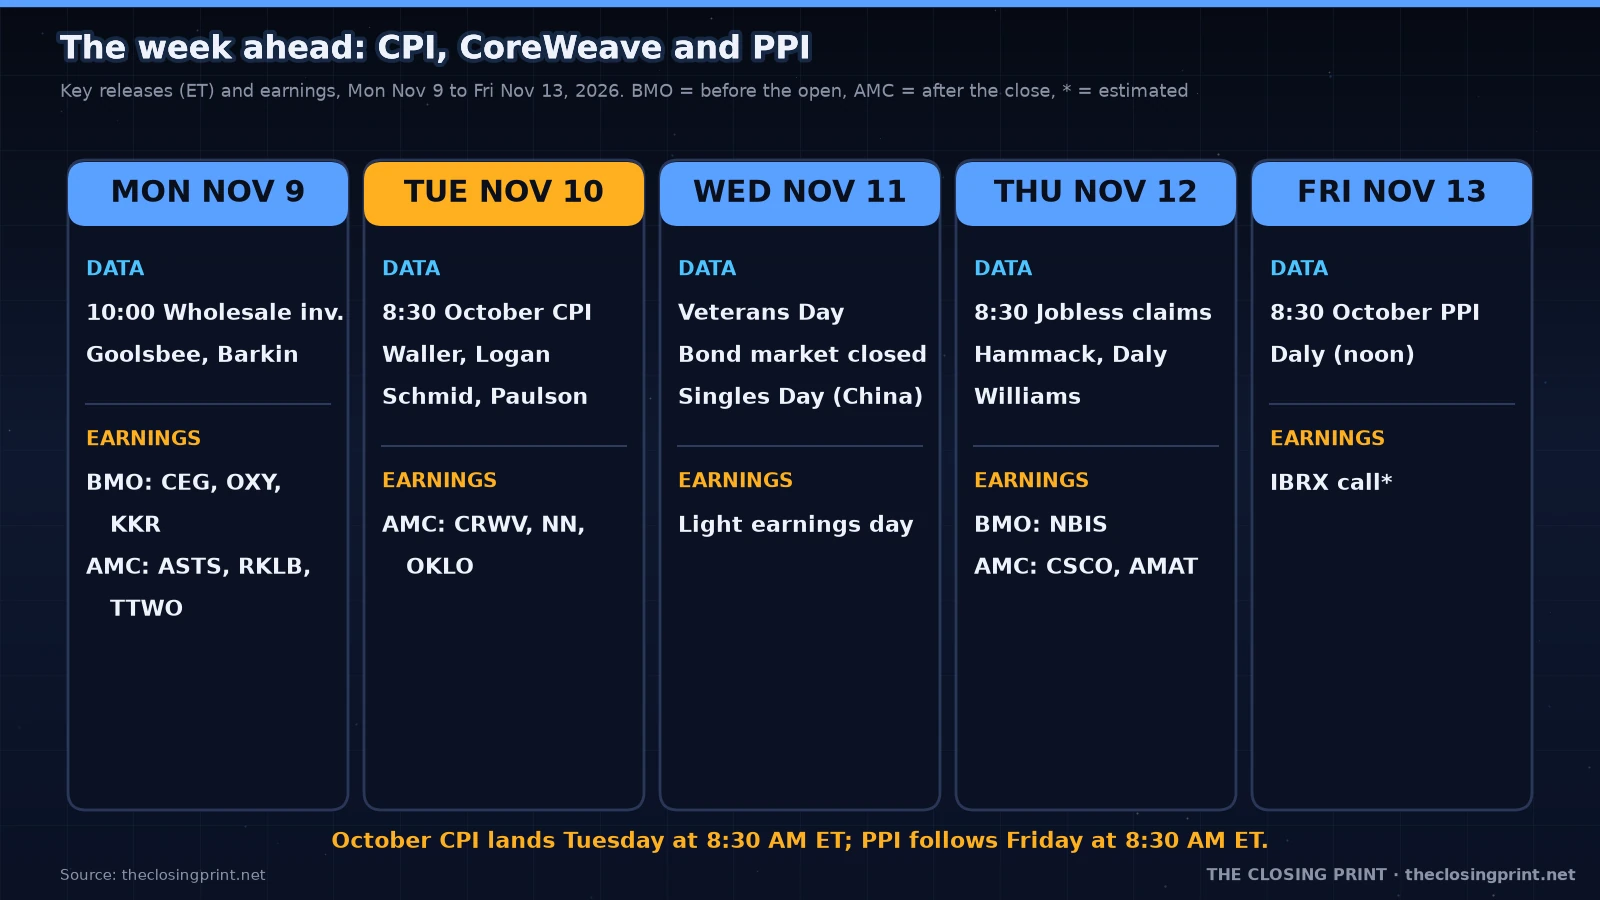
- Data: September wholesale inventories Monday at 10:00 AM; the NFIB small-business survey at 6:00 AM and October CPI at 8:30 AM Tuesday, with headline inflation expected around 3.7% a year; the USDA’s crop report and the EIA’s energy outlook at noon Tuesday; jobless claims Thursday at 8:30 AM and the monthly Treasury statement at 2:00 PM; and October PPI Friday at 8:30 AM. Wednesday is Veterans Day, so the bond market is closed but stocks trade.
- The Fed: Chicago’s Austan Goolsbee speaks Monday at 10:00 AM and Richmond’s Tom Barkin at 12:15 PM. Governor Christopher Waller, Dallas’s Lorie Logan, Kansas City’s Jeffrey Schmid and Philadelphia’s Anna Paulson speak Tuesday. Cleveland’s Beth Hammack, San Francisco’s Mary Daly and New York’s John Williams speak Thursday, and Daly again Friday at noon.
- Earnings: Constellation Energy (CEG), Occidental Petroleum (OXY), KKR (KKR) and Take-Two Interactive (TTWO) report Monday, with AST SpaceMobile (ASTS) and Rocket Lab (RKLB) after the close. CoreWeave (CRWV) reports Tuesday after the close, the week’s big AI test, along with Oklo (OKLO) and NextNav. Nebius (NBIS) reports Thursday morning, and Cisco (CSCO) and Applied Materials (AMAT) report Thursday after the close. ImmunityBio‘s third-quarter call is expected Friday.
Watchlist setups
- ImmunityBio (IBRX) $8.63 Friday (+7.8% on the day, +4.2% on the week): it closed the week up while the market fell, and it is still waiting on topline results from the QUILT-2.005 bladder cancer trial, expected this month, plus a third-quarter call expected Friday. X chatter this weekend was mostly spam pitching chat groups, with a few real posts asking when Q3 results will come. Reddit and Substack sentiment were unavailable for this run. The trial readout, not the tape, sets the next big move.
- NextNav (NN) $8.61 Friday (+7.2% on the day, -25.3% on the week): it bounced Friday after hitting a 52-week low near $8.27 midweek, and it reports Tuesday after the close, with the call at 5:00 PM. X discussion among longtime holders turned frustrated this week, with complaints about management and the slow FCC process and one post noting the stock could be worth very little if the FCC does nothing; others still argue the 900 MHz spectrum is the prize. Reddit and Substack sentiment were unavailable for this run. Any FCC timing update on the call matters more than the numbers.
- SpaceX (SPCX) $134.27 Friday (+8.6% on the day, -0.3% on the week): it jumped Friday with the tech bounce. Monday night’s results from AST SpaceMobile and Rocket Lab are the space read-across, and it should otherwise trade with the Nasdaq.
- Sprott Uranium Miners ETF (URNM) $41.28 Friday (+3.0% on the day, -2.5% on the week): Constellation Energy’s results Monday morning and Oklo’s on Tuesday will test the nuclear-power trade, and the data-center restrictions debate is the overhang.
- Roundhill Memory ETF (DRAM) $39.29 Friday (+6.2% on the day, -18.2% on the week): memory was the center of last week’s chip rout. Applied Materials on Thursday is the chip-equipment check, and CoreWeave’s spending plans on Tuesday matter for memory demand.
- Galaxy Digital (GLXY) $13.66 Friday (+5.2% on the day, -14.6% on the week): bitcoin is slipping tonight near $75,000, which keeps pressure on it; it has no company event this week, so it trades with crypto and the AI-data-center names.
Scenarios and Wick's pick
Monday’s open:
- Bull (30%): the Nvidia news stays contained, chips keep bouncing, and the S&P 500 opens above 7,420 and holds it.
- Base (45%): a flat to slightly higher open near 7,370 to 7,420, with Nvidia lagging and the rest of the market choppy ahead of CPI.
- Bear (25%): Nvidia drags the chip complex lower again and the S&P 500 slips below 7,330.
The week: Bull (30%): a soft CPI cools hike odds and CoreWeave reassures on spending, lifting the S&P 500 back above 7,500. Base (45%): an in-line CPI and mixed AI earnings keep the S&P between 7,250 and 7,500. Bear (25%): a hot CPI cements a December hike, CoreWeave disappoints, and the S&P breaks below 7,250.
Wick's pick: Base for both. A calm Sunday open doesn’t repair last week’s damage, and the Nvidia probe adds a new headline risk to the market’s biggest stock. With the Fed leaning toward a hike and CPI on Tuesday, we expect a choppy range rather than a clean recovery until CoreWeave and the inflation data are out.
What to watch
- Mon Nov 9, 9:00 AM: Constellation Energy Q3 earnings call.
 .ics

- Mon Nov 9 after the close: Rocket Lab Q3 results..ics
- Mon Nov 9 after the close: AST SpaceMobile Q3 results..ics
- Tue Nov 10, 8:30 AM: US October CPI..ics
- Tue Nov 10 after the close: CoreWeave Q3 results..ics
- Tue Nov 10 after the close: NextNav Q3 results..ics
- Thu Nov 12, 8:30 AM: weekly jobless claims..ics
- Thu Nov 12 before the open: Nebius Q3 results..ics
- Thu Nov 12 after the close: Cisco and Applied Materials results..ics
- Fri Nov 13, 8:30 AM: US October PPI..ics
- Fri Nov 13 (estimated): ImmunityBio Q3 conference call..ics
Market data and opinions by Wick. This post is informational only and is not financial advice. Sunday-night futures trade thinly and can reverse before the cash open; scenario odds are our estimates.
Add all 11 events to calendar (.ics) Times are ET. Each event has a 1-day reminder. Estimated dates are marked.