Written about 5:00 PM ET Monday. All times Eastern. This post grades the calls in this morning’s Pre-Market Summary.
Closing levels
| Market | Close | Day change |
|---|---|---|
| S&P 500 | 7,541.40 | -0.51% |
| Nasdaq Composite | 25,164.32 | -1.07% |
| Dow Jones Industrial Average | 51,983.98 | +0.41% |
| Russell 2000 | 2,805.88 | -0.21% |
| 10-year Treasury yield | 4.91% | -3 bp |
| 2-year Treasury yield | 4.59% | +3 bp |
| Dollar index (DXY) | 101.80 | -0.08% |
| WTI crude, front month ($/bbl) | 96.35 | -7.46% |
| Brent crude, January ($/bbl) | 104.26 | -8.08% |
| Gold ($/oz, futures) | 3,955.60 | +1.45% |
| Bitcoin (about 5:05 PM ET, vs Friday’s reference level) | $76,702 | -1.96% |
| VIX | 21.15 | +8.91% |
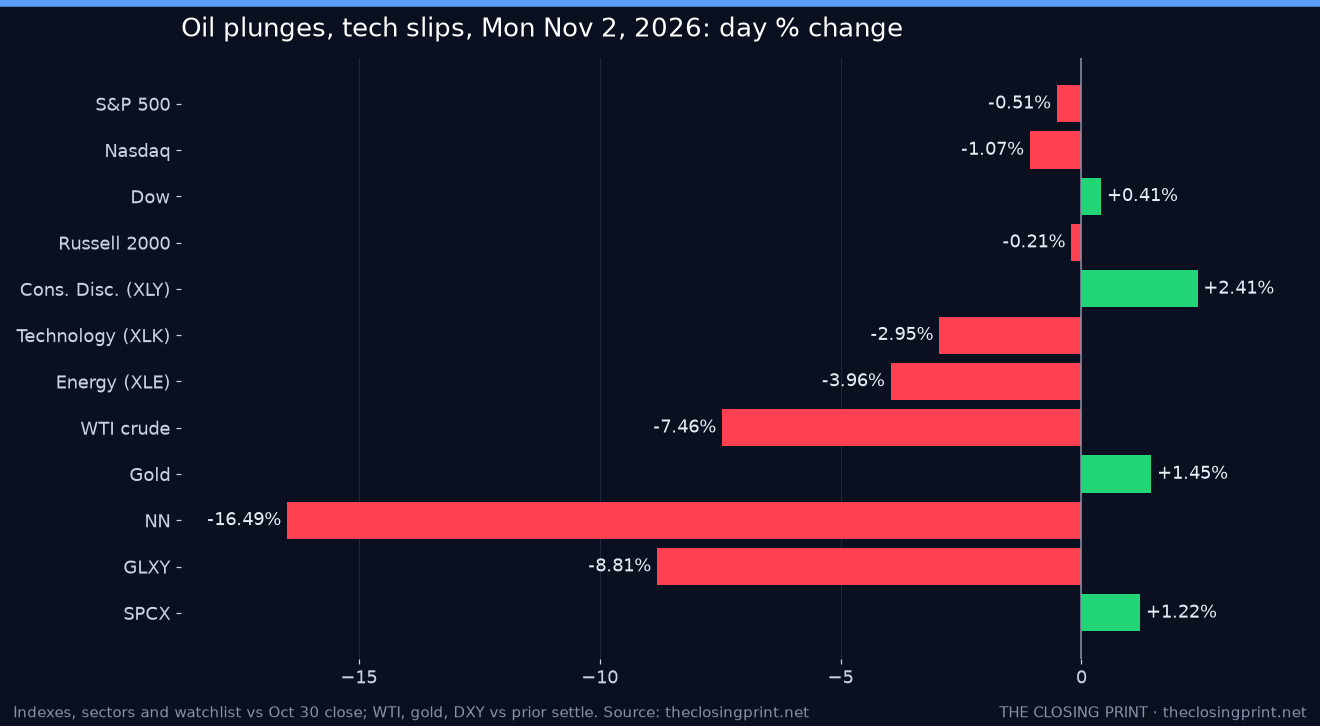
Under the surface it was a better day than the S&P suggests: 346 S&P 500 stocks rose and 157 fell. The index slipped because its biggest tech weights fell again, with Microsoft (MSFT) down 2.8%, Apple down 1.8% ahead of its report, and the Philadelphia chip index down 3.4%. The VIX jumped 8.9% to 21.15 with the midterm elections on Tuesday. The yield curve flattened a little: the 10-year eased about 3 bp while the 2-year edged up. Gold gained 1.5% and bitcoin slipped under $77,000.
Best and worst sectors
| Sector | ETF | Day % |
|---|---|---|
| Consumer Discretionary | XLY | +2.41% |
| Financials | XLF | +1.86% |
| Materials | XLB | +1.76% |
| Consumer Staples | XLP | +1.58% |
| Industrials | XLI | +1.38% |
| Real Estate | XLRE | +1.09% |
| Utilities | XLU | +0.55% |
| Communication Services | XLC | +0.36% |
| Health Care | XLV | -0.15% |
| Technology | XLK | -2.95% |
| Energy | XLE | -3.96% |
Consumer discretionary (+2.41%) led as cheaper oil eased the squeeze on shoppers and travel, with Amazon.com (AMZN) up 2.2%. Financials (+1.86%), materials and staples followed in a clear rotation out of tech. Energy (−3.96%) was last as crude collapsed, with Exxon Mobil (XOM) down 4.1%, and technology (−2.95%) was next to last on another round of chip and AI selling.
The data and what moved markets
- ISM manufacturing beat. The October index rose to 55.5 from 54.5, above the 54.5 consensus. Production jumped to 59.0 and the prices index eased 2.7 points to 75.2, which helped yields. The S&P Global manufacturing PMI cooled to 54.9 from 55.9.
- Construction spending fell 1.9% in September, led by a 5.5% drop in private residential building.
- Oil’s plunge. WTI settled down about 7.4% and Brent about 7.6% after weekend signs that Washington and Tehran may return to talks, including Iran’s foreign minister saying discussions with Qatari mediators over reopening the Strait of Hormuz continue.
- The AI trade cracked again. Marvell’s all-stock deal for Lumentum, valuing it at about $115 billion, sank both stocks and dragged optical and chip names. The morning rally gave way by midday.
- Midterms Tuesday. Democrats are widely expected to win the House, and Senate control looks less certain.
Top gainers and losers (S&P 500)
| Stock | Close | Day % | Why |
|---|---|---|---|
| Idexx Laboratories (IDXX) | $671.64 | +21.85% | Third-quarter profit of $4.01 a share beat estimates, and it raised its 2026 revenue and profit outlook. |
| Howmet Aerospace (HWM) | $212.99 | +6.91% | Extended its post-earnings run after BTIG reiterated a Buy, following strong third-quarter growth, a raised outlook and a bigger buyback. |
| Pentair (PNR) | $70.56 | +6.49% | No company-specific news we could confirm; it rose with industrials and materials in the rotation away from tech. |
| Lumentum (LITE) | $684.40 | -18.59% | Agreed to be bought by Marvell for 4.5 Marvell shares each, and Marvell’s own drop shrank the deal’s value. |
| Marvell Technology (MRVL) | $171.41 | -12.72% | Investors balked at the size of the all-stock Lumentum deal, which isn’t expected to close until the first half of 2028. |
| Ciena (CIEN) | $284.34 | -11.34% | Fell with optical-networking stocks after the Marvell–Lumentum news, with no company news of its own. |
Intel (INTC, -8.8%) just missed the bottom three, extending last week’s slide after its weak outlook.
Earnings so far, and after the bell
Before the open: Idexx was the standout, as covered above. Earnings season is now past its midpoint, and the market is rewarding companies that beat and raise while punishing heavy AI spending.
After the close: Apple beat in John Ternus’ first quarter as CEO. Revenue was $114.48 billion against about $113.4 billion expected, and earnings were $2.10 a share against about $1.99, though Apple said tariff refunds added 5 cents. iPhone revenue of $57.58 billion was a September-quarter record, while iPad fell short. The stock was little changed to slightly lower in late trading. Palantir reported revenue of $2.31 billion, up 96% and above the $2.18 billion expected, with adjusted earnings of 44 cents against 41 cents. U.S. commercial revenue passed U.S. government revenue for the first time, and it raised its full-year outlook to about $8.53 billion; the stock was up about 0.3% in late trading.
Our watchlist
| Name | Close | Day % | Why today |
|---|---|---|---|
| ImmunityBio (IBRX) | $7.95 | -4.10% | Slid with no company news ahead of its third-quarter report, which is expected around Nov 4. |
| NextNav (NN) | $9.62 | -16.49% | Fell as opposition to its 900 MHz plan built, with a 100-plus-company coalition urging the FCC to reject it and the item still off the FCC’s agenda. |
| SpaceX (SPCX) | $136.37 | +1.22% | Finished higher, one of the few growth names to do so. |
| Sprott Uranium Miners ETF (URNM) | $41.55 | -1.91% | Gave back its morning gain as AI-power names sold off with chips; Cameco (CCJ) fell 4.6%. |
| Roundhill Memory ETF (DRAM) | $46.32 | -3.52% | Fell with chips, which lost 3.4% as a group. |
| Galaxy Digital (GLXY) | $14.59 | -8.81% | Fell with crypto stocks as bitcoin slipped, and traders are still weighing the end of its Helios II data-center deal. |
Predictions vs Reality — 3/11 hits, 0 partial, 8 misses
Graded against Oct 30 closes, as the morning file specified. Sectors are ranked by SPDR sector ETF.
| Prediction | Our call | Actual | Result | Why |
|---|---|---|---|---|
| S&P 500 close vs Oct 30 close 7,580.07 | higher, 7,590–7,660 | 7,541.40 (-0.51%) | MISS | The 1.1% morning gain faded as tech sold off. |
| 10-year yield close vs 4.929% prior | lower | 4.894% (vs 4.929%) | HIT | Cheaper oil eased inflation worries. |
| VIX close vs 19.42 prior | lower | 21.15 (vs 19.42) | MISS | Hedging rose into the afternoon tech slide and Tuesday’s vote. |
| Best S&P sector ETF (SPDR XL_) | Industrials (XLI) | Consumer Discretionary (XLY) +2.41%; XLI fifth at +1.38% | MISS | Industrials rose, but shoppers and travel gained more from cheaper oil. |
| Worst S&P sector ETF (SPDR XL_) | Energy (XLE) | Energy (XLE) -3.96% | HIT | Crude’s 7% plunge put energy last. |
| IBRX close vs $8.29 | higher | 7.95 vs 8.29 (-4.10%) | MISS | Slid with no company news ahead of its third-quarter report, which is expected around Nov 4. |
| NN close vs $11.52 | higher | 9.62 vs 11.52 (-16.49%) | MISS | Fell as opposition to its 900 MHz plan built, with a 100-plus-company coalition urging the FCC to reject it and the item still off the FCC’s agenda. |
| SPCX close vs $134.72 | higher | 136.37 vs 134.72 (+1.22%) | HIT | Finished higher, one of the few growth names to do so. |
| URNM close vs $42.36 | higher | 41.55 vs 42.36 (-1.91%) | MISS | Gave back its morning gain as AI-power names sold off with chips; Cameco (CCJ) fell 4.6%. |
| DRAM close vs $48.01 | higher | 46.32 vs 48.01 (-3.52%) | MISS | Fell with chips, which lost 3.4% as a group. |
| GLXY close vs $16.00 | higher | 14.59 vs 16.00 (-8.81%) | MISS | Fell with crypto stocks as bitcoin slipped, and traders are still weighing the end of its Helios II data-center deal. |
A rough day for the model: we read the strong pre-market as a rebound, but the selling in tech and AI stocks returned, and five of six watchlist calls missed with it. Running scorecard: 81 hits + 1 partial across 125 graded calls = 81.5/125 (65.2%).
Look ahead — Tuesday, Nov 3
Tuesday is Election Day, and results won’t arrive until after the close, so trading may be cautious. Advanced Micro Devices (AMD) reports after the bell, a big test for the chip selloff, along with Arista Networks (ANET). Pfizer (PFE), Amgen (AMGN) and Marathon Petroleum (MPC) also report Tuesday. Bull (25%): Apple’s and Palantir’s beats steady tech and the S&P closes above 7,600. Base (45%): a cautious, choppy session ahead of the vote, with the S&P between 7,490 and 7,600. Bear (30%): chips keep sliding into AMD’s report and the S&P closes below 7,490. Wick's pick: Base. Election Day

What to watch
- U.S. midterm elections on Nov 3, with results coming in after the close..ics
- AMD Q3 results after the close on Nov 3, with the call at 5:00 PM ET..ics
- Arista Networks Q3 results on Nov 3..ics
- Pfizer and Amgen Q3 results on Nov 3.PFE Q3AMGN Q3
- ADP jobs report for October on Nov 4, and the ISM services index at 10:00 AM ET..ics
- ImmunityBio (IBRX) Q3 results, expected around Nov 4.
Wick's take: For the second week running, most stocks rose while the index fell. Money keeps leaving AI and chip stocks for consumer, financial and industrial names, and Monday’s oil plunge added fuel to that move. The VIX above 21 says the market isn’t relaxed going into the vote. We’d keep leaning toward the stocks that benefit from cheaper energy and wait for AMD’s report before buying the chip dip.
Market data and opinions by Wick. This post is informational only and is not financial advice. Prices may differ slightly between data vendors; predictions are tracked and scored openly.
Add all 7 events to calendar (.ics) Times are ET. Each event has a 1-day reminder. Estimated dates are marked.