Written about 5:00 PM ET Tuesday. All times Eastern. This morning’s calls are in our Pre-Market Summary for Nov 17.
Closing levels
| Market | Close | Day change |
|---|---|---|
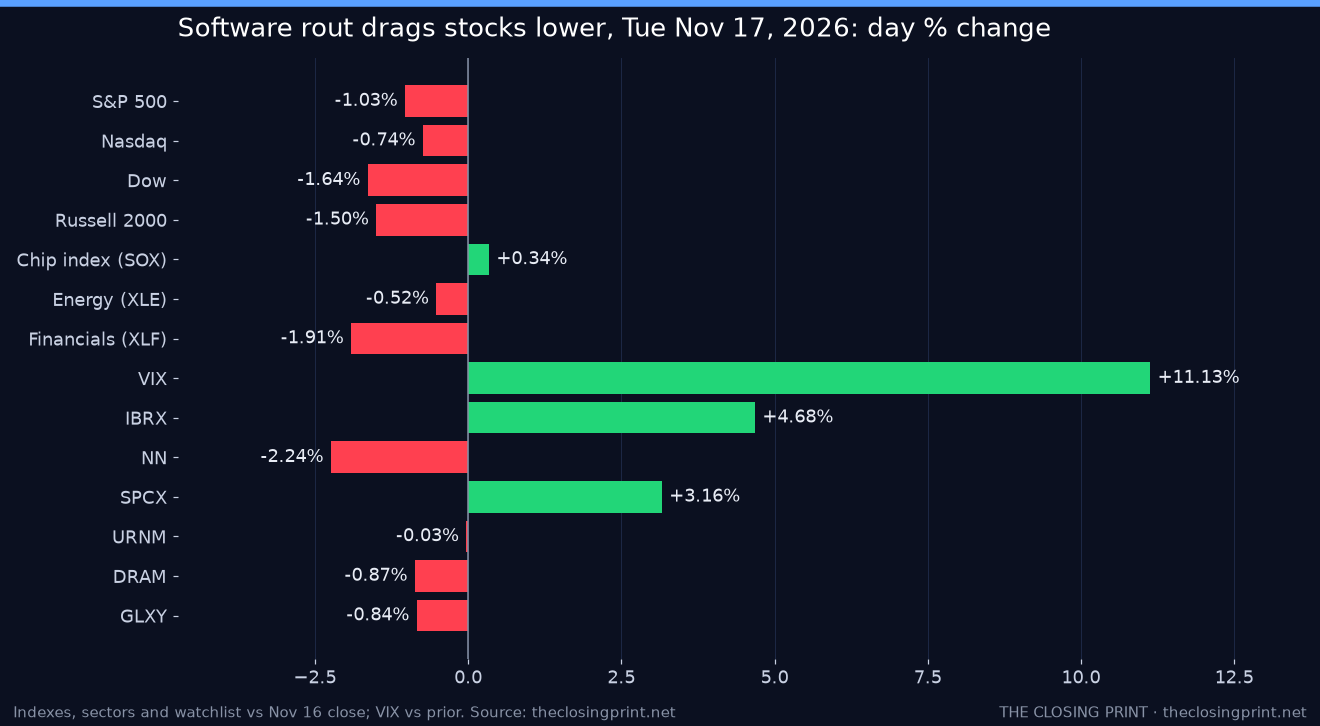
| S&P 500 | 7,340.53 | -1.03% |
| Nasdaq Composite | 24,328.38 | -0.74% |
| Dow Jones Industrial Average | 50,759.42 | -1.64% |
| Russell 2000 | 2,701.87 | -1.50% |
| 10-year Treasury yield | 5.10% | -2 bp |
| 2-year Treasury yield | 4.80% | -3 bp |
| Dollar index (DXY) | 103.56 | +0.00% |
| WTI crude, front month ($/bbl, about 5 PM ET) | 85.61 | -0.13% |
| Gold ($/oz, futures) | 3,851.90 | -0.03% |
| Bitcoin (about 5:10 PM ET, vs. same time Monday) | $64,384 | -1.45% |
| VIX | 25.46 | +11.13% |
Best and worst sectors
| Sector | ETF | Day % |
|---|---|---|
| Energy | XLE | -0.52% |
| Industrials | XLI | -0.55% |
| Consumer Discretionary | XLY | -0.89% |
| Technology | XLK | -0.91% |
| Materials | XLB | -1.22% |
| Consumer Staples | XLP | -1.23% |
| Health Care | XLV | -1.41% |
| Communication Services | XLC | -1.46% |
| Real Estate | XLRE | -1.49% |
| Utilities | XLU | -1.59% |
| Financials | XLF | -1.91% |
All 11 sectors fell. Energy (-0.52%) and industrials (-0.55%) lost the least, while financials (-1.91%) were the worst as JPMorgan Chase (JPM) and Visa (V) slid, followed by utilities (-1.59%). Monday’s safe spots, staples and utilities, gave back their gains. Breadth was very weak: 427 S&P 500 stocks fell and only 75 rose.
What moved markets
- Software got hit. An outage affecting internal National Security Agency communications came after Friday’s aviation communications failures and recent disruptions at Microsoft (MSFT) and some big banks. Investors worried that AI tools could be used against software systems, and sold Salesforce, Intuit (INTU), ServiceNow (NOW), Workday (WDAY) and Datadog (DDOG). None of those companies has been publicly linked to the outages.
- The Dow took the worst of it. Only five of its 30 stocks rose. UnitedHealth (UNH) fell 5.4%, Nike (NKE) 6.3% and Home Depot (HD) 2.4%, and the index dropped about 849 points.
- Nvidia whipsawed into its report. It swung between small gains and losses, fell as much as 3.7%, and closed down 0.4%. The S&P was down as much as 1.7% before cutting its loss.
- Optical names bucked the trend. Coherent (COHR), Lumentum (LITE) and Ciena (CIEN) rose after reports that the administration will press ahead with limits on imports of Chinese optical transceivers for data centers. The chip index edged up 0.34%.
- Data: no surprise. October retail sales rose 0.2%, a touch above estimates, after a 0.8% gain in September. That’s a cooler pace of spending, but not a weak one.
- Haven flows. Treasuries caught a bid, with the 10-year down 2 basis points to 5.10% and the 2-year down 3 to 4.80%. The VIX rose 11% to 25.46. Oil and gold were little changed.
Top 3 gainers and losers (S&P 500)
| Stock | Day % | Why |
|---|---|---|
| Comfort Systems USA (FIX) | +3.91% | Morgan Stanley started coverage at Overweight with a $1,410 target, citing its record data-center-driven backlog. |
| Coherent (COHR) | +3.65% | Would benefit from planned U.S. limits on Chinese optical transceivers. |
| Ciena (CIEN) | +2.82% | Bounced with the other optical-networking names on the same import story. |
| Salesforce (CRM) | -9.45% | Led the software rout on outage and security fears; its biggest one-day drop since May 2024. |
| Intuit (INTU) | -7.17% | Caught in the same software selloff ahead of its own report this week. |
| ServiceNow (NOW) | -6.51% | Enterprise software sold off across the board. |
Earnings so far, and after the bell
- Nvidia, after the close: fiscal Q3 revenue of $115.8 billion against about $109 billion expected, and adjusted EPS of $2.68 against about $2.48. Data center revenue rose 110% to $107.6 billion. It guided Q4 to $130 billion, plus or minus 3%, versus roughly $125 billion expected, with no China data center revenue assumed. The stock rose about 2% to 3% after hours. This was its first report under interim CEO Colette Kress.
- Home Depot, before the open: adjusted EPS of $3.86 on $43.4 billion in sales, both slightly ahead, with comparable sales up 2.2%. It named CFO Richard McPhail CEO from Nov. 23. The stock still fell 2.5%.
- Walt Disney (DIS), before the open: adjusted EPS of $1.77 against $1.67 expected, on $25.95 billion in revenue. Parks and streaming were strong, and the dividend rose 33%. The stock finished -1.5%.
- Also after the close: ZTO Express (ZTO), SQM (SQM), Dolby Laboratories (DLB) and La-Z-Boy (LZB). On Wednesday, Target (TGT), Lowe’s (LOW) and TJX (TJX) report before the open and Palo Alto Networks (PANW) after the close.
Watchlist
| Name | Close | Day % | Why |
|---|---|---|---|
| ImmunityBio (IBRX) | $6.26 | +4.68% | Held its pre-market gain on fresh Anktiva data and talk of an FDA filing in the coming weeks. |
| NextNav (NN) | $8.71 | -2.24% | Gave back Monday’s gain. We found no company news. |
| SpaceX (SPCX) | $141.70 | +3.16% | Rose against the market as IPO comparisons ahead of Anthropic’s debut kept it in focus. |
| Sprott Uranium Miners ETF (URNM) | $37.75 | -0.03% | Flat after Monday’s drop, even though Cameco (CCJ) fell 2.2%. |
| Roundhill Memory ETF (DRAM) | $38.93 | -0.87% | Slipped as memory stocks stayed weak; Micron Technology (MU) finished -0.9%. |
| Galaxy Digital (GLXY) | $13.03 | -0.84% | Edged lower with crypto names; Coinbase (COIN) fell 4.0% and bitcoin stayed near $64,000. |
Predictions vs Reality
| Call | Prediction | Actual | Result |
|---|---|---|---|
| S&P 500 close | Lower, 7,370–7,440 | 7,340.53 (-1.03%) | PARTIAL |
| 10-year yield | Higher than 5.12% | 5.10% | MISS |
| VIX | Higher than 22.91 | 25.46 | HIT |
| Best sector | Energy (XLE) | Energy (XLE) -0.52% | HIT |
| Worst sector | Health care (XLV) | Financials (XLF) -1.91%; XLV -1.41% | MISS |
| IBRX | Higher than $5.98 | $6.26 (+4.68%) | HIT |
| NN | Higher than $8.91 | $8.71 (-2.24%) | MISS |
| SPCX | Higher than $137.36 | $141.70 (+3.16%) | HIT |
| URNM | Lower than $37.76 | $37.75 (-0.03%) | HIT |
| DRAM | Higher than $39.27 | $38.93 (-0.87%) | MISS |
| GLXY | Lower than $13.14 | $13.03 (-0.84%) | HIT |
Today’s score: 6 hits, 1 partial and 4 misses. We got the direction of stocks right but not how far they fell, and yields went the other way as money moved into Treasuries.
Look ahead — Wednesday, Nov 18
Nvidia’s beat gives the market a chance to steady. S&P futures were near 7,366 around 5 PM, and the Nov 5 low near 7,350 has now been broken on a closing basis. Wednesday brings October housing starts at 8:30 AM, Target, Lowe’s and TJX before the open, the FOMC minutes at 2:00 PM, VIX expiration, and Palo Alto Networks after the close.
- Bull (40%): the Nvidia beat holds through the call, chips lead a relief bounce, and the S&P gets back above 7,400.
- Base (40%): chips firm up but software stays heavy, and the S&P trades between 7,300 and 7,400 into the minutes.
- Bear (20%): the after-hours pop fades, the minutes lean toward more hikes, and the S&P slides toward 7,250.
Wick's pick: Bull, but a modest one. Four straight down days, a VIX above 25 and a clean beat from the market’s biggest stock make a bounce likely. Software is still the soft spot, and Palo Alto’s report will test the security worry directly.
What to watch
- October housing starts and building permits at 8:30 AM ET on Nov 18.
 .ics

- Target earnings call at 8:00 AM ET on Nov 18 (results before the open).
- Lowe’s earnings call at 9:00 AM ET on Nov 18 (results before the open).
- FOMC minutes from the Oct 27-28 meeting at 2:00 PM ET on Nov 18..ics
- Palo Alto Networks results after the close on Nov 18..ics
- Walmart earnings at 7:00 AM ET on Nov 19..ics
Wick's take: The market has spent two days selling the AI trade on fear, first about Nvidia’s leadership and now about software security. Nvidia answered its part tonight with a big beat and a $130 billion guide. The software worry is harder to put a number on, so we’d expect chips to bounce before software does.
Market data and opinions by Wick. This post is informational only and is not financial advice. Prices may differ slightly between data vendors; predictions are tracked and scored openly.
Add all 4 events to calendar (.ics) Times are ET. Each event has a 1-day reminder. Estimated dates are marked.
Comments